
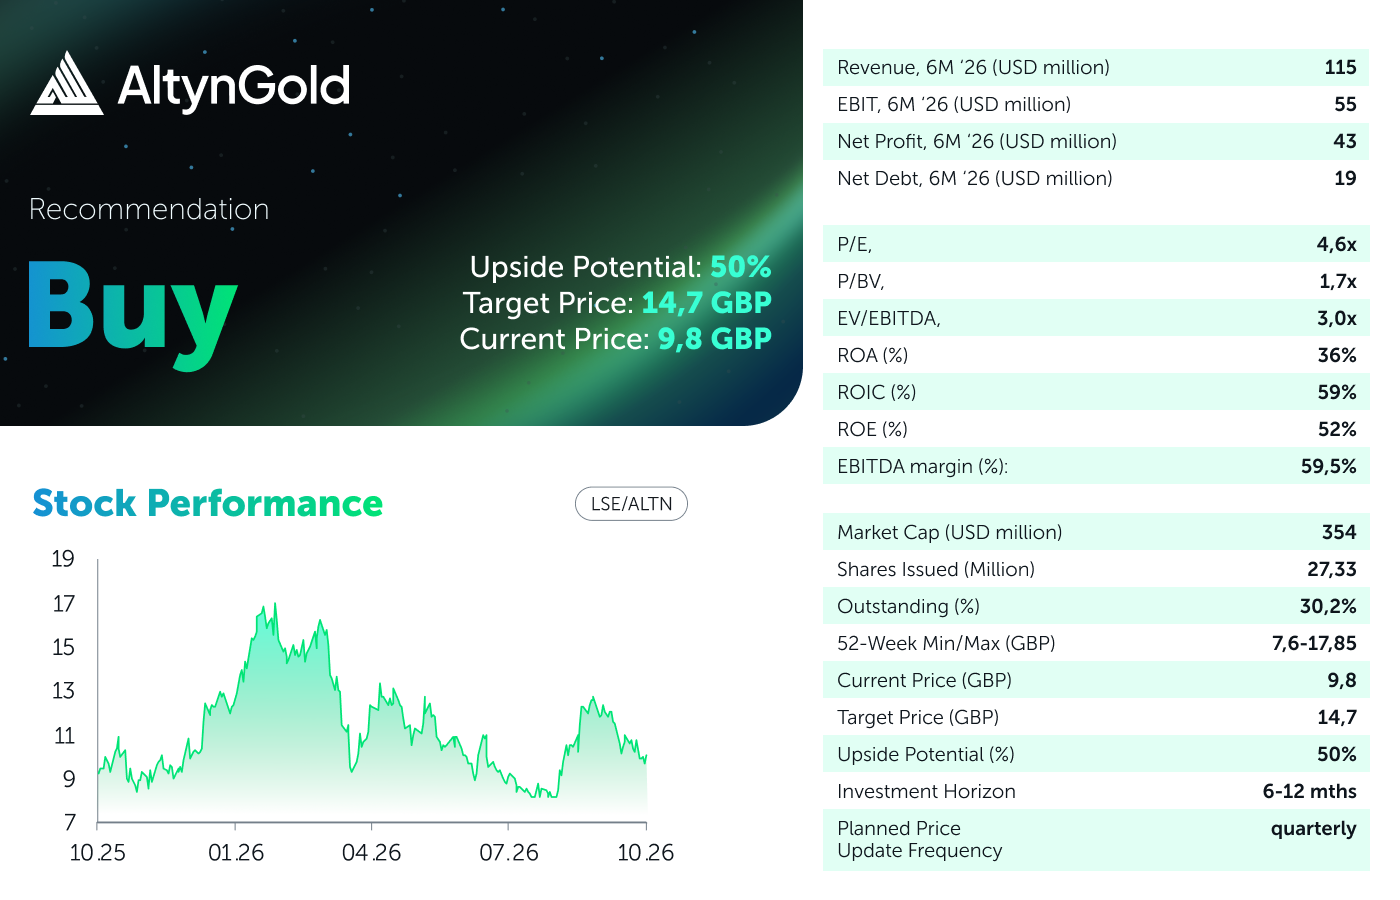
AltynGold PLC has published its H1 2026 performance report. The company continues to deliver growth across key financial metrics, driven by higher market gold prices. However, margins came under pressure due to the increase in the mineral extraction tax rate from 7.5% to 11%, the appreciation of the tenge against the US dollar, and a 14% YoY decline in gold grades. The EBITDA margin decreased by 3.5 percentage points to 59.5%, which nevertheless remains historically high for the company. Capital expenditures reported in the cash flow statement nearly tripled, largely due to development spending and the expansion of operating activities. In our valuation model, we increased our long-term gold price forecasts by 38%, while also raising production costs and the cost of capital amid higher government bond yields in the market. As a result, our target price for one AltynGold PLC share decreased from GBP 14.9 to GBP 14.7, implying 50% upside potential. We maintain our “Buy” recommendation.
Core Valuation Factors. The key valuation driver is the gold price: the average realized price in the first half of the year was $4,615/oz, 34% above the 2025 level. However, following the September correction, gold is trading at around $4,200/oz, 9% below the first-half average. Therefore, revenue growth in the second half will depend more heavily on production volumes. The second factor is the recovery in gold grades. Following the completion of the transition between ore bodies in April, grades increased from 1.68 g/t in Q1 to 1.84 g/t in Q2. To meet the second-half production target of 52,000–55,000 oz, grades of approximately 2.1–2.3 g/t will be required. The third catalyst is the expansion of Sekisovskoye. The ordered equipment will increase the processing plant’s capacity by 200,000 tonnes per year (+20%), while a decision on further expansion to 2–2.5 million tonnes per year is expected by the end of 2026. The fourth factor is Teren-Sai. In August, the Ministry approved an extension of the subsoil use contract. The company will apply to proceed with mining at Areas 2, 4 and 5 and will publish a new resource estimate. The key risk is the term of the Sekisovskoye mining licence, which expires in 2029. Without an extension of the licence or the timely launch of Teren-Sai, the terminal value in the DCF valuation would be significantly constrained. The second risk is rising costs: AISC increased to $1,995/oz, up 30% from 2025. The company also plans to invest $95 million in 2026–2028 and repay $20 million of bonds in 2027–2028, which could limit dividend potential over the next 1–2 years.
(+) Revenue continues to grow, driven by higher gold prices. Revenue for the first half of 2026 amounted to $115 million, up 65% year over year. The increase was largely driven by a 50.3% YoY rise in the average realized gold price to $4,615/oz, while gold sales volumes increased by 9% YoY to 24.6 thousand ounces. Compared with the second half of 2025, the company produced 17% less gold, while mined ore volumes declined by only 3.7% HoH. The main factor behind the decline was a 14% YoY and 15% HoH decrease in gold grades. Grades fell from 2.08 g/t in H2 2025 to 1.76 g/t, the lowest level since 2020. Revenue increased by 9.3% compared with H2 2025, driven by a 23% HoH increase in the average realized gold price.
(=) Margins are declining, while cash flow turned negative. The company’s gross margin decreased from 57.4% to 52.0%, while the EBITDA margin declined from 63.0% to 59.5%. Costs increased by 86% YoY, driven by higher mineral extraction tax following the increase in the tax rate from 7.5% to 11% amid higher market prices, higher depreciation and amortization due to increased capital expenditures, and the appreciation of the tenge against the US dollar, which affected the tenge-denominated portion of expenses. AISC increased from $1,299 to $1,995 per ounce, while cash operating costs rose from $980 to $1,640 per ounce. Nevertheless, supported by higher gold prices, EBITDA increased by 55% YoY to $68.5 million, while first-half net profit rose to $42.7 million, or $1.56 per share (+58% YoY). Moreover, compared with H2 2025, the EBITDA margin increased from 55.5% to 59.5%. Free cash flow turned negative at –$1.2 million. This was mainly due to supplier advances, higher VAT receivables, and a 198% YoY increase in capital expenditures reported in the cash flow statement. Most of the capital expenditures were related to development and expansion. Spending included one-off mining works associated with the transition between ore bodies and the purchase of processing equipment that will increase processing capacity by 200,000 tonnes per year. This is expected to increase annual gold production by approximately 20%, assuming all other parameters remain unchanged. Net debt amounted to $19.3 million, down 43% YoY but up 4.7% from the end of 2025.
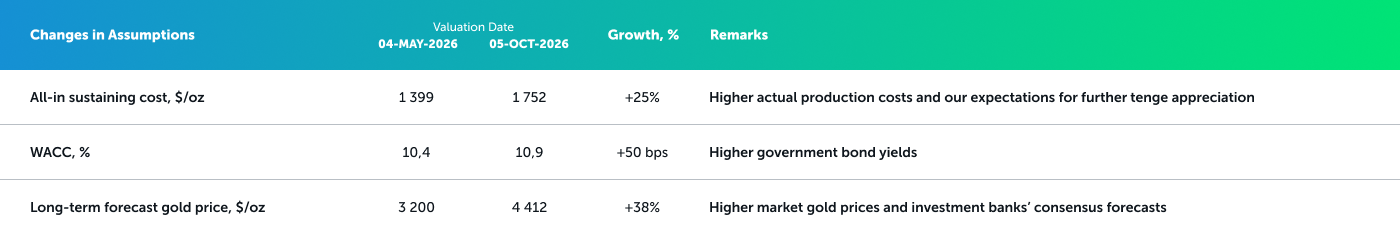
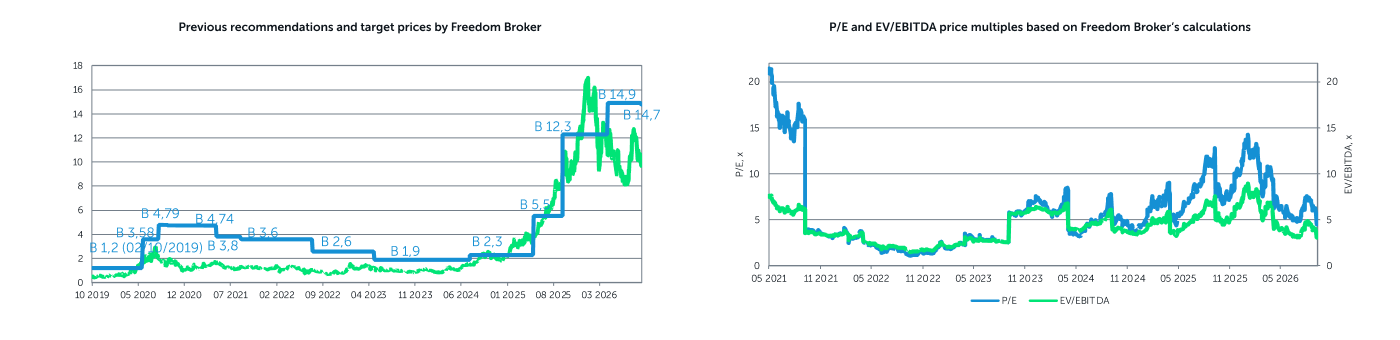
Our Opinion. The company published strong H1 2026 results, setting new records for revenue, EBITDA and net profit. The weaker aspects of the report were the decline in gold grades, higher unit costs and negative FCF, but we believe these factors are largely temporary. Gold grades have been recovering since April. The cash outflow was driven by advances for equipment and the accumulation of $35.9 million in VAT receivables, which is almost twice the company’s net debt. At the same time, the 52,000–55,000 oz production target appears ambitious, while gold is currently trading below the average realized price in H1. The key near-term catalysts will be the new Teren-Sai resource estimate and the decision on the expansion of Sekisovskoye expected by year-end. In our valuation model, we raised our forecast gold price to the level of investment banks’ consensus forecasts, while also increasing production costs and the cost of capital. As a result, our target price for AltynGold PLC decreased from GBP 14.9 to GBP 14.7, implying 50% upside potential from the latest market price. The recommendation is Buy.
Author: Daniyar Orazbayev,
CFA, Investment Analyst
+7 (727) 311 10 64 (688) | [email protected]