
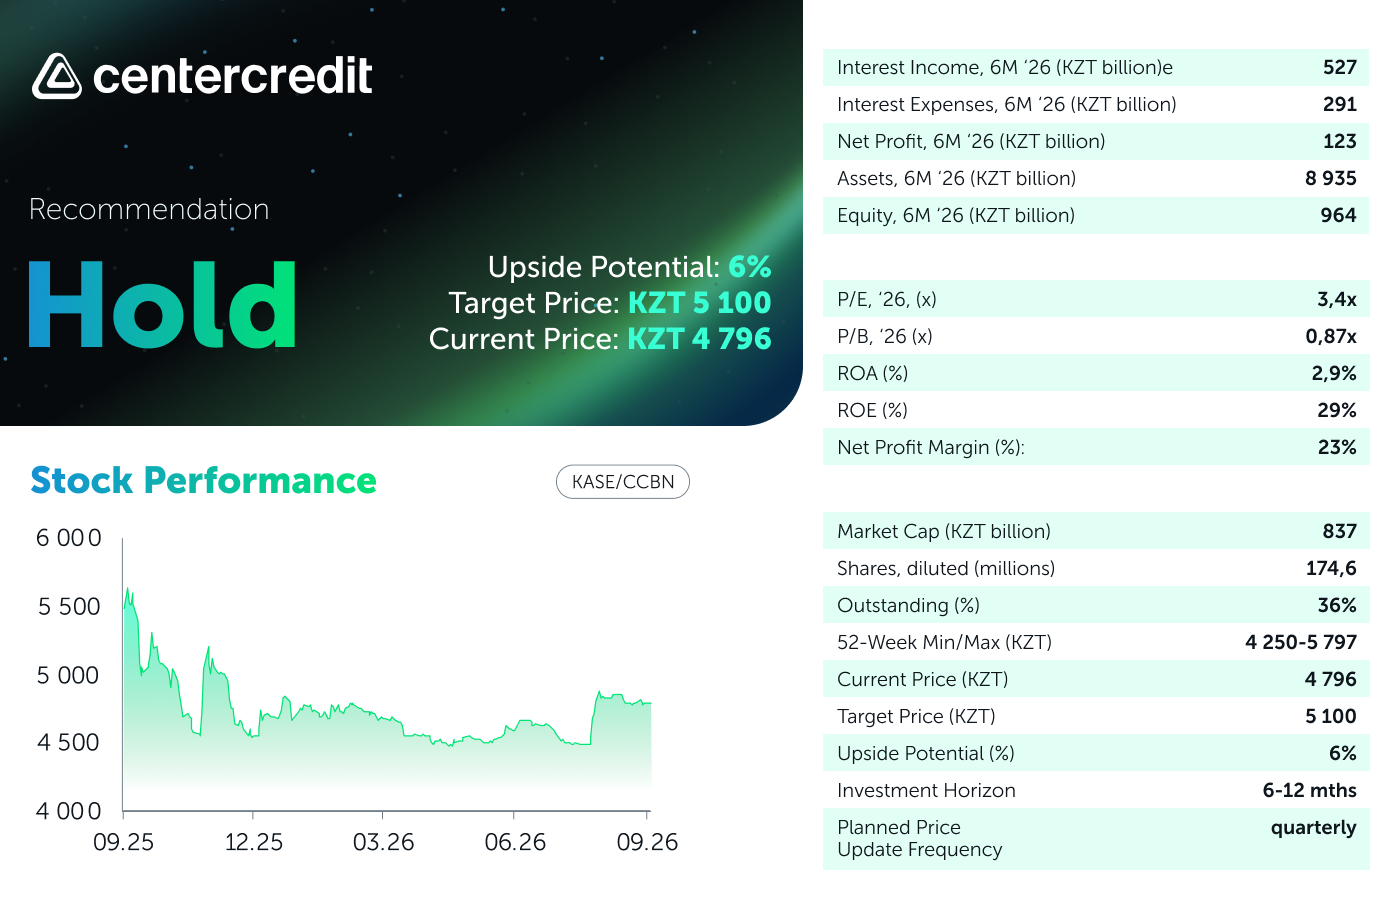
Bank CenterCredit has reported its performance for the Q2 2026. We assess the report as neutral, as quarterly net profit remained broadly unchanged both year-on-year and quarter-on-quarter. Net interest income continues to show year-on-year growth despite higher funding costs. We also note some recovery in non-interest income following a relatively weak first quarter. On the other hand, operating expenses increased sharply in the second quarter due to higher salaries, limiting net profit growth. In our valuation model, we updated the key financial metrics, lowered the cost of equity, and improved our expectations for non-interest income and the loan portfolio. As a result, we have raised our target price for BCC shares from KZT 4,800 to KZT 5,100, implying 6% upside potential from the current level. Our recommendation is Hold.
Interest expenses are growing faster than income. Quarterly interest income amounted to KZT 269 billion (+4.2% QoQ and +19% YoY), reaching a new record for the fourth consecutive quarter. The main contribution came from higher income from customer loans (+7.6% QoQ and +26% YoY). Interest expenses amounted to KZT 151 billion (+8.6% QoQ and +24.4% YoY), outpacing the growth in interest income, with the largest increase coming from customer deposit expenses (+33% YoY). The full repayment of subordinated bonds continues to mitigate the year-on-year increase in expenses. As a result, net interest income before provisions amounted to KZT 118 billion (-1.0% QoQ and +13% YoY).
Higher operating expenses offset the improvement in provisions. Credit loss expenses declined quarter-on-quarter to KZT 21.1 billion (-10% QoQ and +6.7% YoY), which was broadly a positive signal following relatively high levels in the previous two quarters. Net non-interest income increased by 17% YoY and 35% QoQ following a weak first quarter. The year-on-year growth was largely driven by gains on financial assets and a significantly lower level of impairment provisions. Net foreign exchange trading income recovered by 18% QoQ. Operating expenses increased by 33% YoY to KZT 68 billion, primarily due to a sharp 62% YoY increase in salaries, which was the main factor weighing on profit. The tax burden decreased significantly, accounting for only 19% of pre-tax profit, 2.8 pp lower than in the first quarter. As a result, quarterly net profit amounted to KZT 62 billion (+1.4% QoQ and -4.1% YoY), or KZT 352 per share. The net loan portfolio increased by 4% QoQ to KZT 4.8 trillion, with YoY growth reaching 19%. Cash collection of interest income edged down to 93.6% from 93.7% a year earlier. The ratio of liquid assets to liabilities increased during the quarter from 41.9% to 45.3%.
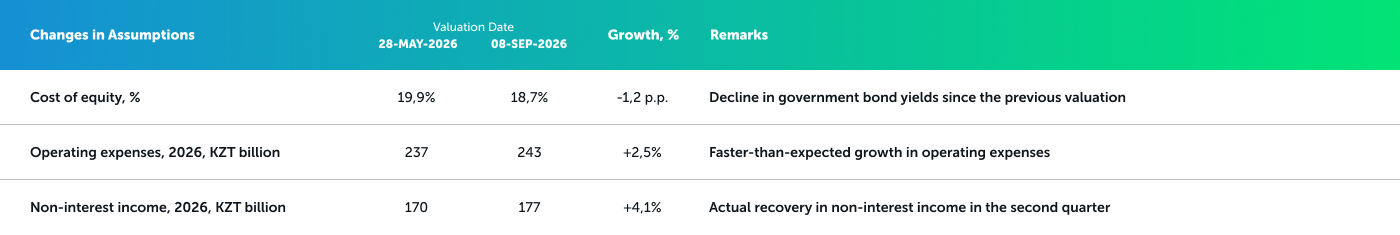
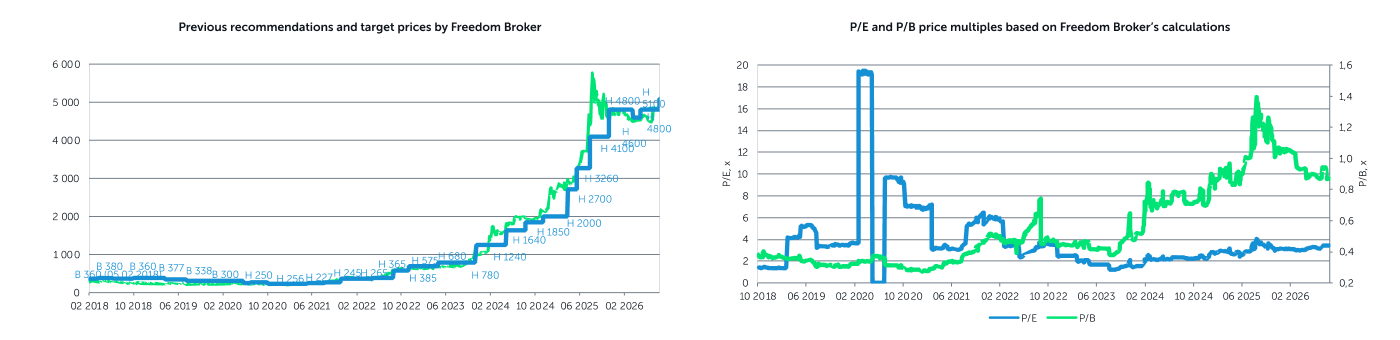
Our Opinion and Changes to the Valuation Model. Among the key risks, we highlight the faster growth in interest expenses, volatility in certain non-interest income items, and the sharp increase in operating expenses. On the other hand, the decline in total non-interest income in the previous quarter did not prove to be a sustained trend, as the indicator recovered this quarter, although the recovery may have been one-off. Positive catalysts include lower credit loss expenses compared with the first quarter and faster loan portfolio growth relative to other publicly listed banks. Overall, we expect funding cost pressures to gradually ease amid the National Bank’s rate-cutting cycle. In our valuation model, we updated the key financial metrics and lowered the cost of equity following the decline in government bond yields since our previous valuation. We also raised our forecasts for non-interest income and the loan portfolio, while lowering our expectations for operating expenses. As a result, we have raised our target price for BCC shares from KZT 4,800 to KZT 5,100, implying 6% upside potential from the latest share price. Our recommendation remains Hold.
Author: Daniyar Orazbayev,
CFA, Investment Analyst
(+7) 727 311 10 64 (688) | [email protected]