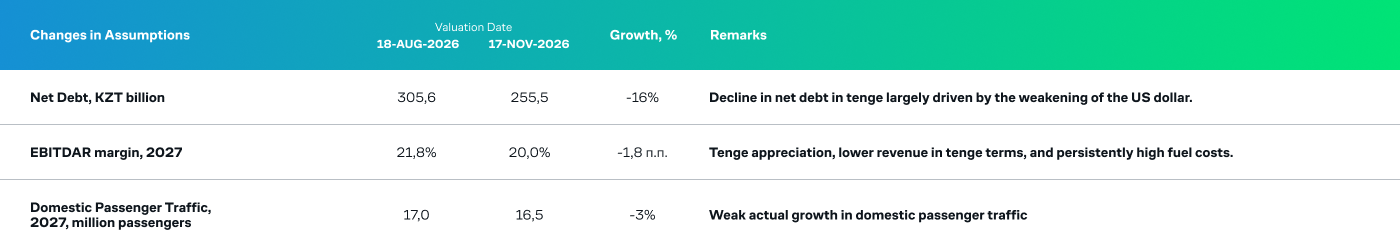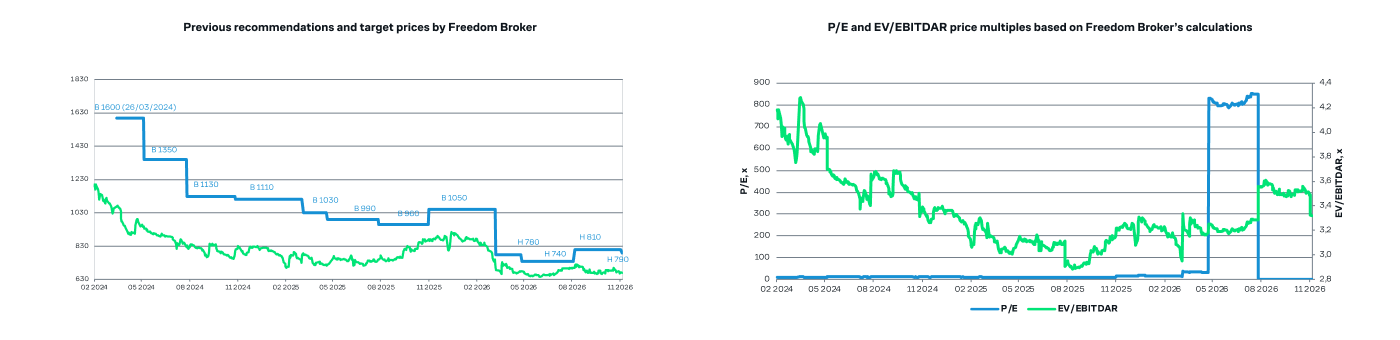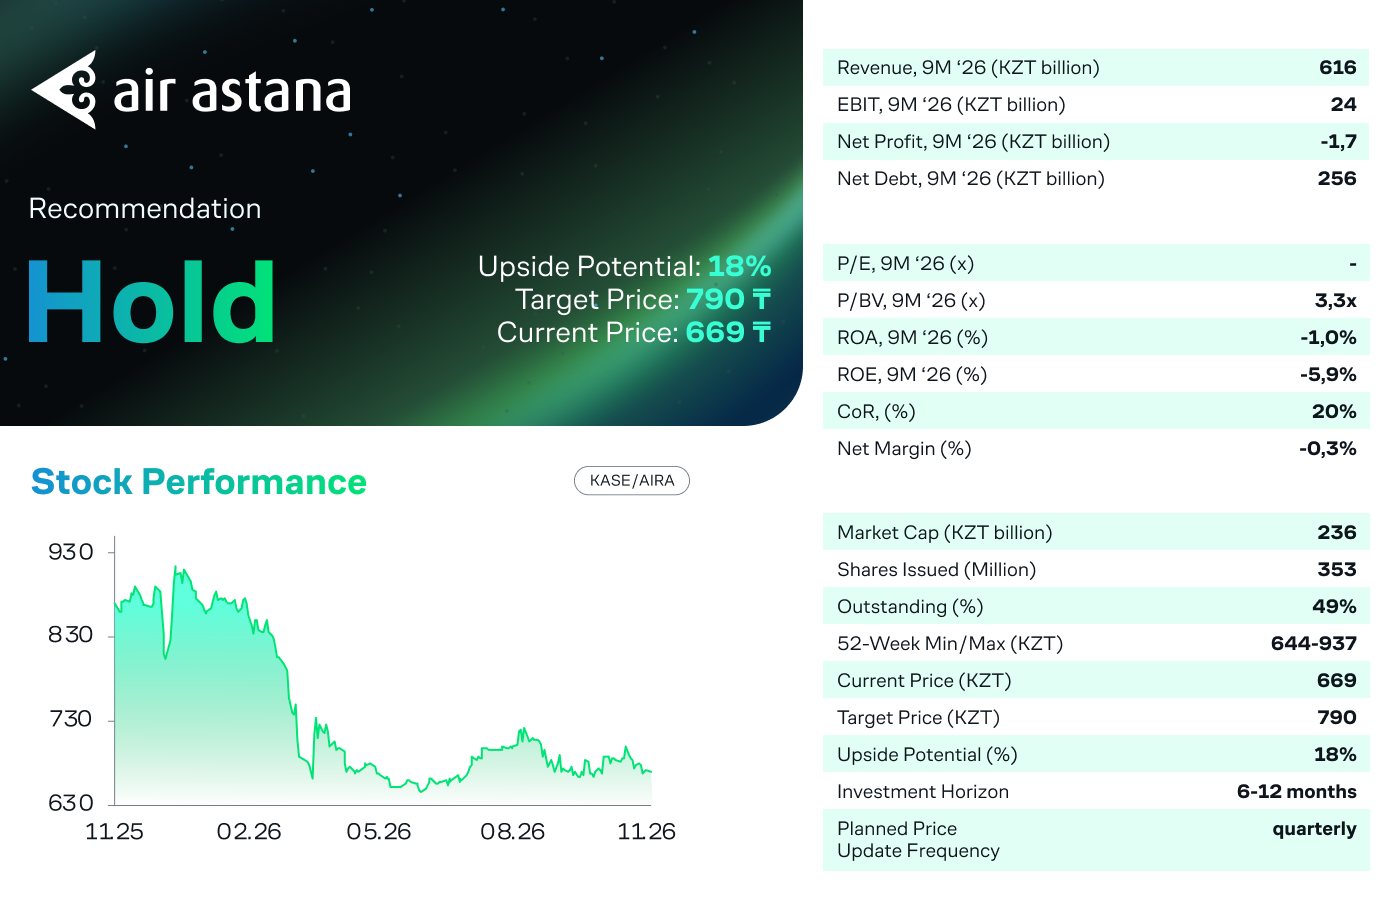
Air Astana JSC has published its financial results for Q3 2026. We view the results as mixed. Revenue in US dollar terms increased by 20.6% year-on-year; however, expenses continued to grow at a faster pace, and the quarterly EBITDAR margin declined from 24.0% to 20.0%. The main pressures remain high fuel costs abroad and Pratt & Whitney engine issues. Nevertheless, improved engine availability has enabled the airline to resume capacity growth, while the gap between the growth rates of expenses and revenue per Available Seat Kilometres (ASK) has narrowed for the third consecutive quarter. The net debt-to-EBITDAR ratio decreased to 1.9x from 2.1x at the end of June. In our valuation model, we have revised our expectations regarding aircraft groundings upwards, while maintaining elevated fuel cost assumptions and factoring in slower growth in the overall air transportation market. As a result, we have lowered our target price per share from KZT 810 to KZT 790, implying 18% upside potential. Our recommendation remains unchanged at Hold.
Core Valuation Factors. The main positive development was the improvement in the Pratt & Whitney engine situation. The number of grounded aircraft decreased by five compared with the third quarter of last year, while the number of engines returned from maintenance in 2026 is expected to be more than three times the 2025 level. Management reaffirmed its target of having no grounded aircraft during the peak summer season of 2027. As a result, Available Seat Kilometres (ASK) increased by 4.0% year-on-year in the third quarter, the highest growth rate since the beginning of the year. The Group is allocating the additional capacity to international routes: capacity to China nearly doubled, capacity to India increased by 23% year-on-year, and international transit passenger traffic rose by 75% year-on-year. The gap between the growth rates of unit costs and unit revenues narrowed to 4 percentage points from 5.5 percentage points in the second quarter. Revenue per Available Seat Kilometre (ASK) increased by 16.0% year-on-year to 7.48 cents, while Cost per Available Seat Kilometre (ASK) rose by 20.0% year-on-year to 6.95 cents. Fuel remains the main risk: the average price at foreign airports increased by 47% year-on-year, following a 98% increase in the second quarter. The Group raised the share of its fuel purchases in Kazakhstan from 71% to 75% and expects fuel cost pressures to persist in the near term. In addition, capacity growth is beginning to
outpace demand: while ASK increased by 4.0%, Passenger-Kilometers Performed (PKP) grew by only 2.0%, and the load factor declined from 85.0% to 83.4%.
Revenue growth is being driven by international routes, while tenge appreciation is weighing on growth in local currency terms. Quarterly total revenue amounted to KZT 245bn (+4.3% YoY), while US dollar-
denominated revenue increased by 20.6% YoY to USD 529 million. The difference was driven by tenge appreciation: the average exchange rate for the quarter declined from KZT 536 to KZT 461 per US dollar. Passenger revenue increased by 3.8% YoY to KZT 239 billion, with scheduled services growing by 4.1% YoY, while charter revenue remained virtually unchanged. Air Astana increased passenger revenue by 4.6% YoY to KZT 176 billion, driven by international routes, primarily the CIS (+12% YoY) and Europe (+6% YoY), while domestic revenue declined by 0.8% YoY. FlyArystan's passenger revenue grew by 1.7% YoY to KZT 63 billion. Revenue per Available Seat Kilometre (ASK), in US dollar terms, increased by approximately 12% at Air Astana and approximately 25% at FlyArystan. By route category, the Group's domestic revenue remained flat year-on-year, while international revenue increased by 6.0–6.2% YoY. The Group's passenger traffic increased by 0.9% YoY to 3.05m passengers. Cargo transportation generated KZT 3.8bn in revenue (+2% YoY).
Expenses are growing faster than revenue, with pressure concentrated at Air Astana. Operating expenses in the third quarter amounted to KZT 227 billion (+7.8% YoY), outpacing revenue growth by 3.5 percentage points, compared with a 5-percentage-point gap in the second quarter. The fastest-growing expense items were passenger services (+22% YoY), engineering and maintenance (+12% YoY), and fuel (+10% YoY), while personnel and airport handling costs remained at last year's levels. At the Air Astana brand level, operating expenses increased by 9.6% YoY, compared with 5.3% revenue growth, and operating profit declined by 43% YoY to KZT 8.5 billion. FlyArystan, by contrast, increased operating profit by 22% YoY to KZT 8.6 billion while reducing expenses by 0.5% YoY. According to the Group, FlyArystan's EBITDAR in US dollar terms grew by 33.9% YoY. As a result, the Group's EBITDAR in US dollar terms remained broadly flat year-on-year (+0.4%), while the EBITDAR margin declined from 24.0% to 20.0%. Quarterly net profit amounted to KZT 8.7 billion (-21% YoY). It was supported by a positive foreign exchange gain of KZT 2.1 billion, compared with a loss of KZT 2.9 billion a year earlier. Excluding foreign exchange differences, pre-tax profit declined by 45% YoY. For the first nine months of the year, the Group reported a net loss of KZT 1.7 billion. Cash holdings at the end of September amounted to USD 511.5 million (-5.2% YoY), while cash as a proportion of revenue declined from 38.3% to 31.0%, remaining above the target level of 25%. Net debt to EBITDAR decreased to 1.9x from 2.1x at the end of June. This remains above the 1.3x recorded a year earlier but is within management's target of below 3.0x.
Our Opinion and Changes to the Valuation Model. In our view, the third-quarter results confirm a gradual improvement in the operating environment: capacity is growing again, the gap between unit
revenue and unit costs is narrowing, and FlyArystan is delivering better results. Nevertheless, the EBITDAR margin remains below the Group's medium-term target range (mid-to-high 20%). Fuel prices abroad and uncertainty over the timing of a full resolution of the engine issues remain key concerns. We have updated the key financial metrics in our valuation model to reflect the latest results. Given the progress in resolving the engine issues, we have revised our aircraft grounding assumptions upwards, while maintaining elevated fuel cost assumptions. For now, the positive impact of reduced aircraft groundings does not offset lower-than-expected actual margins and slower growth in the overall air transportation market. As a result, we have lowered our updated target price for Air Astana shares from KZT 810 to KZT 790, implying 18% upside potential. Our recommendation remains unchanged at Hold.