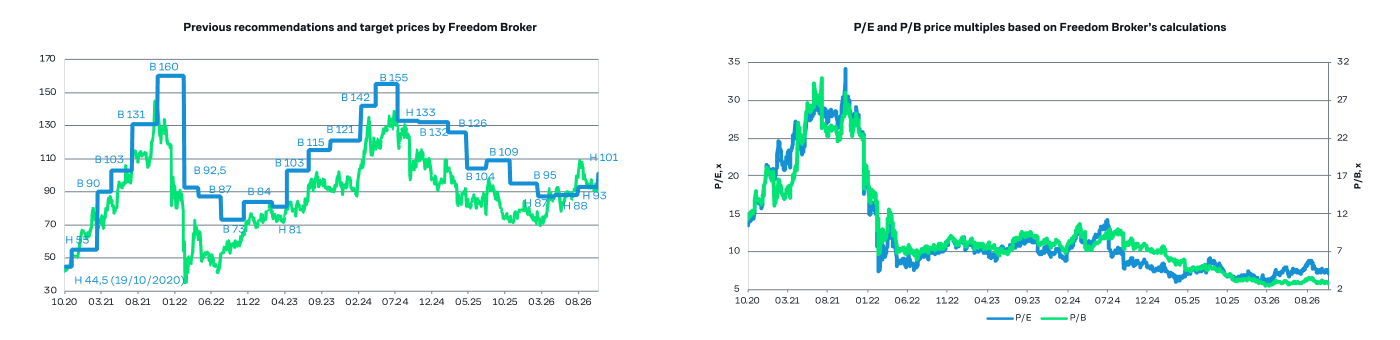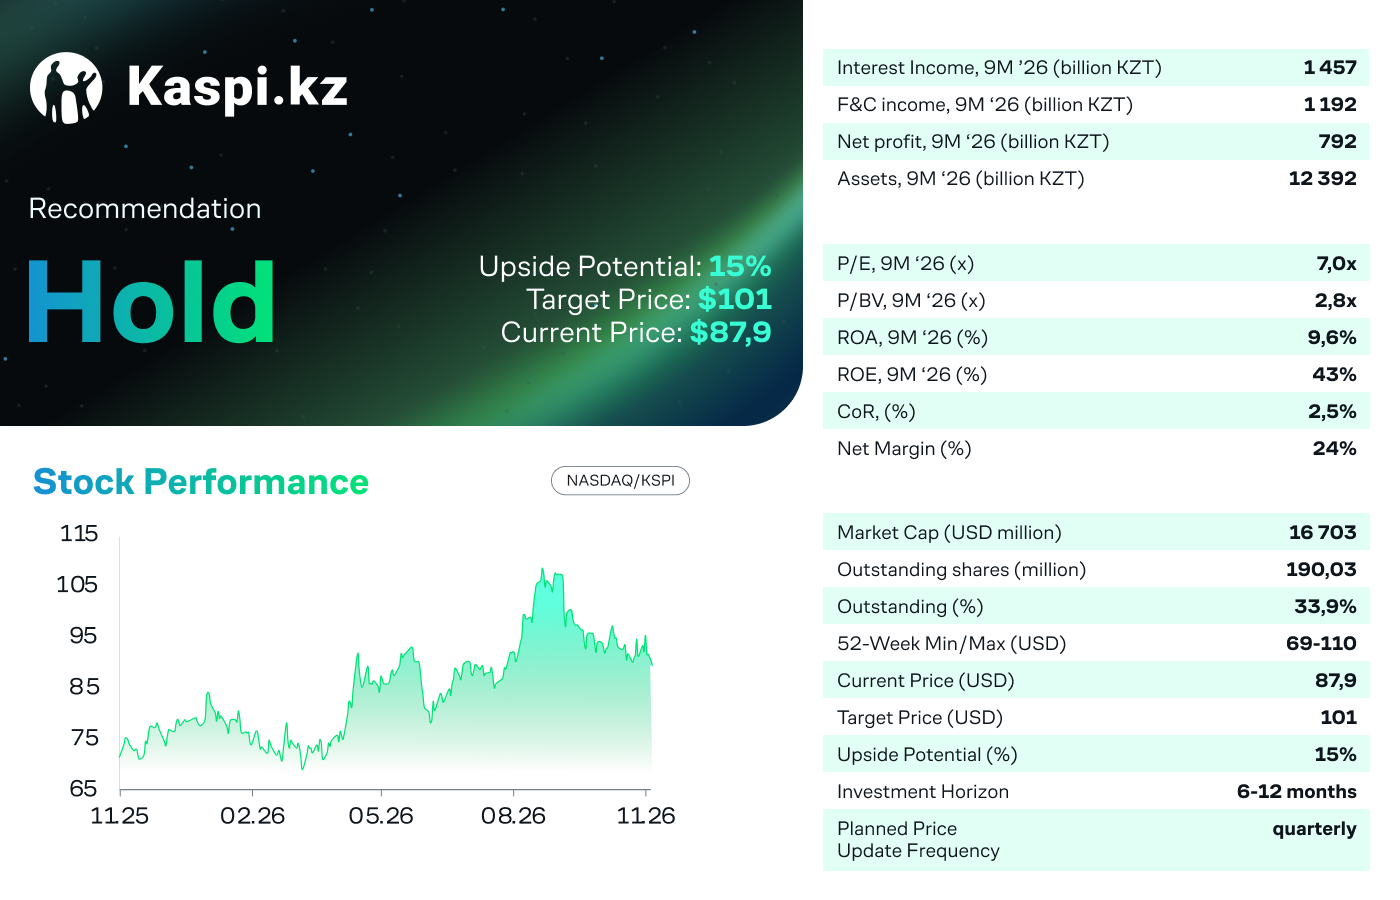
Kaspi.kz JSC published its financial results for the Q3 2026. We assess the report as neutral relative to our expectations. Net profit remains broadly in line with our forecast, at around 1% year-on-year growth. The main negative development was the downward revision of the 2026 Marketplace GMV growth forecast from 20% to 12%. In addition, Turkey-based Hepsiburada reported weaker results in Q3, with its quarterly net loss increasing by 50% year on year in Turkish lira terms. Nevertheless, we note a further slowdown in the growth of interest expenses and record quarterly interest income. The remaining three management forecasts were unchanged, with actual results broadly in line with guidance. The Board of Directors maintained its recommended quarterly dividend of KZT 1,000 per ADR. We updated the key financial metrics in our valuation model, keeping to management's guidance. We also raised our loan portfolio growth expectations and lowered our cost of funding, while the appreciation of the tenge against the US dollar increased our valuation in dollar terms. As a result, we raised our target price per ADR from $93 to $101, implying 15% upside potential. Recommendation: Hold.
Core Valuation Factors. The main risk remains Turkey: Hepsiburada reported negative quarterly adjusted EBITDA, while debt securities outstanding have increased from $0.66 billion to $1.26 billion since the beginning of the year. The tenge's appreciation against the US dollar (20% YoY) and the Turkish lira (32% YoY) as of period-end is weighing on Turkey's reported financial results and the average selling price in Kazakhstan (-8% YoY). To meet the adjusted EBITDA growth forecast of approximately 5%, Q4 needs to deliver growth of around 5% YoY, following 1.4% growth in Q3. Pressure on the interest margin is easing: the gap between the growth rates of interest expenses and interest income narrowed to 1.9 pp, down from 4.0 pp in Q2. An increase in the NPL ratio to 6.9%, from 6.1% at year-end 2025, is adding further pressure. The key growth catalyst remains e-Commerce: GMV in constant currency increased by 17% YoY, purchase frequency rose from 12.8 to 16.3, the take rate increased by 210 bps to 16.3%, and advertising and delivery revenue grew by 42% YoY. Two 100-bp cuts to the three-month deposit rate (in August and October) should reduce the cost of funding, primarily in 2027. The Board of Directors once again recommended a quarterly dividend of KZT 1,000 per ADR, implying an annual dividend yield of approximately 10%.
Revenue is growing, but net profit remains broadly stable, as expected. Interest income reached a record KZT 522 billion in Q3 (+22% YoY, +8.0% QoQ). However, quarterly interest expenses outpaced interest income growth for the fifth consecutive quarter in annual terms (+23% YoY, +6.4% QoQ). The growth differential continues to narrow amid a lower base rate and the tenge's appreciation against the US dollar, which reduced interest expenses on Eurobonds. Gross fee and commission income declined by 5.2% YoY and 2.6% QoQ. Retail revenue also fell by 30% YoY and 17% QoQ. Non-interest expenses decreased by 16% YoY, mainly due to a 23% YoY reduction in the cost of goods and services amid the lira's depreciation against the tenge.
As a result, quarterly net profit amounted to KZT 281 billion (+1.1% YoY, +8.5% QoQ). Net margin, calculated on a quarterly basis using fee and commission and retail income, stood at 25.2%, compared with 25.0% a year earlier.
Marketplace GMV grew by 14% YoY in constant currency over the first nine months, but the 2026 growth forecast was revised down from 20% to 12%. In the Marketplace segment, GMV, including Hepsiburada, increased by 8% YoY in constant currency, falling short of management's previous full-year growth forecast of 20%. One of the key factors was an 8% decline in the average selling price in Kazakhstan, despite a 24% increase in the number of items sold. This was driven by the tenge's appreciation against the US dollar and the Turkish lira, which resulted in an approximately 8% decline in reported GMV in tenge terms. The segment's take rate increased from 11.0% to 11.9%, but quarterly revenue fell by 15% YoY to KZT 466 billion (-8.2% QoQ). Estimated revenue from the Kazakhstan-only segment grew by 14% YoY, pointing to a negative contribution from Turkey. The number of active buyers reached 20.6 million (+4% YoY). In the Payments segment, quarterly TPV increased by 14% YoY in constant currency, broadly in line with management's 2026 forecast of approximately 15%. The number of active users rose by 4% YoY, while the take rate decreased from 1.03% to 1.01%. As a result, quarterly segment revenue increased by 5.7% YoY to KZT 182 billion. In the Fintech segment, the average loan portfolio grew by 14% YoY, slightly below management's current forecast of 15%. Quarterly segment revenue increased by 19% YoY to KZT 489 billion. The average annualised portfolio yield remained unchanged at 24%. The active Fintech user base expanded by 2% YoY to 8.8 million.
Hepsiburada: Rising Losses and Stagnant Operating Performance. Hepsiburada reported year-on-year declines in quarterly revenue (-6.1% YoY) and GMV (-6.6% YoY) in local currency, adjusted for inflation. The quarterly number of orders increased by 0.7% YoY, while the number of active users grew by 1.9% YoY. Quarterly EBITDA turned negative, declining by TRY 360 million, while EBITDA for the first nine months fell by 58% YoY. The quarterly net loss increased by 50% YoY in Turkish lira terms and, according to our estimates, amounted to KZT 24.9 billion. Overall, we consider Q3 a weak quarter for Hepsiburada in terms of financial performance. The tenge's average quarterly appreciation against the lira of 27% YoY also affected the reported results.
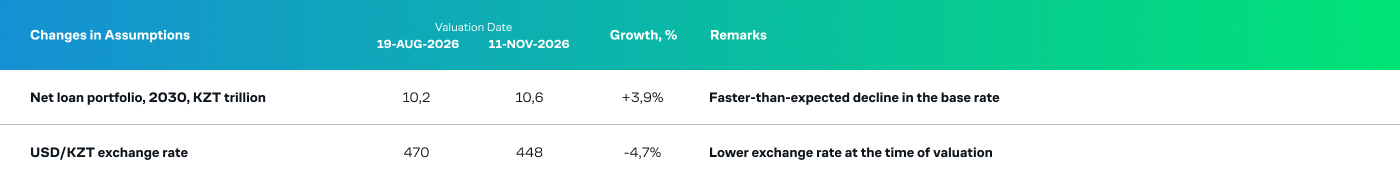
Our Opinion and Changes to the Valuation Model. We consider the third-quarter results neutral. The GMV growth forecast for the Marketplace segment has been revised down from 20% to 12%, primarily due to a decline in the average selling price of goods in Kazakhstan amid the strengthening of the tenge. At the same time, the number of items sold increased by 24% YoY, while Marketplace revenue in constant currency grew by 20% YoY. All other forecasts remain unchanged and are in line with the nine-month results: TPV +14%, average loan portfolio +18%, and adjusted EBITDA +5%. Interest expenses are growing almost in line with revenue (+23.4% vs. +21.5% YoY). Lower deposit rates in August and October should support Fintech profitability in 2027. Turkey remains a capital-intensive market, although management expects a significant reduction in investment in Hepsiburada in 2027. We have updated the key financial metrics in our valuation model. As we had already factored in slower GMV growth in the Marketplace segment, the revision had only a minor impact on our valuation. On the other hand, we raised our expectations for loan portfolio growth and lowered our
cost of funding assumptions amid the decline in the base rate. The depreciation of the US dollar against the tenge also increased the company's value in US dollar terms. As a result, our updated target price for one Kaspi.kz ADR has increased from $93 to $101, implying 15% upside potential. Our recommendation remains unchanged: Hold.