
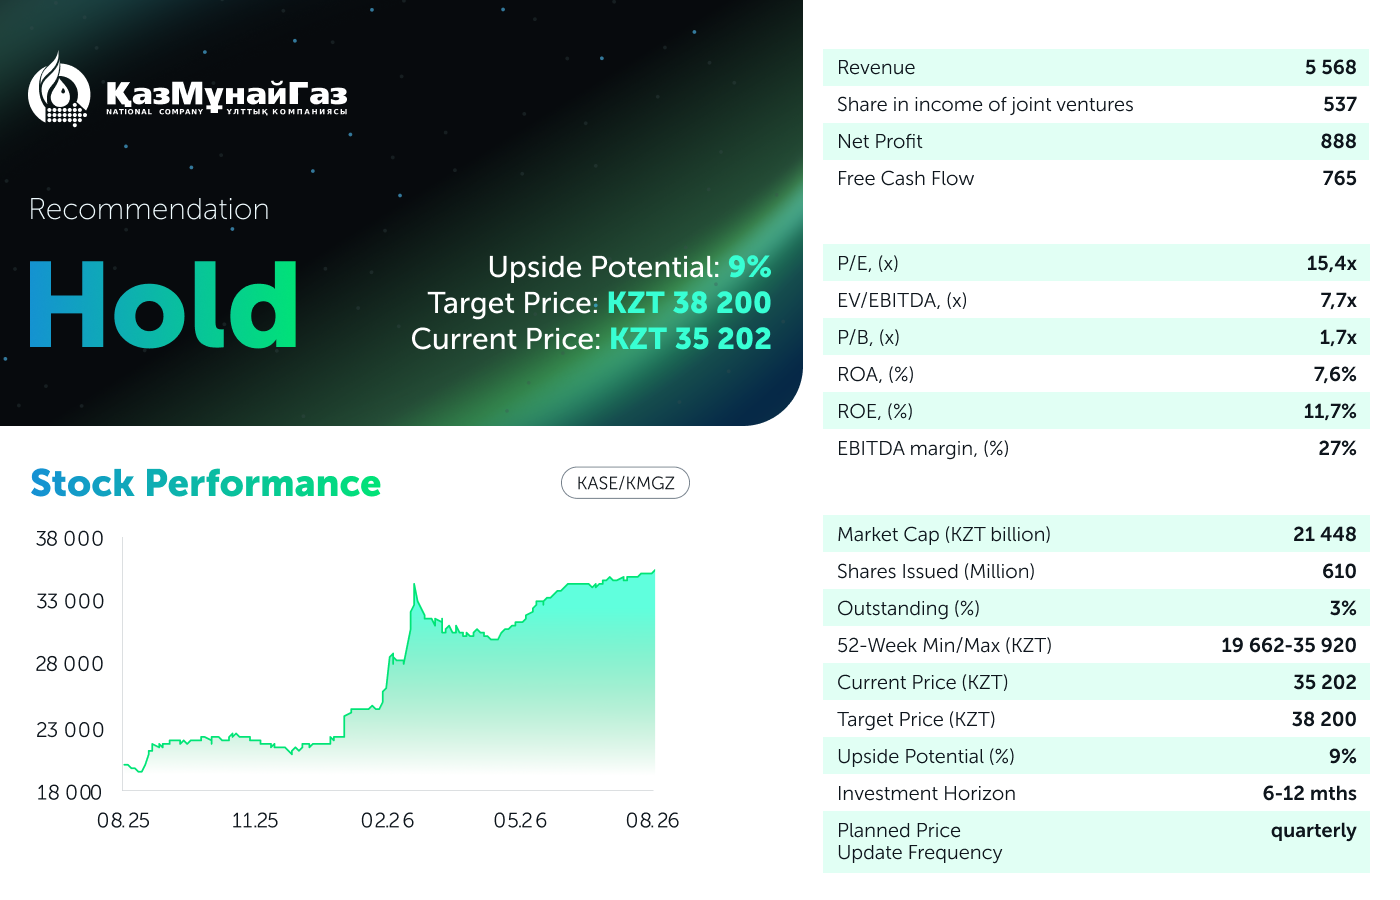
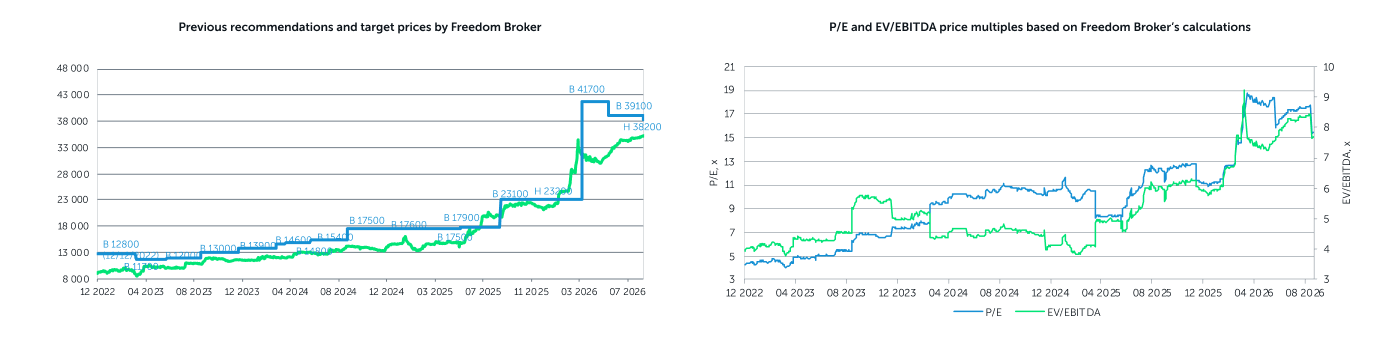
KazMunayGas NC JSC published its financial results for 2Q26. The report is assessed as positive, driven by growth across all key financial metrics. Revenue increased sharply on the back of higher global oil prices. Against this backdrop, EBITDA and, most importantly, free cash flow posted strong growth. As a result, the company’s cash and debt position remains excellent, taking into account the bonds acquired from Samruk-Kazyna. The company also recently announced a $500 million eurobond buyback. From an operational perspective, the quarter was also broadly positive, with modest growth across key operating metrics. We have updated our valuation model to reflect revised financial and operating assumptions, while maintaining our previous oil price forecasts. The appreciation of the tenge was one of the key factors affecting our valuation. We also lowered the cost of capital and the relative valuation of smaller joint ventures, reflecting a decline in KMG’s implied valuation multiple. As a result, we lowered our target price from KZT 39,100 per share to KZT 38,200, implying 9% upside potential, and downgraded our recommendation to Hold.
Core Valuation Factors. Oil prices remained the key driver of the results. In 1H26, the average Brent price increased 28.4% to USD 92.31/bbl, while KEBCO rose 26.9% to USD 92.44/bbl, with the Kazakh grade trading at a USD 0.13/bbl premium to Brent instead of its usual discount. KMG’s share of TCO’s profit reached KZT 263bn in the quarter, compared with KZT 69bn a year earlier, driven by strong oil price growth. However, CPC’s contribution to profit declined 29% YoY to KZT 27bn due to restrictions on the operation of its single-point mooring units. The dividend for 2025 was increased from KZT 491.71 to KZT 573.66 per share. The key negative was the cash position. Cash and deposits declined 18% QoQ to KZT 2.5tn, while net debt increased from KZT 824bn to KZT 1.2tn, as KZT 952bn was allocated to the purchase of Samruk-Kazyna bonds. However, in our valuation model, we adjusted net debt for the carrying value of these bonds. Support in 3Q26 will come from dividends received in July: KZT 97bn from TCO and KZT 41bn from CPC. Key risks include a potential reversal in oil prices, as well as the dependence of production and transportation volumes on the stability of the CPC system.
Revenue: sharp increase amid high oil prices. Quarterly revenue amounted to KZT 3.09tn (+37% YoY), increasing across all segments. Growth was driven by a 52% YoY increase in global oil prices, partially offset by a 7.4% YoY appreciation of the average KZT/USD exchange rate. Revenue from crude oil and gas sales increased 43% YoY to KZT 1.61tn, while petroleum product sales rose 31% YoY to KZT 1.15tn. Oil transportation revenue increased 103% YoY.
Operating volumes also edged up. Oil and gas condensate production increased 2.5% YoY to 6.8mn tonnes, including a 5.2% YoY increase at the major projects, largely driven by an 8% YoY increase at Tengizchevroil (TCO). On a quarterly basis, TCO production increased 91% following the recovery from the transformer fire in 1Q26. Production at operating assets increased 0.2% YoY, supported by the launch of the Zapadnaya Prorva field at Embamunaigas JSC (+7.1%). Oil transportation volumes increased 8.8% YoY to 22.5mn tonnes, driven by a sharp 78% YoY increase in transportation volumes through the Black and Mediterranean Seas. Oil refining volumes declined 0.3% YoY to 5.2mn tonnes due to scheduled maintenance at PetroKazakhstan Oil Products (PKOP), where volumes fell 21%. This was partially offset by a 21% YoY increase in refining volumes at Pavlodar Petrochemical Plant (PNHZ). KMG’s share of profit from joint ventures and associates increased 109% YoY, driven by a 280% YoY increase in TCO’s contribution amid higher oil production and prices. Total revenue including other income amounted to KZT 3.5tn (+39% YoY).
Margins: strong growth in net profit and FCF. The cost of purchased oil and petroleum products increased 47% YoY to KZT 1.78tn, while production expenses rose 8.6% YoY, depreciation and amortization increased 7.5% YoY, and transportation and selling expenses rose 9.2% YoY. Taxes other than income tax increased 56% YoY amid higher oil prices, in line with the increase in the cost of purchased oil and petroleum products. Adjusted quarterly EBITDA increased 45% YoY to KZT 1.03tn, while the EBITDA margin improved from 27.5% to 28.7%. Financial expenses declined 13% YoY to KZT 72bn, supported by lower debt. At the same time, foreign exchange movements had no material negative impact in 2Q26 compared with 1Q26, resulting in a KZT 5.4bn FX gain. As a result, net profit attributable to shareholders increased to KZT 520bn (+53% YoY), or approximately KZT 852 per share. Free cash flow was exceptionally strong at KZT 843bn, up 111% YoY. The sharp increase was driven by a 54% YoY rise in dividends received from joint ventures and, more broadly, a doubling of operating cash flow. Capital expenditures, meanwhile, increased 57% YoY. Based on our calculations, net debt increased 47% QoQ due to the purchase of Samruk-Kazyna bonds. Nevertheless, leverage remains very low, at approximately 0.4x net debt/EBITDA. Adjusting for these bonds, adjusted net debt would have been almost four times lower than in the previous quarter.
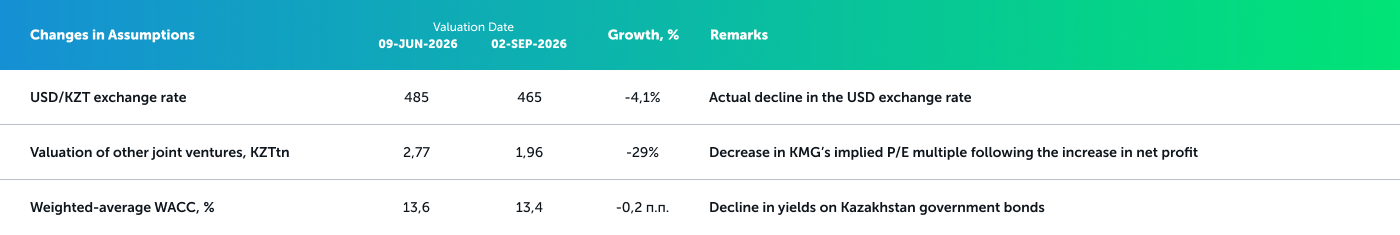
Our Opinion and Changes to the Valuation Model. The results continue to confirm KMG’s dependence on oil prices, while operating volumes remain relatively stable. Our expectations from the previous quarter were largely met: the operational constraints in January proved temporary, while dividends received from joint ventures brought cash flow back into positive territory. In our valuation model, we maintained our oil price forecasts, updated our financial and operational estimates, lowered the cost of capital, and reduced the relative valuation of smaller joint ventures. The appreciation of the tenge had the most significant impact, materially reducing all projected tenge-denominated export cash flows. As a result, we lowered our target price for KazMunayGas from KZT 39,100 to KZT 38,200 per share, implying 9% upside potential. We downgraded our recommendation to Hold.
Author: Daniyar Orazbayev,
CFA, Investment Analyst
(+7) 727 311 10 64 (688) | [email protected]