
Financier №3 (43) 2026
Yerlan Abdikarimov
Director of the Financial Analysis Department, Freedom Finance Global
Prudent Investments
Freedom Broker analysts recommend buying shares of energy companies with high upside potential
Upsides and quotes are as of August 13, 2026.
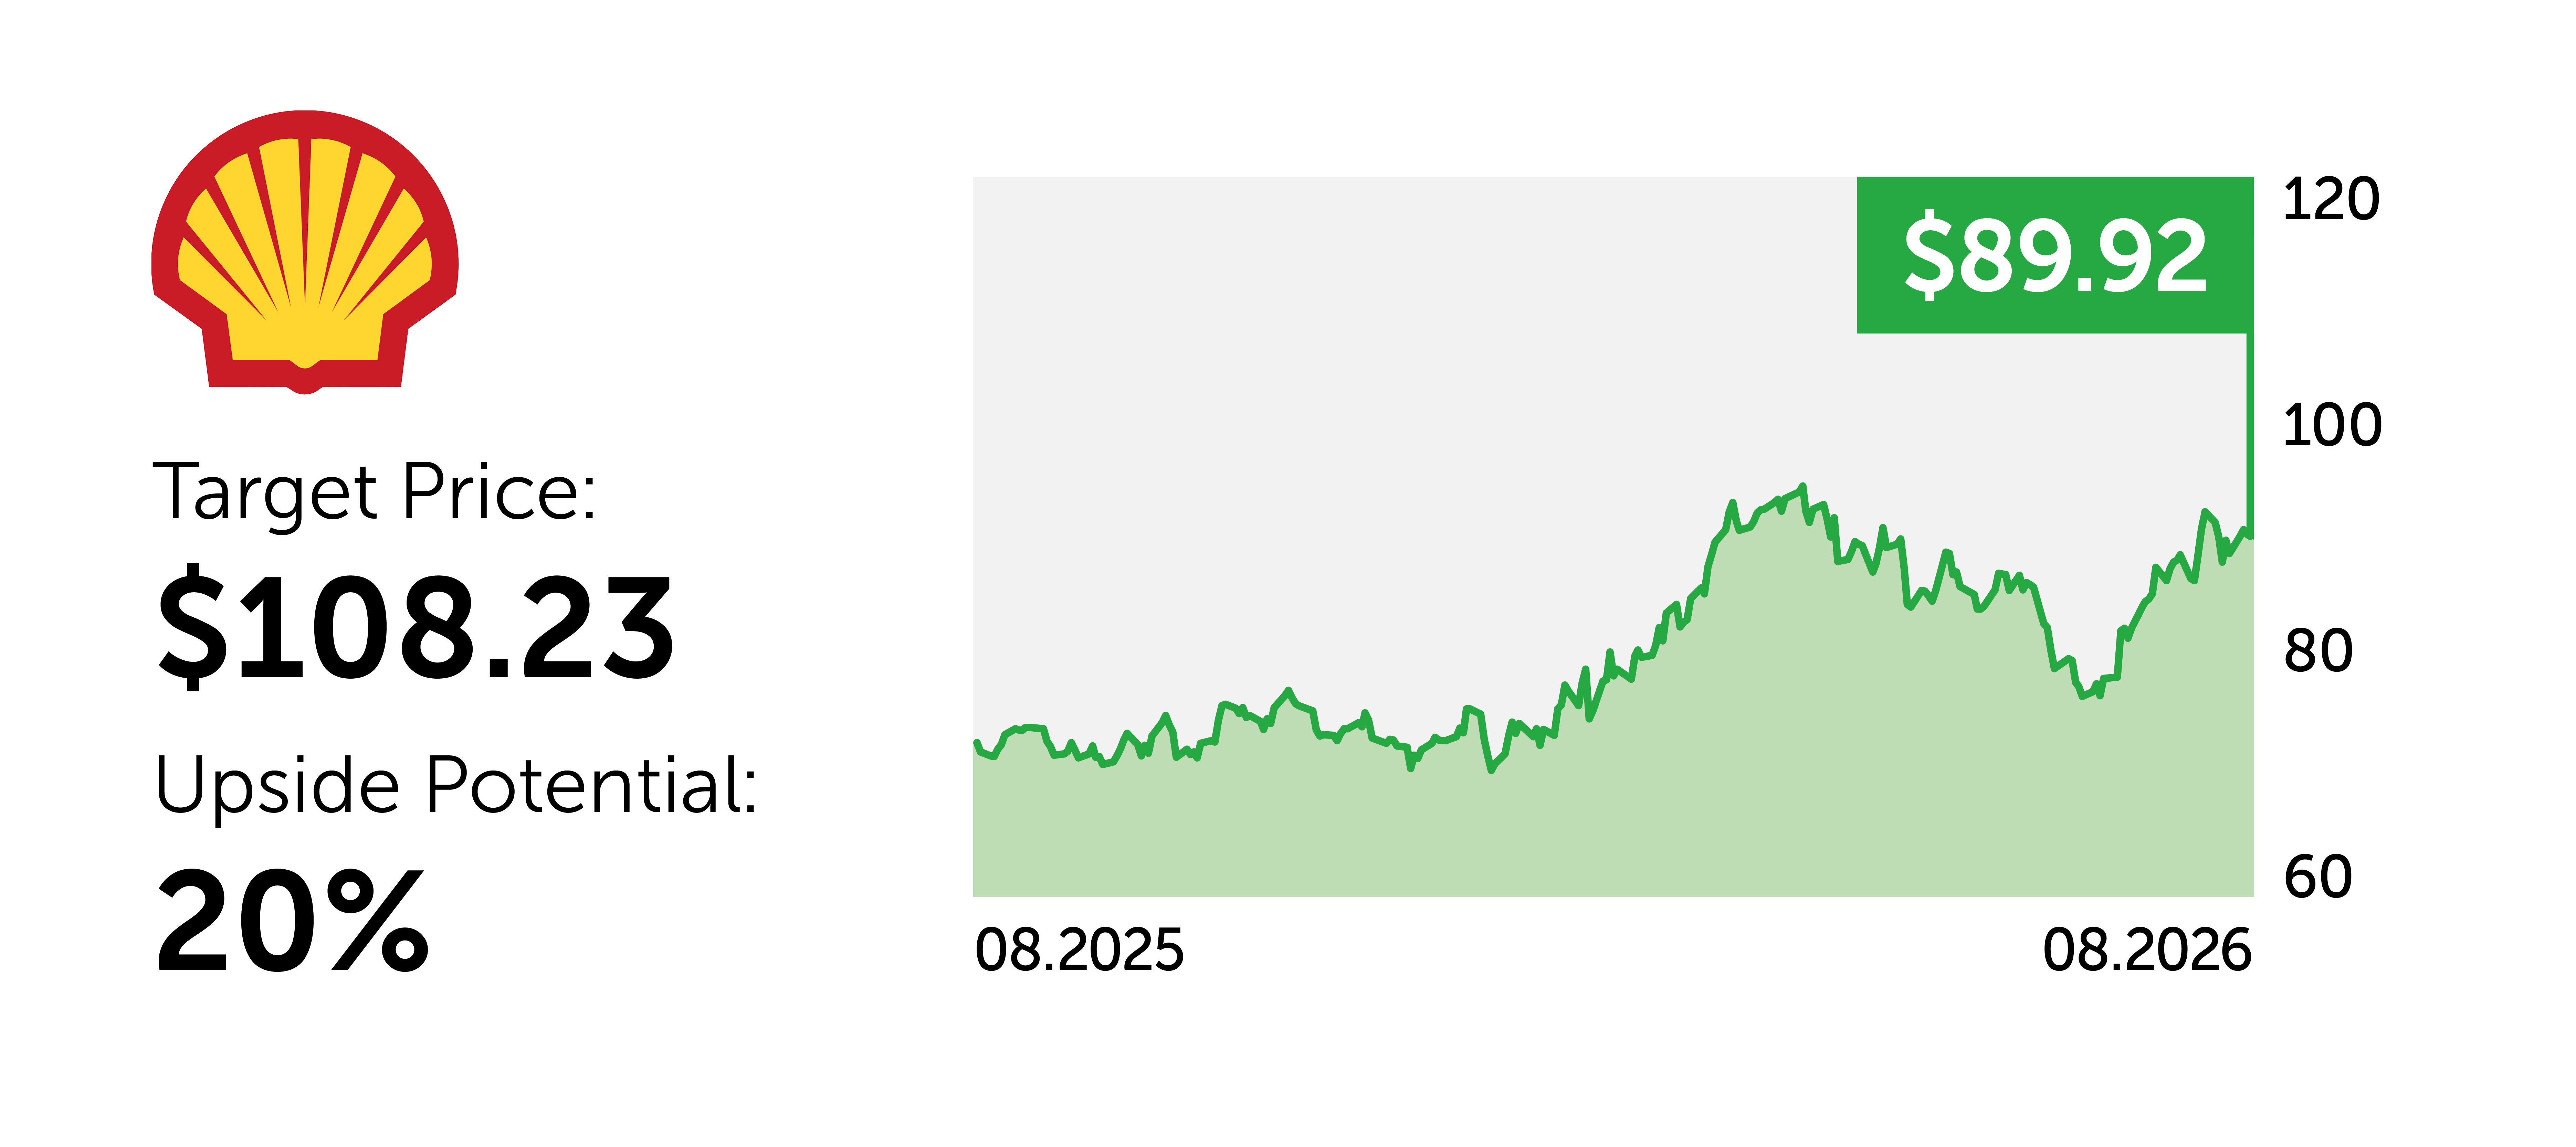
In Q1, Shell (SHEL) posted its highest adjusted net profit in two years - $6.9 billion - driven by higher sales and improved refining margins. The dividend was raised by 5 %, with share buybacks continuing. Following the acquisition of Canadian ARC Resources for $16.4 billion (approved by its shareholders), Shell’s resource base will be strengthened in the Montney gas‑bearing basin. This will provide additional feedstock supplies for the LNG Canada project. As a result, Shell will gain a more robust platform for its gas business development, although the increased debt and integration of a major acquisition will require disciplined capital allocation.
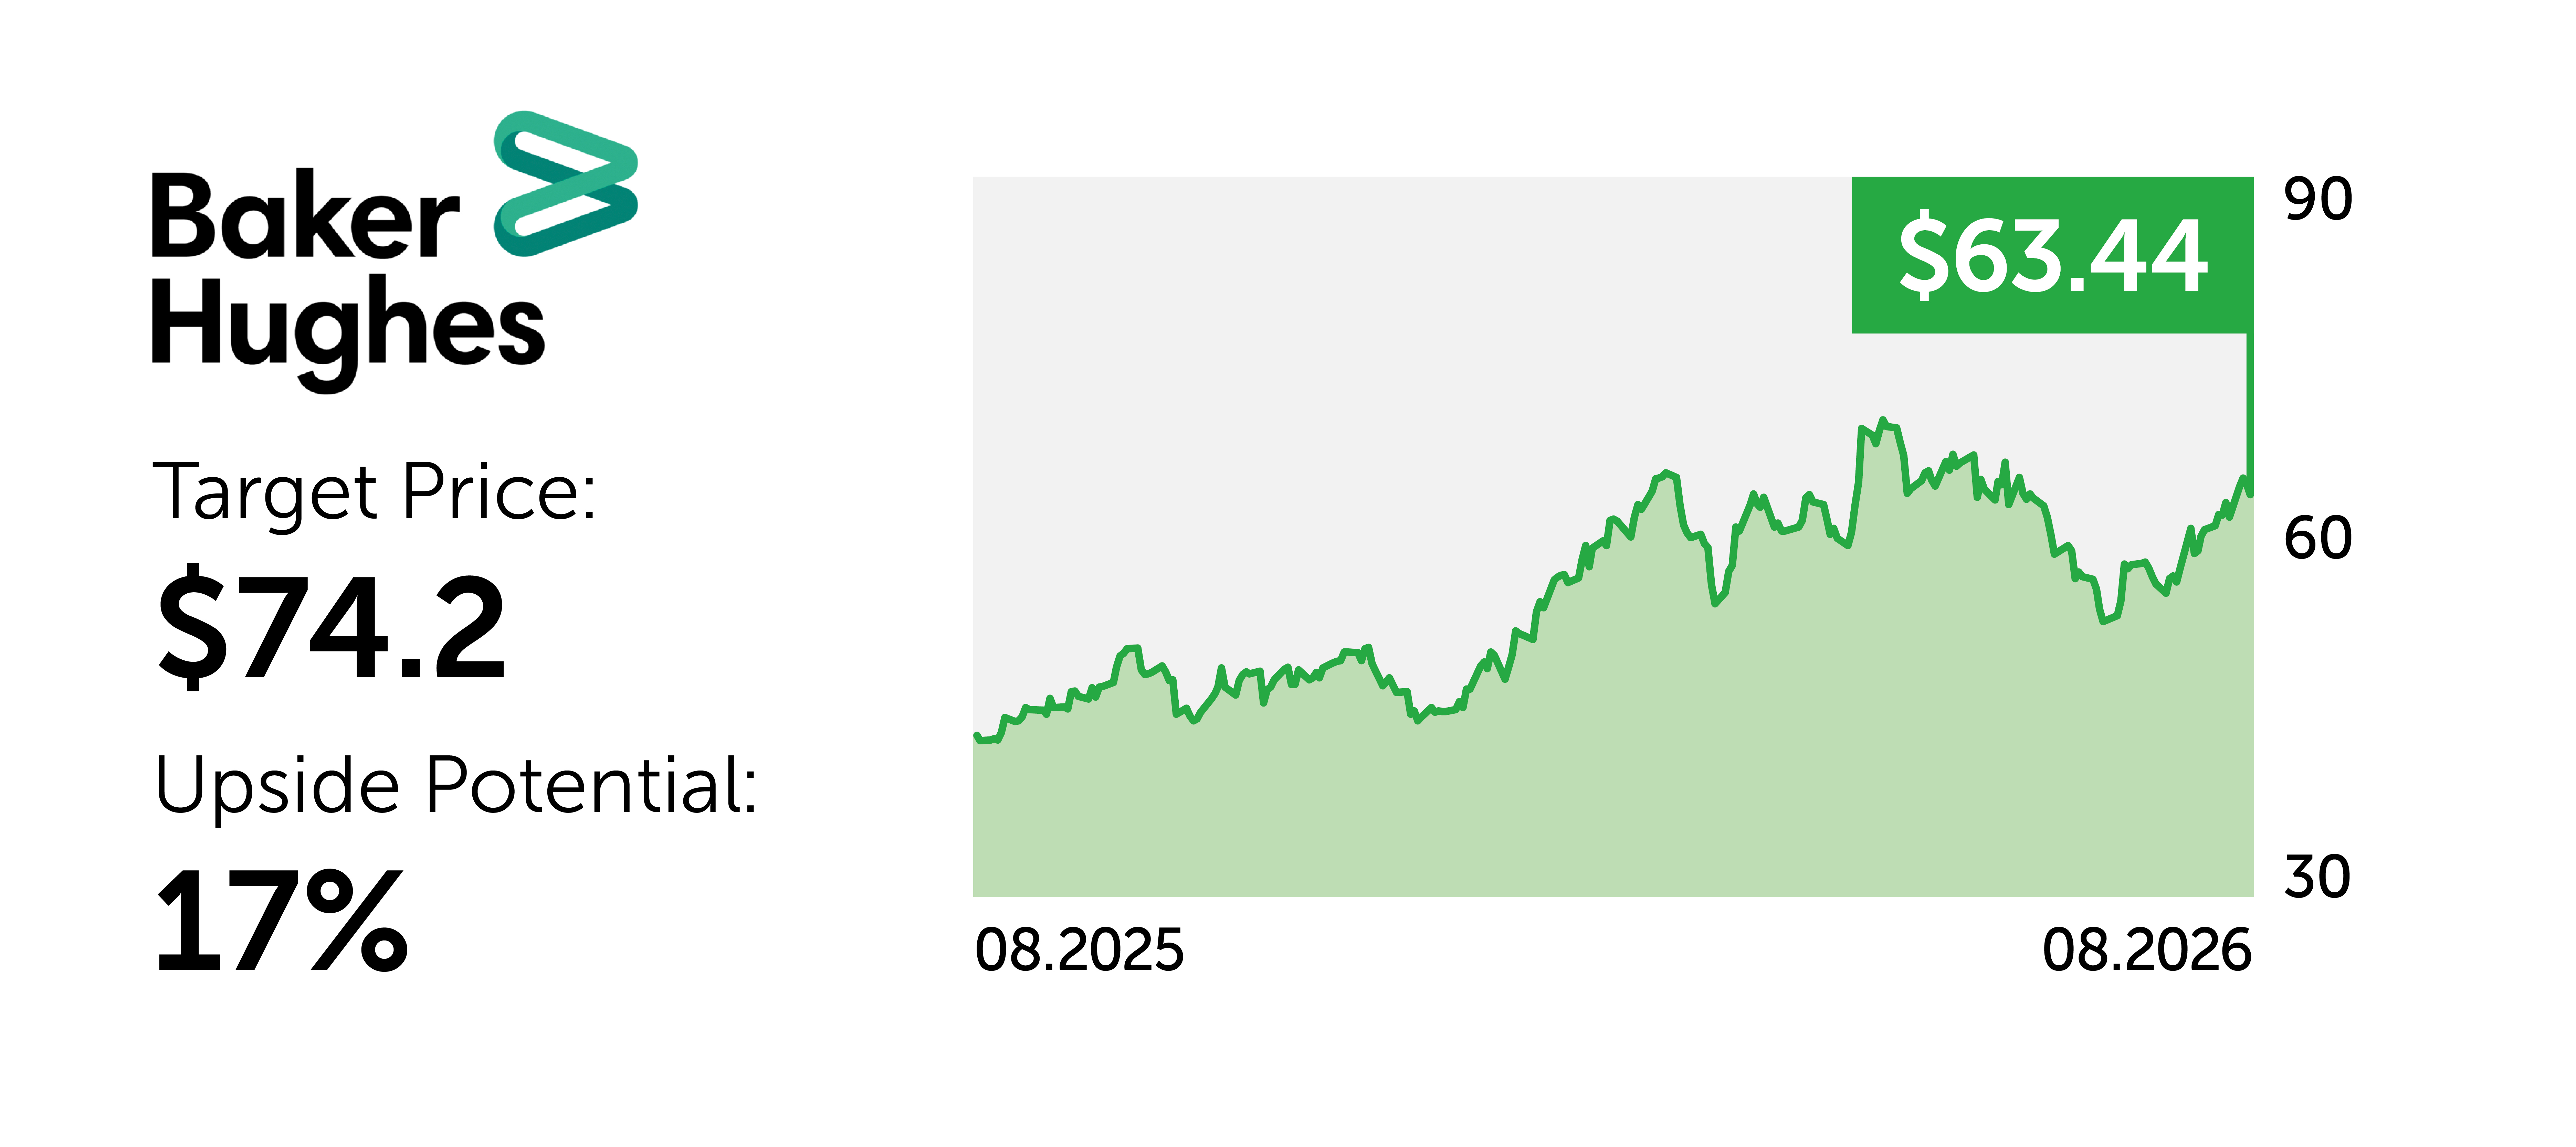
Baker Hughes (BKR) is evolving as a supplier of equipment and technologies for LNG, gas infrastructure, power generation, and data centres. In Q1, orders in the technology segment rose 54 % YoY to $4.9 billion; revenue increased by 14 %, and operating income before depreciation grew by 35 %. A new growth driver will be the acquisition of Chart Industries. This will significantly expand Baker Hughes’ capabilities in LNG equipment, industrial gases, and off‑grid power solutions. Support for the stock will come from the increase in the number of active rigs in the US to the highest level since spring 2025.
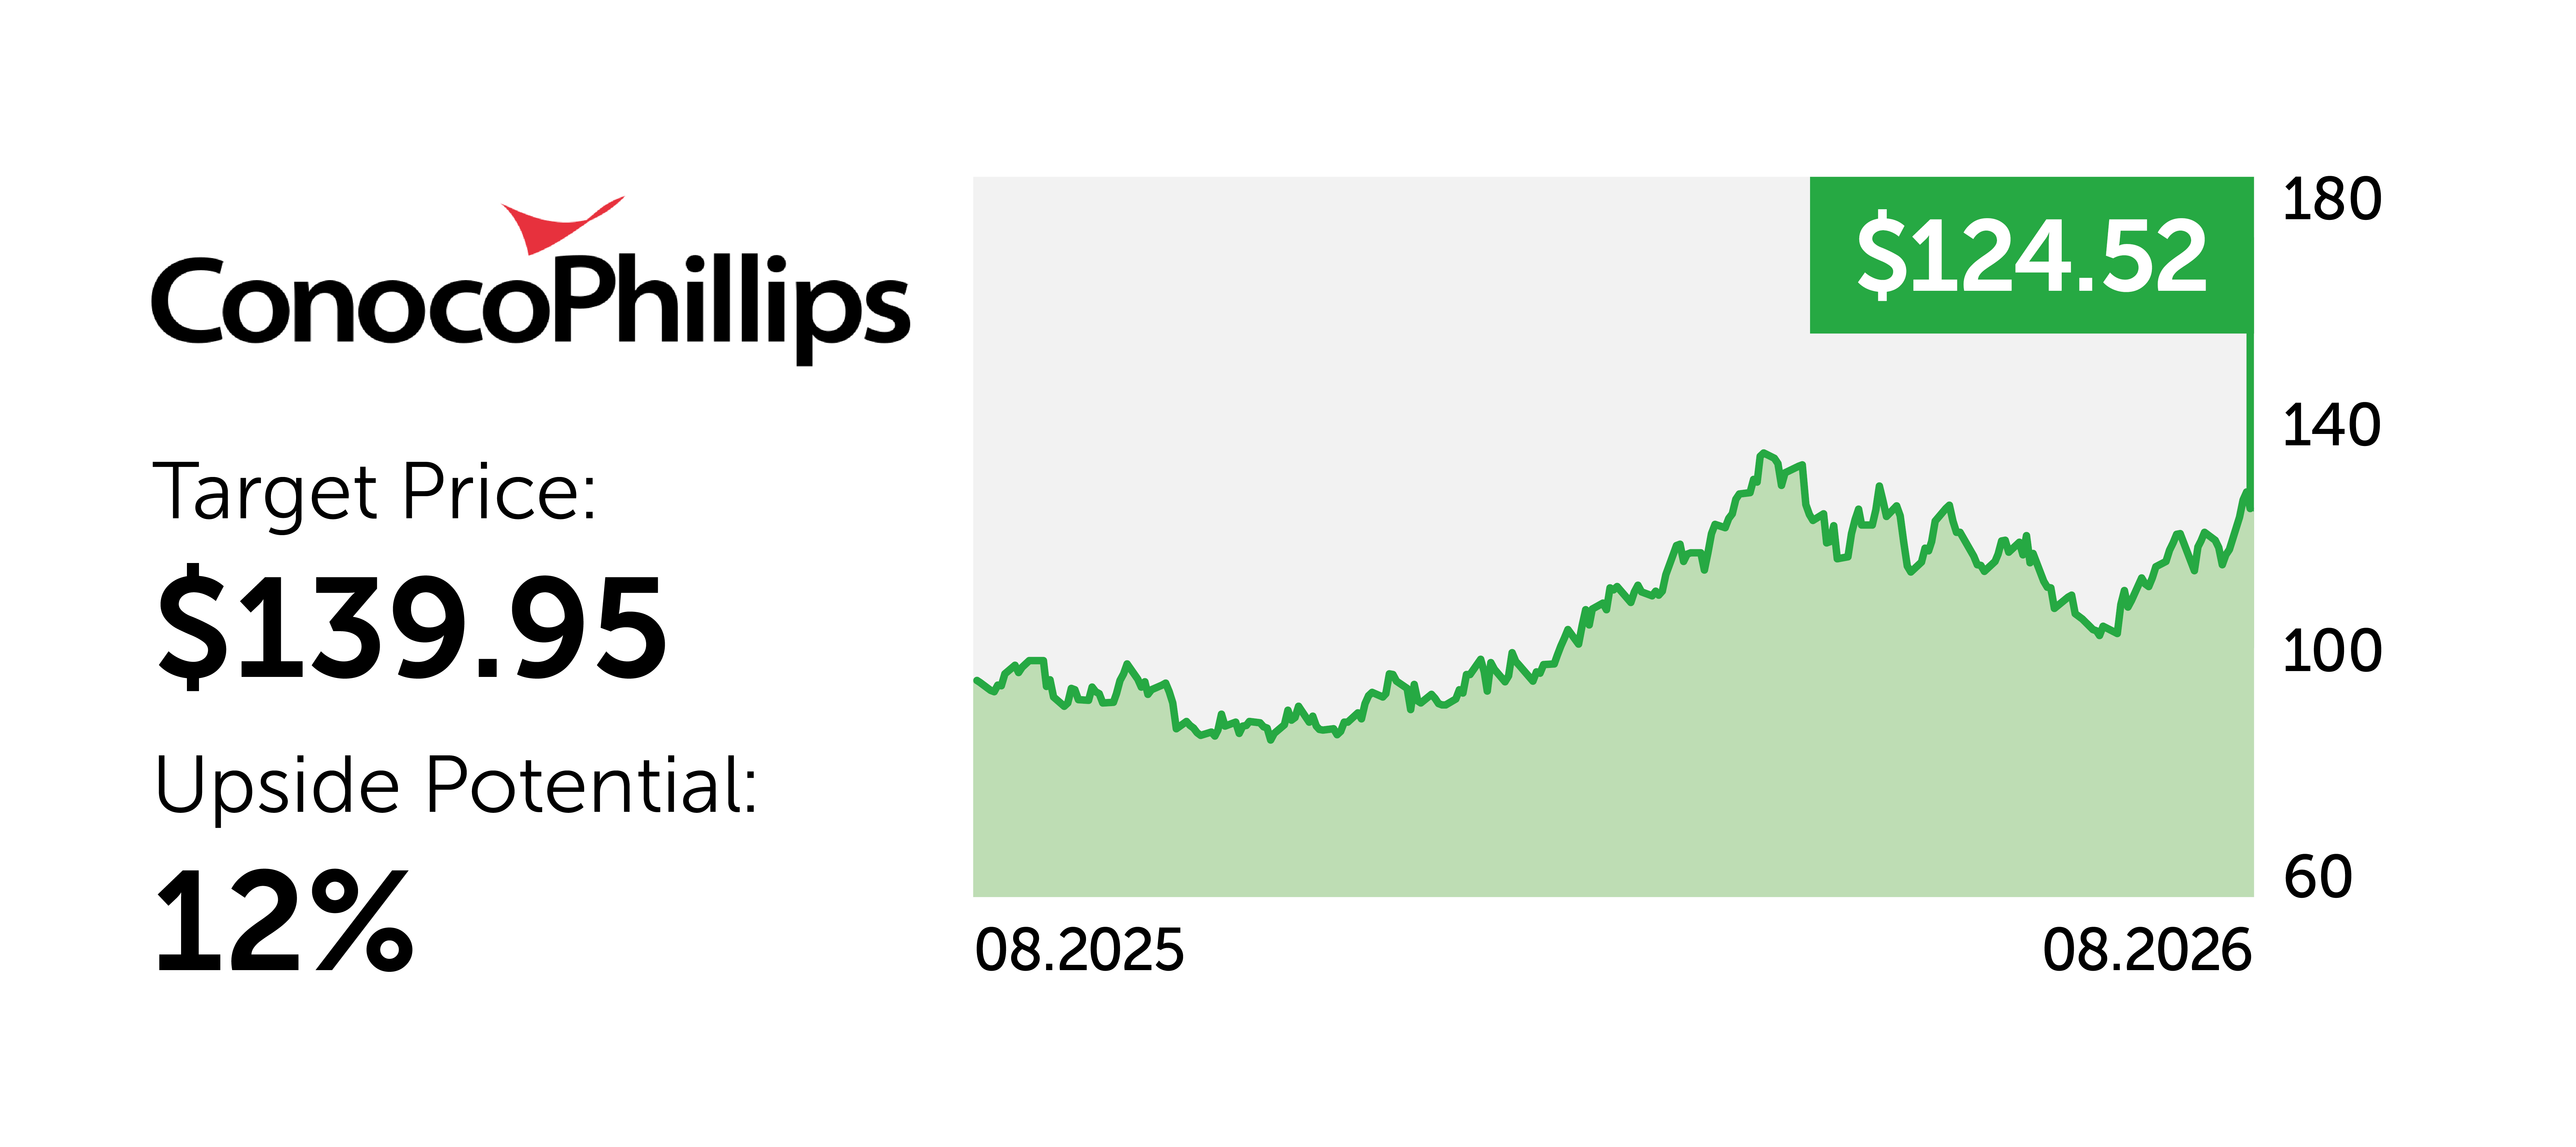
ConocoPhillips (COP) generated $5.4 billion in operating cash flow in Q1, returned $2 billion to shareholders, and confirmed its plan to allocate 45 % of annual cash flow to distributions. Production reached 2.31 million barrels of oil equivalent per day. Growth drivers include cost reductions following the integration of Marathon Oil, the development of LNG projects, and an agreement to acquire a 42 % stake in a project to rehabilitate the large Kirkuk fields in Iraq - with resource bases exceeding 3 billion barrels of oil equivalent. The main risk remains the direct dependence of financial results on oil and gas prices.
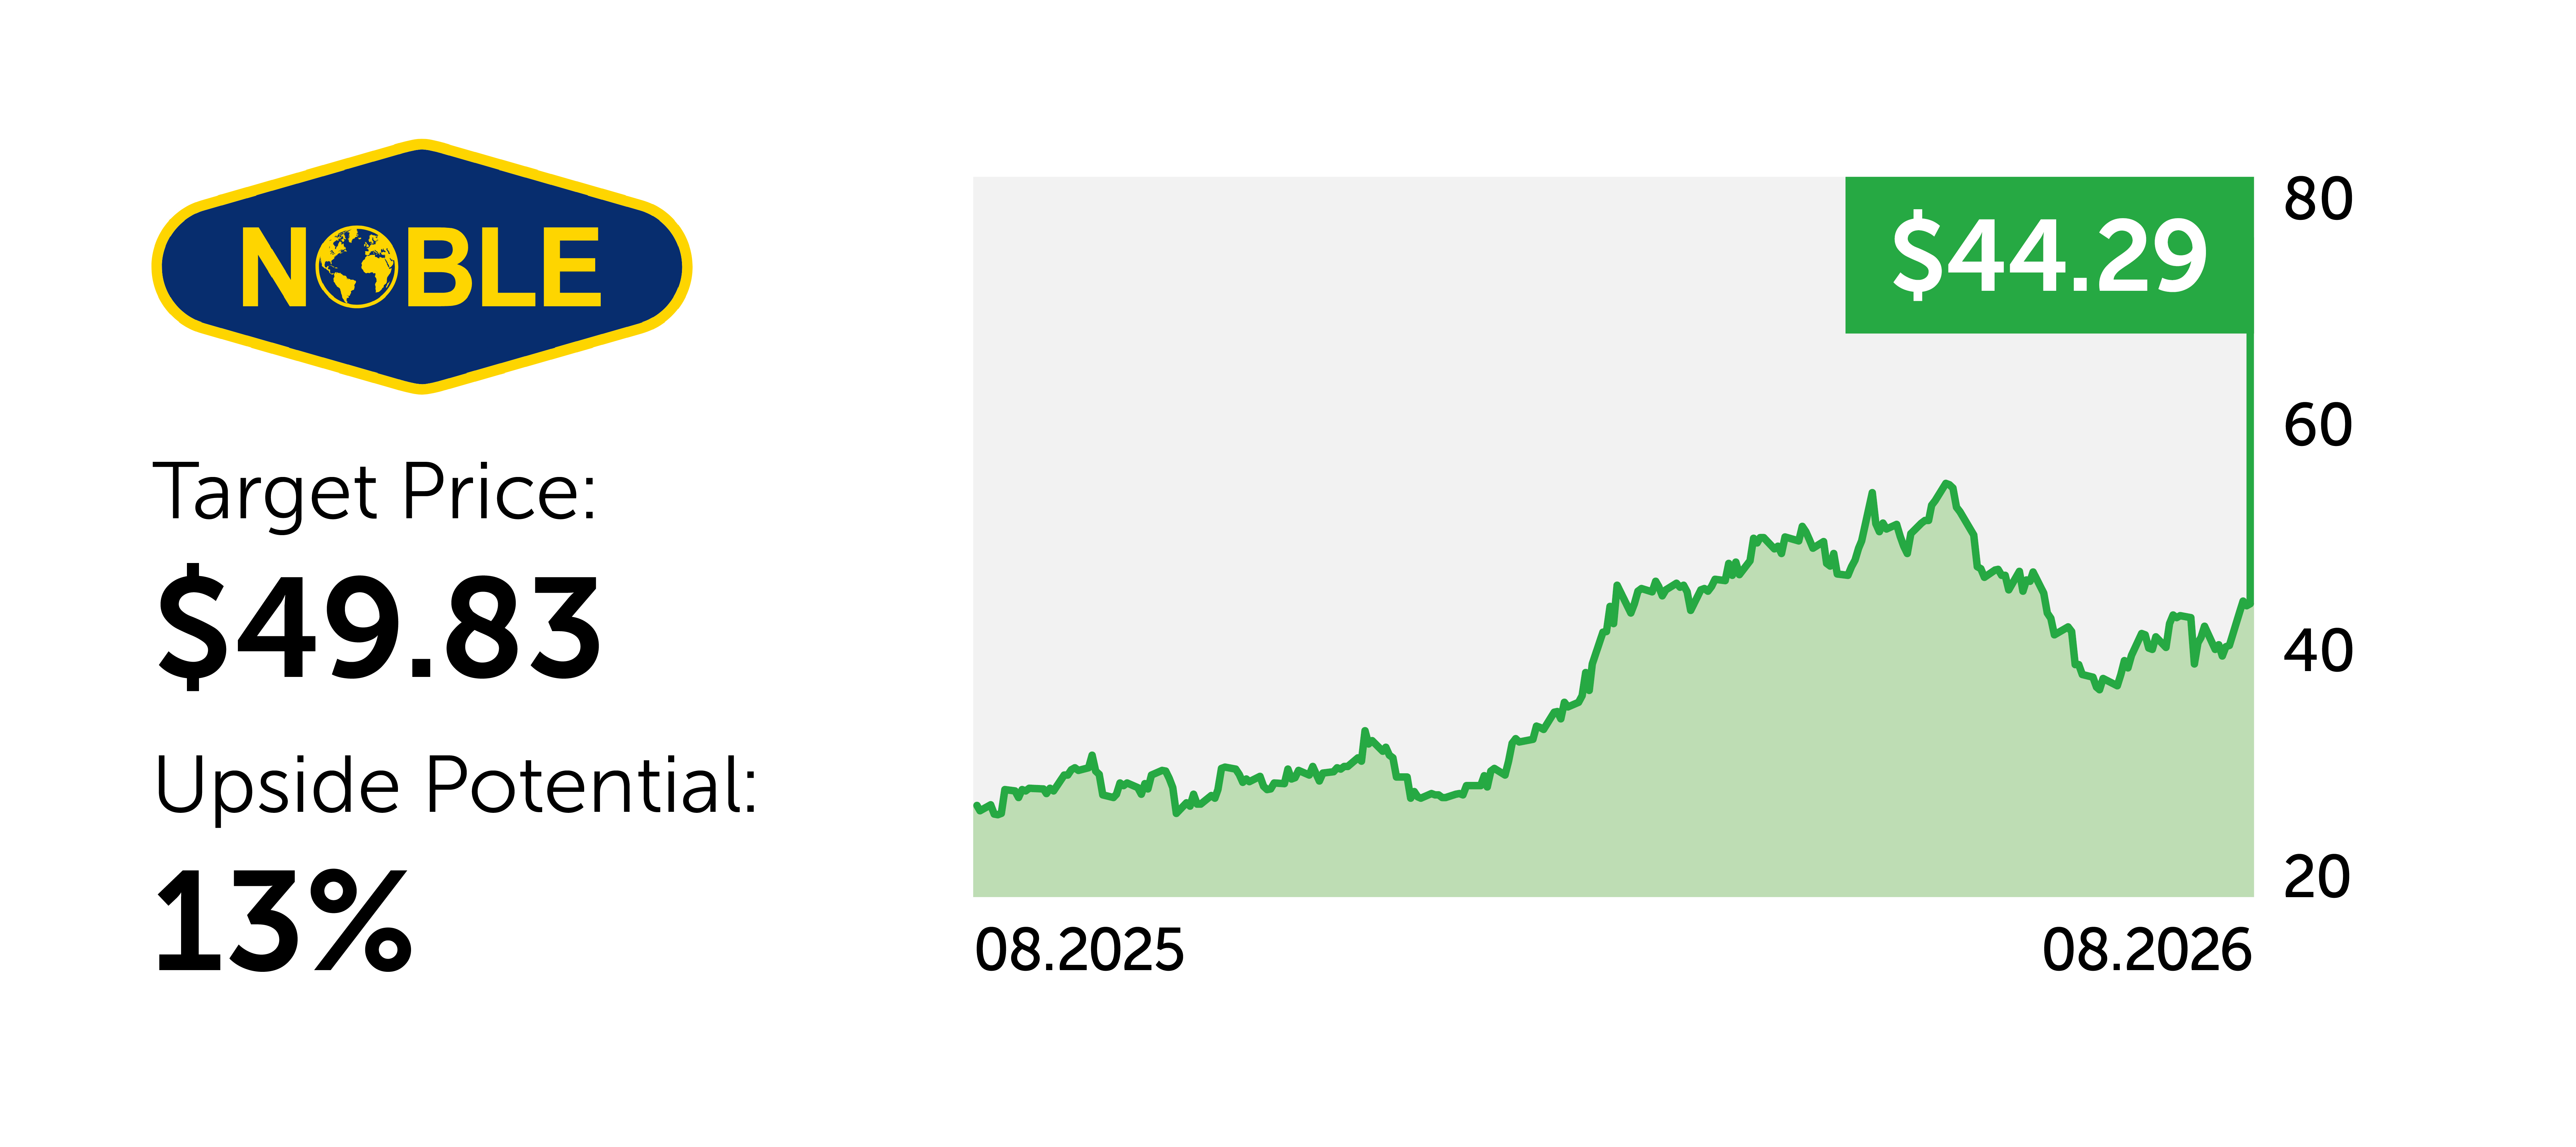
Noble (NE) increased revenue from drilling services to $ 743 million in Q1. The company’s adjusted EBITDA reached $ 277 million, with free cash flow of $ 169 million. Fleet utilization rose from 64 % to 68 %. The contract portfolio expanded to $ 7.5 billion, and day rates for modern floating rigs increased to the $400,000–450,000 per day range. This year, the company began implementing major contracts and recommissioning the Noble Deliverer rig, while maintaining a stable quarterly dividend - a catalyst for share price growth. Key risks relate to oil prices and customers revising project timelines.
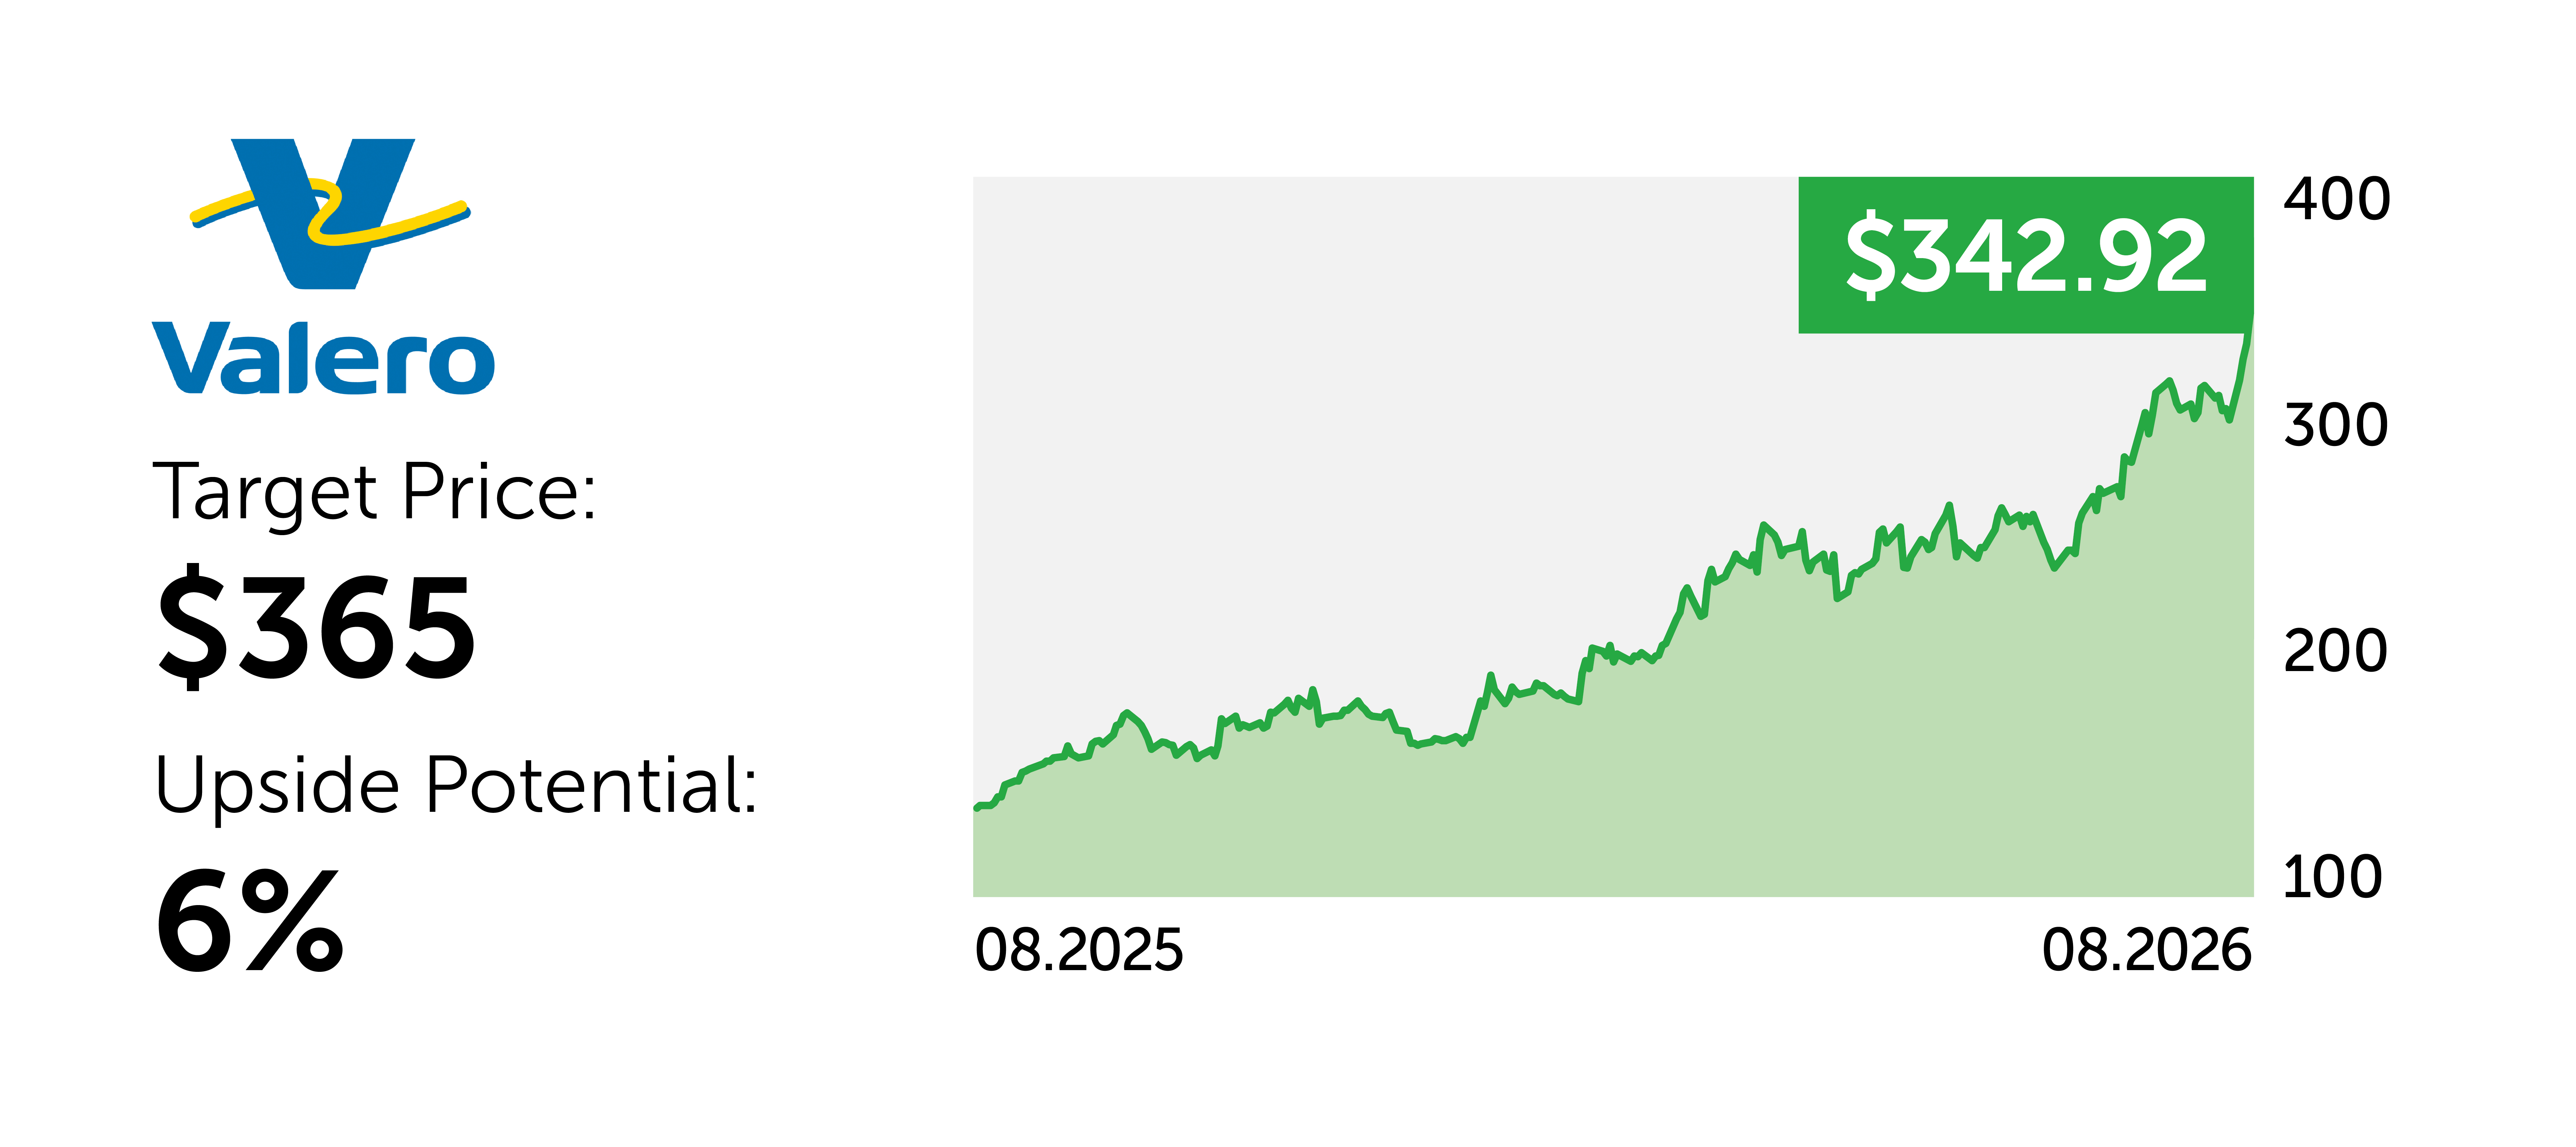
Valero Energy (VLO) reported $ 1.3 billion in net income in January–March, following a loss a year earlier. Operating profit in the refining segment reached $1.8 billion, with throughput averaging around 2.9 million barrels per day. Renewable diesel and ethanol segments began contributing to revenues. Growth drivers include record‑high refining margins amid supply disruptions from the Middle East. The business is supported by the closure of inefficient facilities, limited production expansion, high dividends, and a large buyback program. A risk factor is the rapid normalization of margins once geopolitical tensions ease.
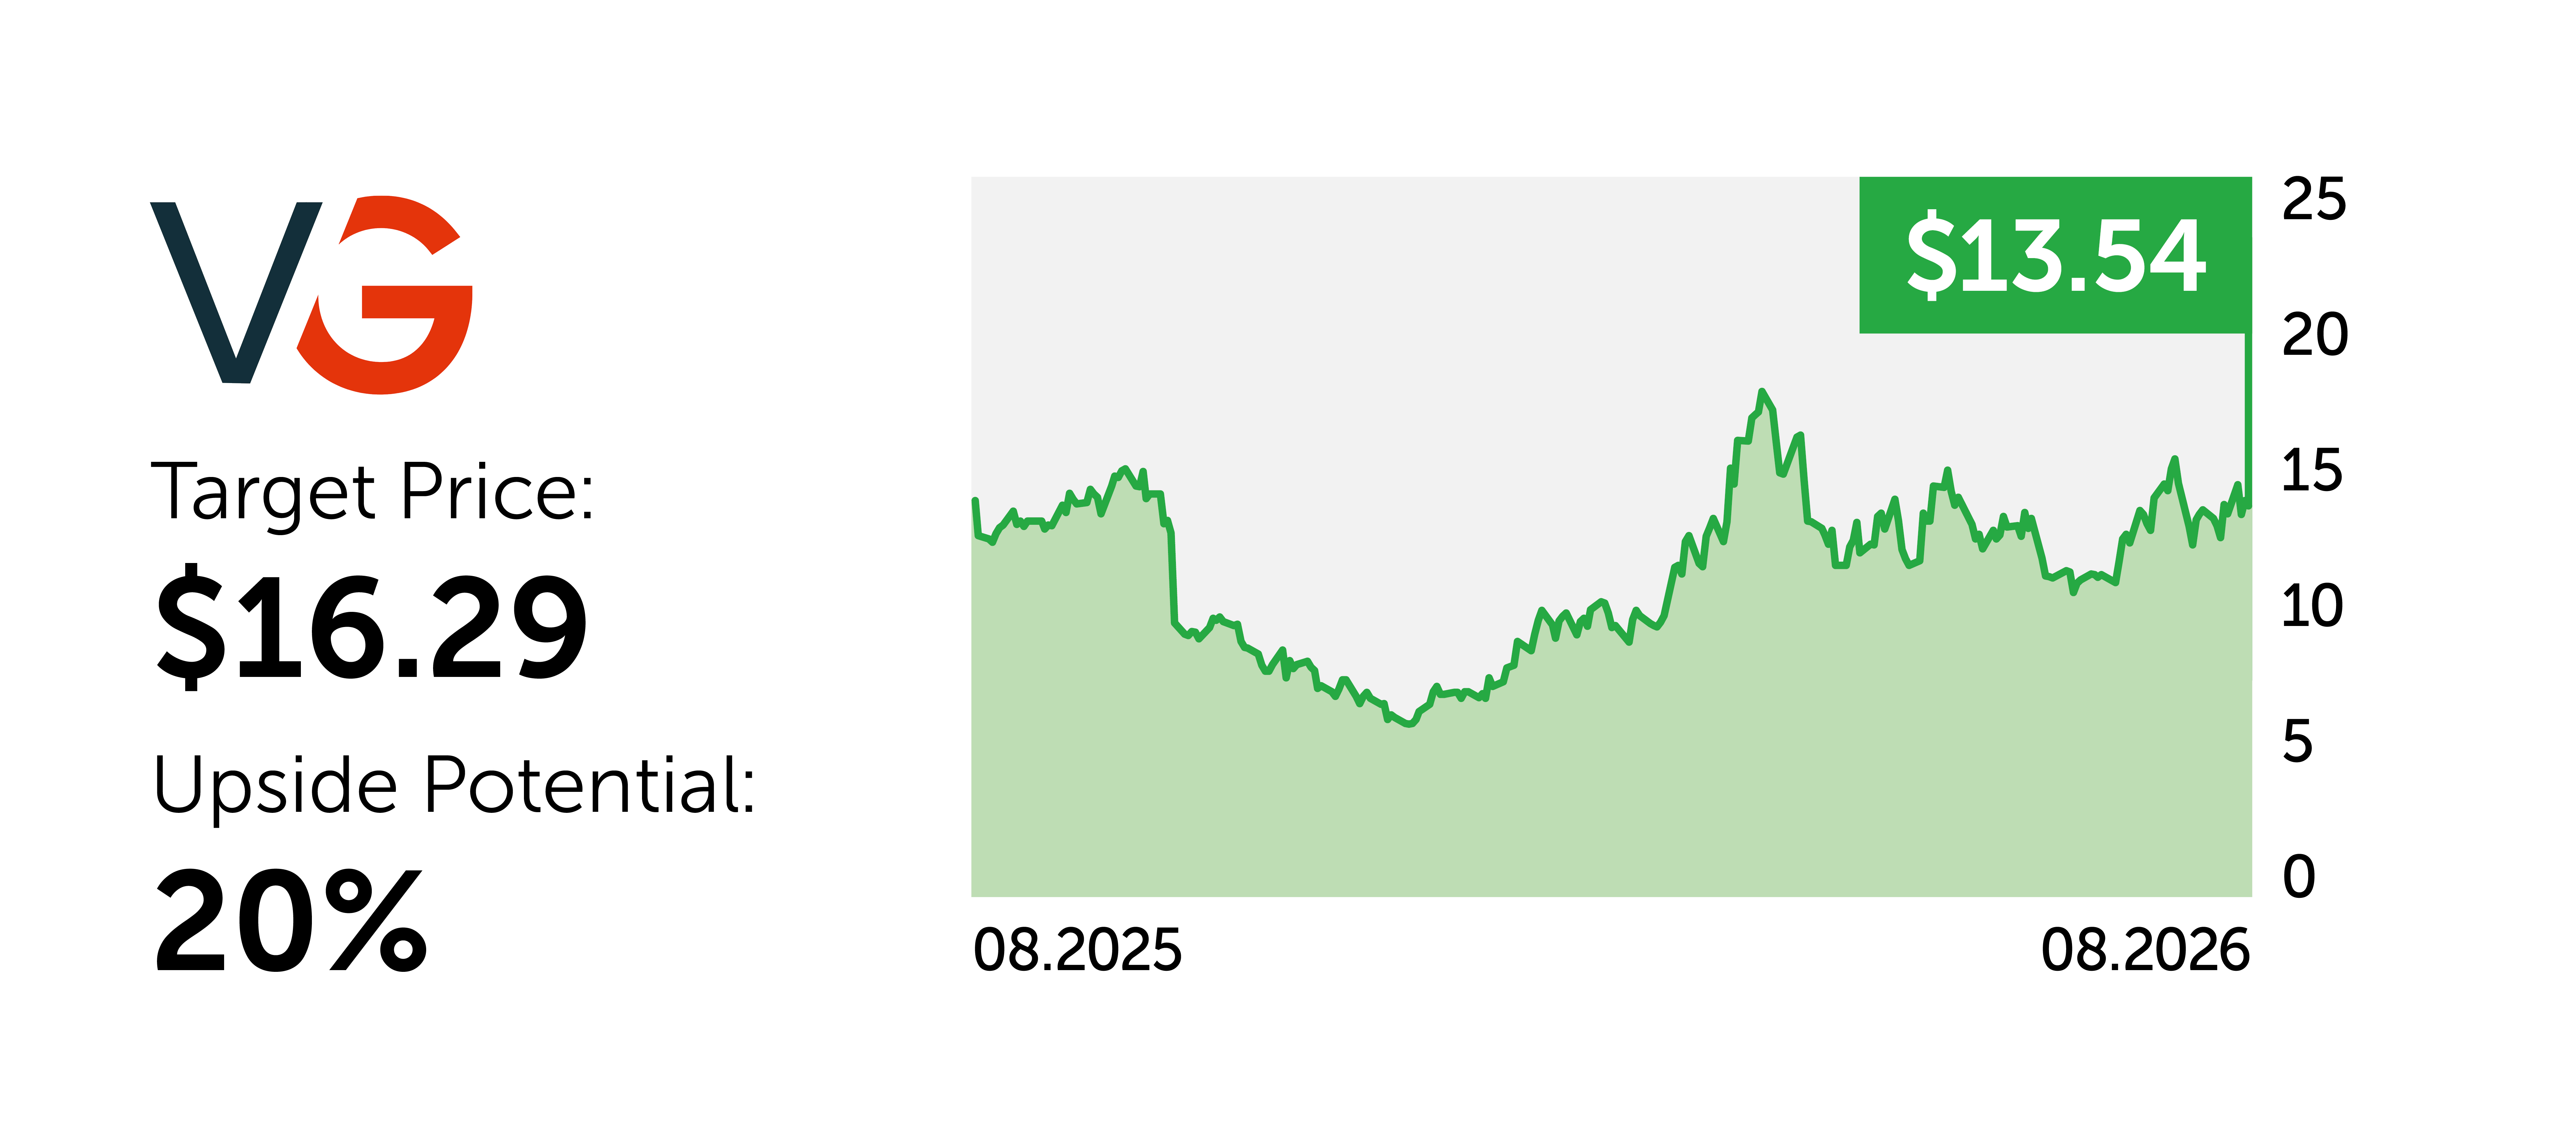
Venture Global (VG) increased revenue by 59 % to $ 4.6 billion in Q1, with net income rising by 23 %. LNG exports more than doubled thanks to the Plaquemines project. The forecast for adjusted EBITDA for 2026 has been raised to $ 8.2–8.5 billion. Share price growth will be driven by the expansion of Plaquemines capacity in late 2026 and 2027, as well as the start of LNG production at the CP2 facility. A significant share of available volumes allows the company to benefit from the gap between low gas prices in the US and higher prices in Europe and Asia. Risks include high leverage, large capital expenditures, and arbitration disputes.
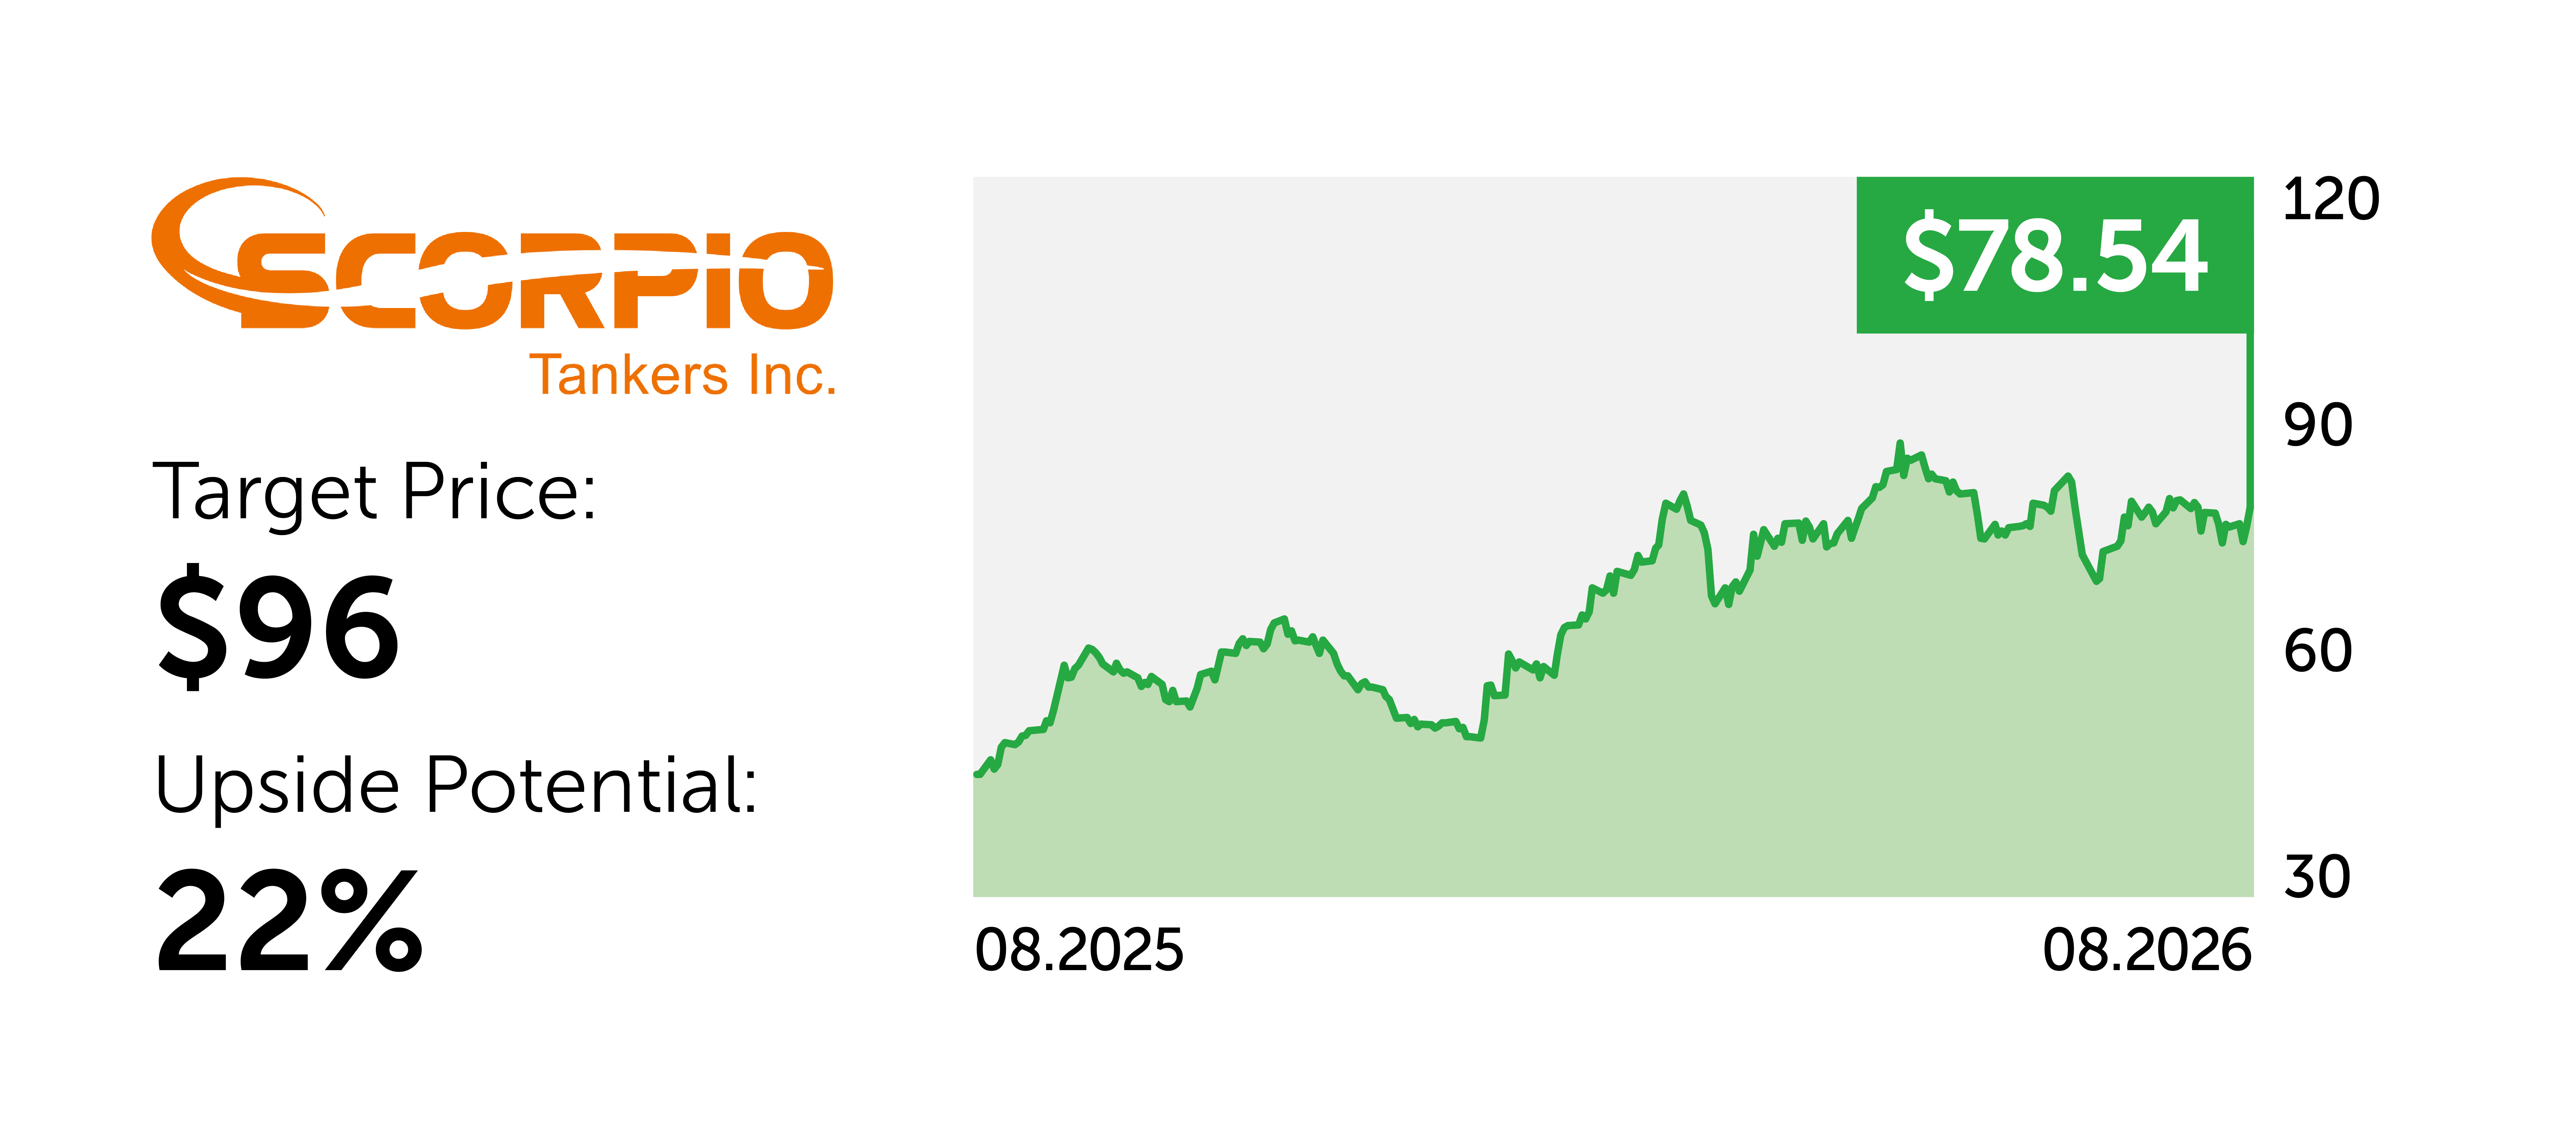
Scorpio Tankers (STNG) reported a nearly 60 % increase in average daily revenue per vessel in Q1, with fleet operating revenue of $303 million and net income of $216 million. Debt decreased from $979 million to $616 million. Rates locked in for part of Q2 were around $96,000 per day for large tankers and $66,000 for medium‑sized vessels - well above early‑year levels. The sale of part of the older fleet, ordering of modern vessels, lower interest expenses, and an expanded buyback program strengthen the potential for capital returns to shareholders. Future results will depend on the normalization of shipping routes and freight rates.
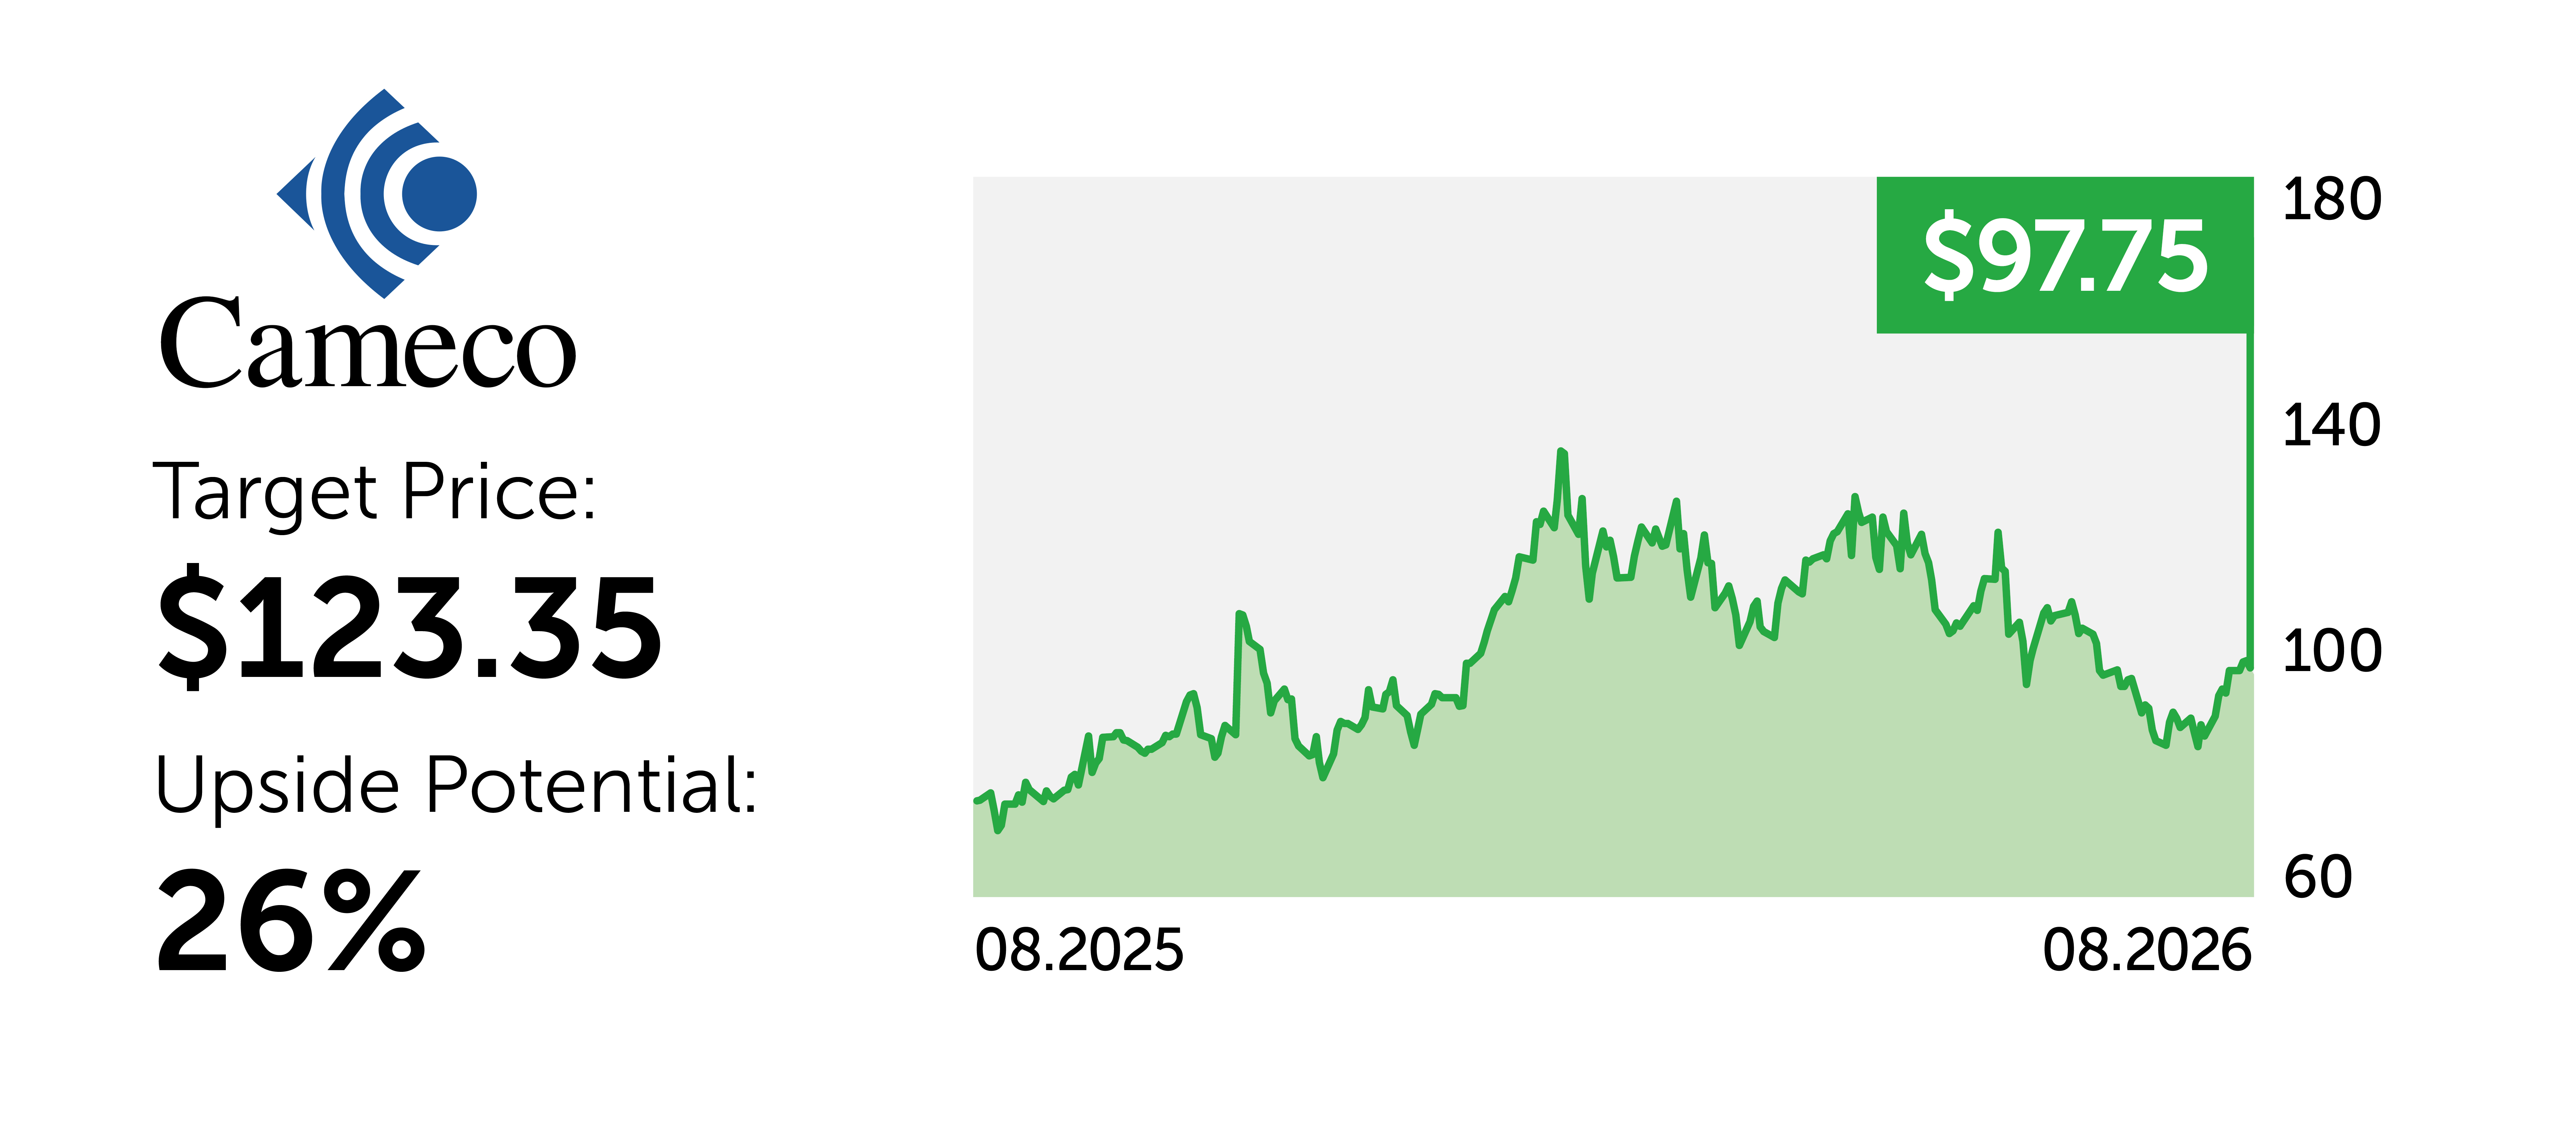
Cameco (CCJ) combines uranium mining and nuclear fuel production. In Q1, its adjusted net income was approximately $144 million, and EBITDA exceeded $360 million. Uranium segment profits grew due to higher sales volumes and prices under long‑term contracts. Structural growth drivers remain the construction of new reactors, the extension of nuclear plant lifespans, rising power demand from data centres, and Western countries’ efforts to reduce dependence on Russia. The disruption at the Cigar Lake uranium mine was quickly resolved. The stable outlook for 2026 confirms the resilience of the company’s operating model.