
Freedom Broker analysts reaffirmed their “Buy” rating on Betterware de México, S.A.P.I. de C.V. (BWMX) and maintained a target price of $31 per share. At the current price of $16.7, the upside potential is about 86%. According to the experts, the first results after the acquisition of the Tupperware business confirm the investment appeal of the deal; however, the key driver of further growth in the company’s value remains the recovery of profitability in the core business.
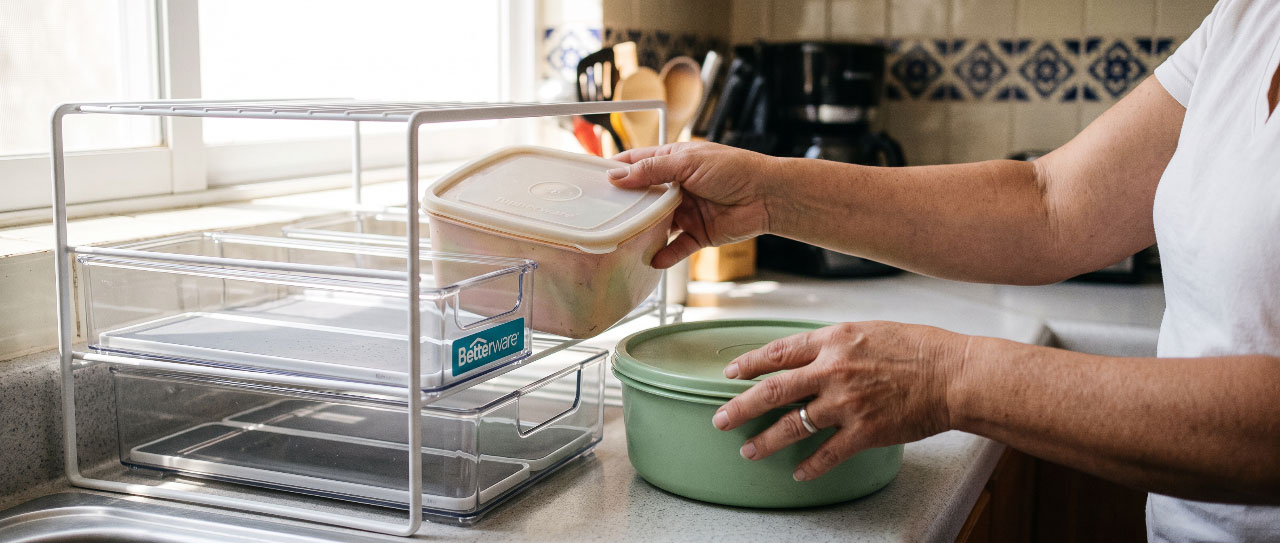
Betterware de México is a Mexican direct sales company focused on home products that owns the Betterware and Jafra brands and, since June 2026, Tupperware’s Latin American business.
Tupperware integration is already having an impact
Tupperware is a well-known American brand that manufactures plastic kitchenware (containers) and various home goods. In 2024, the company filed for bankruptcy in the U.S. amid falling demand for its products.
In June 2026, Betterware de México completed the acquisition of Tupperware’s business in Latin America for $250 mln and received an exclusive perpetual license to use the brand in the region.
The inclusion of Tupperware’s results in reporting happened earlier than expected, the analysts note. The acquired business provided the company with $26 mln in additional revenue and $7.1 mln in EBITDA already in June, and its EBITDA margin was 27.4%, significantly above the group’s figure. Betterware is consistently transforming from a single-brand company into a multi-brand direct sales platform, the experts emphasize.
Revenue and profit rose by nearly 1/5
In the second quarter of fiscal year 2026, Betterware’s consolidated revenue increased by 16.8% year over year to $239.6 mln. EBITDA rose by 15% to $44.9 mln, with a margin of 18.8%.
Excluding the acquired Tupperware business, organic revenue grew by 4.1%; however, organic EBITDA declined by 3.2% as additional business development expenses temporarily pressured margins.
Net profit increased by 20.6% to $22.7 mln, and earnings per share rose by 14.2% to about $0.58.
Free cash flow reached $33.3 mln, which corresponds to 74.1% of EBITDA, and for the first half of the year increased by 73.3% to $53.5 mln. The company also shortened the working capital cycle from 70 to 53 days and repaid about $29.2 mln of debt that existed prior to the Tupperware purchase.
The company’s outlook remains positive
Quarterly results confirmed the soundness of the Tupperware acquisition in June 2026; however, the company’s long-term investment appeal still depends on restoring organic profitability at two major direct sales businesses—Betterware (home goods) and Jafra (beauty and personal care), Freedom Broker analysts note.
Betterware’s management forecasts full-year fiscal 2026 revenue growth of 18–22% and expects to maintain an EBITDA margin of at least 19%. However, management’s main task now is to restore sustainable growth of its own Betterware and Jafra brands and to realize synergies across all three business lines.
Freedom Broker notes that this target looks achievable thanks to the full six-month contribution from Tupperware, lower one-off deal-related expenses, and a gradual recovery in Jafra’s profitability.
The experts also consider the leverage ratio more comfortable than reflected in the reporting. On a pro forma basis, the net debt to EBITDA ratio is 1.62x, which is below last year’s level and indicates that the company’s solid financial position is being maintained.
What’s happening with Betterware de México
As early as the results of the first quarter of fiscal 2026, analysts maintained a “Buy” rating and pointed to improved operating efficiency, free cash flow growth, and lower leverage. The new reporting confirms that the integration of Tupperware has already begun to deliver a financial effect, while restoring margins in the core business remains the key factor for further revaluation of the shares.
This is not an individual investment recommendation.