
Freedom initiates coverage of Expand Energy: upside potential for the stock exceeded 23%
Stock Market News
4 September 2026, 18:15
Freedom Broker analysts have initiated coverage of Expand Energy Corporation (EXE), the largest independent natural gas producer in the U.S., with a “Buy” rating and a $122 target price. With the current price at $99.05, the upside potential is 23.17%. Experts expect that rising liquefied natural gas exports and electricity consumption will support gas prices and the company’s financial results.
What kind of company is Expand Energy
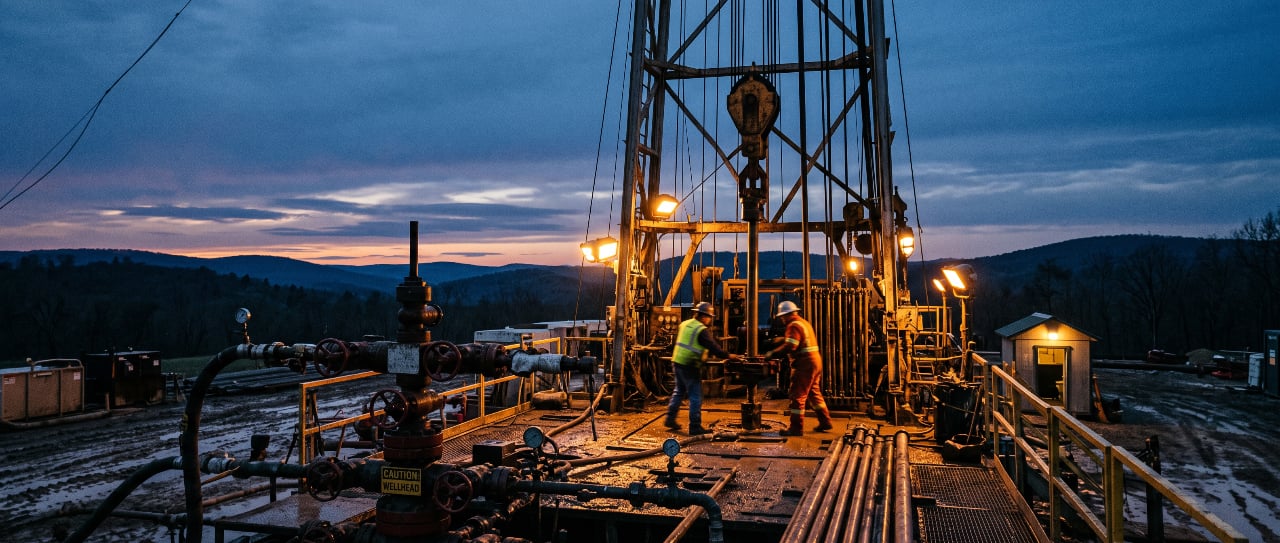
Expand Energy is engaged in the exploration, development and production of natural gas, oil and gas condensate. Its core assets are located in three major U.S. gas-producing regions: Haynesville, and the northeastern and southwestern parts of the Appalachian Basin.
The company became the largest independent natural gas producer in the U.S. after the merger of Chesapeake Energy and Southwestern Energy. The two American natural gas producers combined in October 2024. The merger combined Chesapeake’s assets in the Marcellus and Haynesville basins with Southwestern’s fields in the Appalachian region.
As of the end of 2025, Expand Energy held interests in about 6.6k wells, of which 4.6k were operated by the company. Proved reserves reached 25,880 Bcf in gas equivalent, with natural gas accounting for 87.2%. Expand Energy’s market capitalization reached $23.29bn, and enterprise value including debt was $25.31bn.
The gas market is creating conditions for growth
The main argument in favor of the stock, according to Freedom Broker analysts, is an improvement in the medium-term outlook for the U.S. gas market. Growth in LNG exports, resilient domestic demand and rising electricity consumption should gradually reduce the supply overhang.
The U.S. Department of Energy expects LNG exports to increase by 15.0% in 2026 and by another 7.2% in 2027. Additional demand will be supported by new export capacity, including the expansion of the Corpus Christi LNG terminal in Texas and the commissioning of the new Golden Pass LNG terminal.
According to the analysts, these projects will absorb excess gas volumes in the domestic market and support prices. Expand Energy is especially sensitive to this dynamic: in the first half of 2026, natural gas accounted for 89.0% of hydrocarbon sales revenue, gas condensate for 7.1%, and oil for 3.9%, the experts note.
Diversification reduces operating risks
According to the analysts, Expand Energy’s assets combine low-cost production in Appalachia with Haynesville’s proximity to export terminals on the U.S. Gulf Coast. Northeast Appalachia provides stable cash flow thanks to low production costs. The southwestern part of the region gives the company additional exposure to gas condensate, while Haynesville allows it to directly participate in demand growth from LNG projects.
In Freedom Broker’s view, operating in three basins at once makes Expand Energy’s production base more resilient and allows it to reallocate investment depending on regional pricing and market conditions.
Profit reached $522m
In Q2 2026, Expand Energy posted net income of $522m, or $2.19 per diluted share. Adjusted net income was $317m, or $1.33 per share. Adjusted EBITDAX (earnings before interest, taxes, depreciation, amortization and exploration expenses) reached $1.183bn. Operating cash flow totaled $1.096bn.
Average daily production reached about 7.48 Bcfe, with natural gas accounting for 92% of volumes. The company maintained its full-year production guidance at 7.4–7.6 Bcfe/d. In 2026, Expand Energy plans to operate 11–12 rigs and allocate $2.75–2.95bn for capital investments.
The company is reducing debt and repurchasing shares
At the end of Q2, Expand Energy’s total debt stood at $3.7bn—about $1.3bn less than at the end of 2025. Net debt reached $3.1bn, and the net debt-to-adjusted EBITDA ratio was around 0.5x—the lowest among comparable companies.
In Q2, Expand Energy allocated about $530m to share buybacks. Since the beginning of the year, repurchases totaled about $850m, or 4% of shares outstanding. The company also approved an additional new buyback program of about $1bn.
Expand Energy also pays a base quarterly dividend of $0.575 per share. Analysts believe strong cash flow and low leverage allow the company to both fund production and return capital to shareholders.
The acquisition of Twin Eagle will expand the business
In July, Expand Energy agreed to acquire the natural gas marketing platform Twin Eagle Holdings from investment firm Five Point Infrastructure for about $1.25bn. The deal is still subject to customary closing conditions and regulatory approvals.
Twin Eagle has capabilities in gas trading, transportation and storage across North America. After the acquisition closes, Expand Energy will be able to control a broader portion of the value chain—from gas production to delivery to end markets.
Why analysts recommend buying EXE
Freedom Broker believes the current valuation does not fully reflect the scale of Expand Energy’s business, its diversified asset portfolio and the outlook for growing gas demand. In 2026, analysts forecast revenue of $13.31m and adjusted EPS of $7.54. In 2027, revenue of $12.81m and EPS of $5.15 are expected, and in 2028—$13.61m and $7.58, respectively.
The $122 target price is based on a five-year discounted cash flow model. Key drivers could include a recovery in gas prices, faster growth in LNG exports and continued share buybacks. Key risks include a decline in commodity prices, pipeline capacity constraints and potential complications in the Twin Eagle acquisition.
This is not an individual investment recommendation.