
Freedom Broker sees 35.58% upside potential for Intuitive Surgical
Stock Market News
29 сентября 2026, 10:00
Freedom Broker analysts maintained their “Buy” rating on shares of Intuitive Surgical (ISRG) with a target price of $540. At the current price of $405,1, the upside potential is about 33.3%. The key driver of the investment thesis, experts believe, is the surgical-robot maker’s ability to grow profit faster than revenue thanks to a high share of recurring revenue and operating leverage.
Read more in the new investment review by Freedom Broker experts.
What Intuitive Surgical does
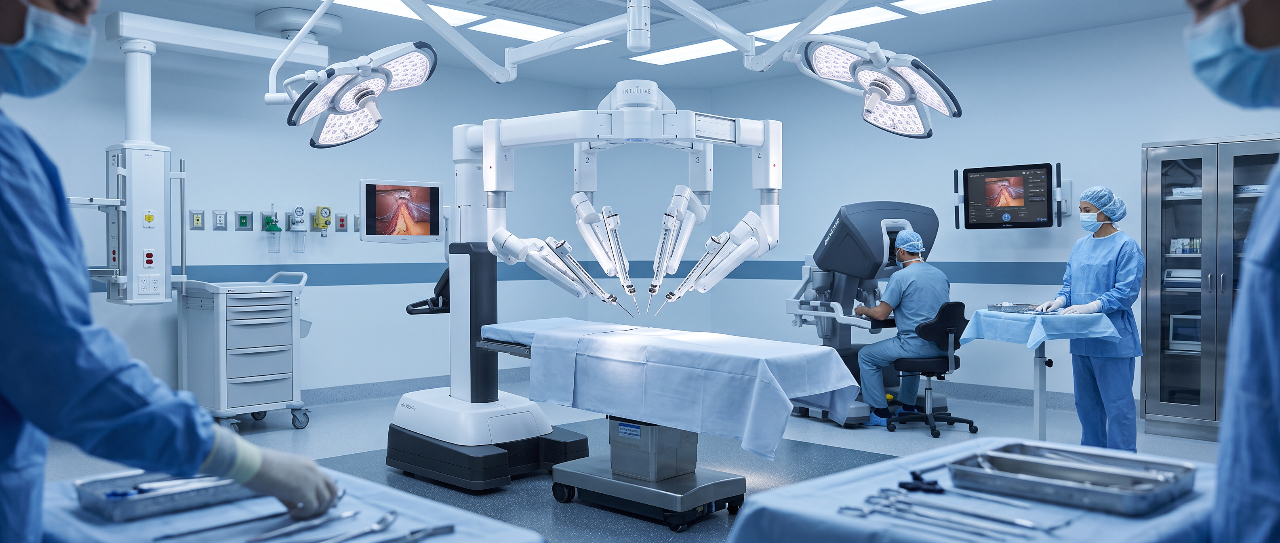
Intuitive Surgical is a global leader in robotic surgery. The company develops the da Vinci platforms for minimally invasive procedures and the Ion system for diagnosing lung diseases.
Intuitive Surgical’s business model combines equipment sales and leasing with service and supplies of consumables. Recurring revenue accounted for 85% of the company’s revenue in Q2 2026, improving the predictability of cash flows.
Rising profitability becomes the main argument
According to Freedom Broker, the investment appeal of Intuitive Surgical increasingly depends not only on the number of procedures, but also on margin expansion. The company shows pronounced operating leverage: its profit grows faster than revenue, as costs increase at a more moderate pace.
Analysts lowered the stock’s target price from $610 to $540 but kept the “Buy” rating. At the current price of $405,1, the expected rise to the target level is about 33.3%. To value the company, experts used a five-year discounted cash flow model, as well as NTM P/E multiples of 50x and EV/Sales of 15x.
Profit grew faster than revenue
In Q2 2026 revenue of Intuitive Surgical rose 19% year over year to $2,89 bn. GAAP net income increased 24% to $818 mn, and diluted EPS reached $2,29 versus $1,81 a year earlier. Adjusted net income totaled $1 bn, or $2,80 per share.
GAAP operating income rose from $743 mn to $972 mn. Gross margin excluding certain items reached 70%, up 210 basis points. Non-GAAP EBIT margin came in at 42.1% and exceeded the market consensus forecast of 38.5%.
Cash, cash equivalents, and investments on the balance sheet reached $8,63 bn, increasing by $650 mn over the quarter. The company also repurchased 0,9 mn of its own shares for $380 mn.
Da Vinci and Ion expand the installed base
The number of procedures using Intuitive Surgical platforms for minimally invasive surgery grew by about 16% year over year. The number of procedures on robot-assisted surgical systems da Vinci increased 15%, while procedures on the biopsy platform Ion jumped 36%.
Over the quarter, the company installed 468 da Vinci systems, including 246 next-generation da Vinci 5 units. The total da Vinci installed base grew 12% to 11 710 systems, and the number of Ion platforms rose 21% to 1 096 units.
Outside the U.S., the number of da Vinci procedures increased 20%. In the U.S. market, growth slowed to 12% from 14% in the previous quarter. Among the restraining factors, analysts cite a decline in bariatric surgeries amid the spread of GLP-1 drugs, weaker activity in the elective surgery segment, and worsening access to healthcare.
Equipment replacement cycle will support revenue
Freedom Broker names a multi-year cycle of replacing older surgical robots with da Vinci 5 as one of the key drivers. Additional support may come from broader use of the SP and Ion platforms, improved insurance reimbursement conditions in Japan, and the rollout of da Vinci 5 into new markets.
The company also offers refurbished XiR systems and is developing the Extended Use program, which allows certain instruments to be used longer. These initiatives reduce the cost per procedure and make robotic surgery more accessible for price-sensitive healthcare providers.
Freedom Broker forecasts that Intuitive Surgical’s revenue in 2026–2028 will grow by an average of 15% per year. Operating profit could grow faster thanks to higher utilization of the installed base and more moderate expense dynamics.
The company improved its profitability outlook
Intuitive Surgical maintained its 2026 outlook for growth in the number of da Vinci procedures at 13.5–15.5%, but now expects results closer to the middle of the range. At the same time, the non-GAAP gross margin forecast was raised from 67.5–68.5% to 68–69%. The company narrowed its expected growth in operating expenses to 11–13%.
According to Freedom Broker, improving margins, growth in service revenue, and the refresh of the installed equipment base support expectations for further profit growth even as the business gradually transitions to more mature growth rates.
What risks analysts consider
The main risks remain further slowing in the number of procedures in the U.S., the proliferation of GLP-1 drugs, and intensifying competition in China. Regulatory pressure and a decline in market multiples as the company’s growth slows may also weigh on the stock.
Not an individual investment recommendation.