
Freedom Broker analysts have maintained their “Hold for up to two years” recommendation on the bonds of Indonesian energy company Medco Energi International (MEDC), MEDCIJ 8.625’30. The target holding-period yield is 7.7%, and the yield to maturity is 7.80%. Strong second-quarter results and lower leverage support the issuer’s credit profile; however, most positive factors are already reflected in the securities’ price, the experts note.
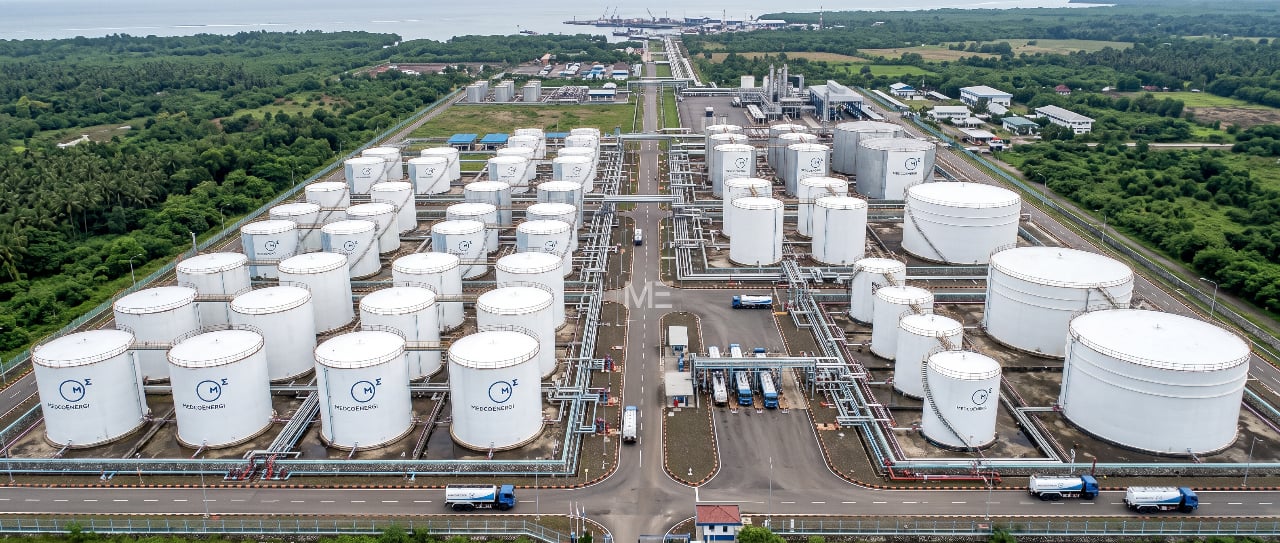
What kind of company is Medco Energi
Medco Energi is an Indonesian energy company engaged in oil and gas exploration and production, power generation, and natural resources development. A diversified asset portfolio and a high share of gas reduce the business’s dependence on fluctuations in oil prices.
About half of production is sold under long-term contracts with fixed prices. This increases cash-flow predictability, while low production costs allow the company to maintain positive free cash flow even when oil prices fall.
The $600 млн MEDCIJ 8.625’30 bonds have a fixed 8.625% coupon paid twice a year. The maturity date is May 19, 2030, and the minimum lot is $250 тыс. Analysts rate the issue’s liquidity as below average and its risk profile as balanced.
Positive factors already priced in
Freedom Broker’s main conclusion is that Medco Energi’s fundamentals remain resilient, but room for further material tightening of the credit spread is limited.
The issue’s OAS spread—i.e., the yield premium over comparable risk-free bonds adjusted for embedded options—has more than halved: from over 400 basis points in May 2025 to around 190 basis points by the end of September 2026. Since the start of 2026, the metric has declined by roughly 100 basis points.
According to analysts, the spread is currently around a fair level relative to BB−-rated emerging-market dollar bonds. Therefore, there are no grounds to expect significant further tightening.
Production growth and a high share of gas with contract-based pricing are structural in nature, while the 61% margin reflects temporarily high oil prices, Freedom Broker analysts noted.
Revenue rose 29%
In the second quarter of 2026, Medco Energi’s revenue increased 29% year over year and 11.7% versus the previous quarter, to $746 млн. For the first half of the year, the figure reached $1,415 млрд, up 24.3% year over year.
The average realized oil price rose to $87.5 per barrel from $75.1 per barrel in the first quarter. At the same time, production reached a record 171 тыс. barrels of oil equivalent per day, up 19.6% year over year and 1.2% quarter over quarter. For the first half, production totaled 170 тыс. boe per day, 19% above last year’s result and in line with the upper end of the company’s guidance. Gas accounted for about 72% of output.
EBITDA in the second quarter rose 57% year over year and 29.5% quarter over quarter, to $452 млн. The EBITDA margin reached 61% versus 50% a year earlier and 52% in the first quarter. Net profit totaled $215 млн versus $22 млн a year earlier. For the first half, it increased from $42 млн to $288 млн.
Free cash flow increased 52%
Operating cash flow in the second quarter declined 11% quarter over quarter, to $242 млн. Analysts consider this a temporary phenomenon related to an increase in receivables following stronger sales and higher tax payments amid expensive oil.
Free cash flow for the first half grew 52% year over year, to $331 млн. Restrained capex allowed the company to maintain positive cash generation despite an expanded investment program.
In the first half, Medco Energi raised $922 млн in new, mostly bank, financing and repaid $324 млн of debt. Gross debt by the end of the second quarter reached $4,3 млрд, up 14% year over year and 16% versus the previous quarter. At the same time, net debt decreased 7% quarter over quarter, to $2,85 млрд.
Liquidity covers maturities through 2030
Medco Energi’s liquidity buffer amounted to about $2,57 млрд. It includes $1,39 млрд in cash and cash equivalents and $1,18 млрд in undrawn credit lines. According to Freedom Broker, together with expected free cash flow, this is sufficient to cover maturities through 2030.
Analysts do not expect a material increase in leverage. Under their forecast, the net debt-to-EBITDA ratio will remain in the 1,9–2,1x range in 2026–2028, while gross debt will decline to $3,4 млрд by 2028.
Freedom Broker forecasts Medco Energi’s revenue in the $2,3–2,5 млрд range in 2026–2028 and EBITDA at $1,1–1,35 млрд. Free cash flow could total $496 млн in 2026, $192 млн in 2027, and $88 млн in 2028.
Production growth supports the credit profile
For the full year 2025, Medco Energi posted revenue of $2,34 млрд and EBITDA of $1,26 млрд with a 54% margin. Production increased to 156 тыс. boe per day, and in the fourth quarter reached a record 176 тыс. boe per day.
For 2026, the company reaffirmed production guidance in the 165–170 тыс. boe per day range. Among the factors supporting the bonds, Freedom Broker highlights production growth, contract pricing for a significant portion of gas deliveries, positive free cash flow, and a liquidity buffer. The key constraints remain part of earnings’ dependence on oil prices, a growing investment program, and the lack of meaningful potential for further credit-spread tightening.
This is not an individual investment recommendation.