
Freedom experts estimate EQT’s upside at 14% ahead of the heating season
Stock Market News
2 October 2026, 09:43
Freedom Broker analysts recommend buying shares of U.S. natural gas producer EQT Corporation (EQT) with a target price of $55,40 through November 30, 2026. At the current quote of $48,5, the upside potential is 14%. Increased gas demand during the heating season and expanding LNG exports could support the stock, experts say.
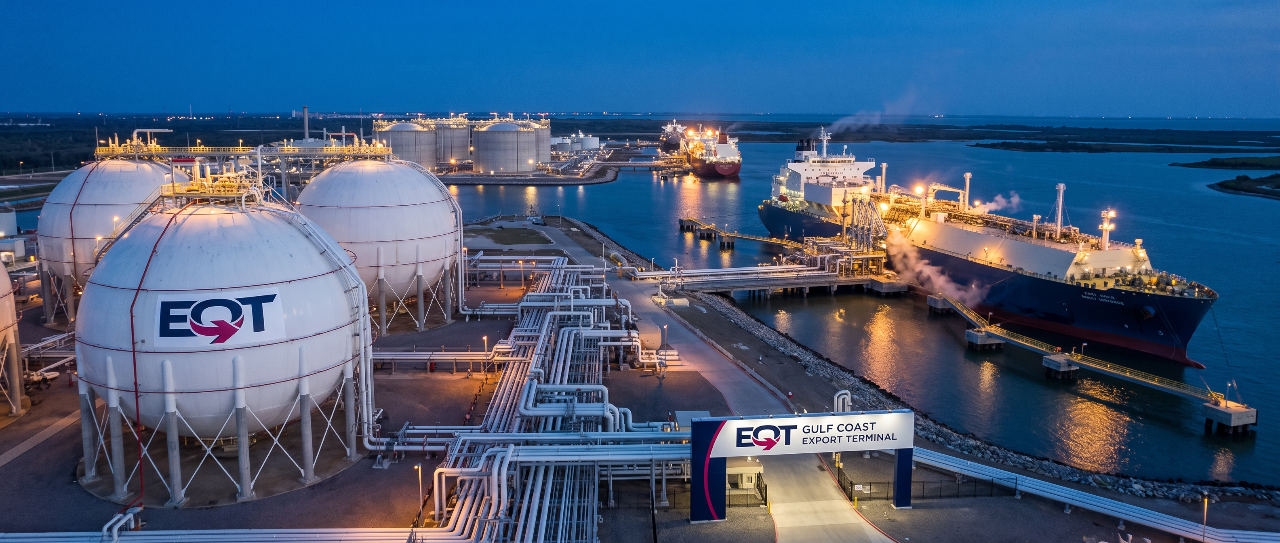
What kind of company is EQT
EQT is one of the largest U.S. natural gas producers. Its core operations are concentrated in the Appalachian Basin, including the Marcellus shale formation. In Q1 2026, natural gas accounted for 94,6% of hydrocarbon sales revenue, so movements in its price significantly affect the company’s results.
Gas demand may rise as cold weather sets in
A driver for the stock, Freedom Broker analysts believe, will be the seasonal increase in gas consumption. In the second half of autumn, its price in the U.S. may climb to $3,75 per million British thermal units (MMBtu). The U.S. Department of Energy forecast предполагает an increase in gas demand by 16,9% in November versus October and by another 17,9% in December versus November, experts emphasize.
Additional support could come from shipments of liquefied natural gas abroad. LNG exports are expected to grow by 6,3% month over month in both November and December. The combination of heating demand and export shipments creates conditions for higher prices, experts explain.
Valuation has fallen below last year’s level
The second argument in favor of the idea is relatively low valuation multiples. The projected price-to-earnings ratio for 2026, P/E, is 12,1 versus a higher level for 2025. The difference reaches 31%. The enterprise value to EBITDA ratio for 2026, EV/EBITDA, is estimated at 6,4 — 23% below last year’s level. According to Freedom Broker, this leaves room for quotes to rise if the gas market develops favorably. Over the past month, EQT shares fell by 10,4%, and over the quarter — by 6%. The market capitalization cited when the investment idea was prepared was about $30,58 bn.
Sales volumes rose, but profit declined
In Q2 2026, EQT’s sales volume increased by 11,6% year over year, to 634 bn cubic feet of gas equivalent. The company exceeded the upper end of its own guidance thanks to high well productivity, system pressure optimization, and less production curtailment due to prices than expected.
At the same time, the average realized price decreased by 5,7%, to $2,65 per thousand cubic feet of gas equivalent. Net income attributable to EQT dropped by 73,1%, to $211 mn, and earnings per share fell from $1,30 to $0,34.
Adjusted net income fell by 10,6%, to $244 mn. Adjusted earnings per share were $0,39 versus $0,45 a year earlier. At the same time, adjusted EBITDA attributable to EQT rose by 3,3%, to $1,067 bn. Unit operating costs declined from $1,08 to $1,03 per thousand cubic feet of gas equivalent. Capital expenditures totaled $666 mn — 9% below the low end of the company’s guidance, though above last year’s $554 mn.
Free cash flow increased by 37,5%
Operating cash flow in Q2 decreased by 15,6% year over year, to $1,048 bn. However, adjusted operating cash flow attributable to EQT increased from $794 mn to $1,014 bn. Free cash flow attributable to the company grew by 37,5%, to $330 mn. Thus, the decline in reported net income was accompanied by an improvement in adjusted cash generation metrics.
By the end of June, total debt was $5,7 bn versus $7,8 bn at the end of 2025, and net debt was $5,5 bn versus $7,7 bn. Liquidity reached about $3,6 bn. After the quarter ended, the company additionally repaid $115 mn of debt.
EQT raises production guidance and expands long-term sales
Following strong operating results, EQT raised its forecast for annual sales volume by about 90 bn cubic feet of gas equivalent, to a range of 2,375–2,450 trillion. At the same time, the company lowered its forecast for annual capital expenditures by $25 mn.
Freedom analytics
In July 2026, Freedom Broker experts initiated coverage of EQT with a “Buy” rating and a target price of $79. At that time, the main arguments were expanding LNG exports, low production costs, and the acquisition of the energy company Olympus Energy for $1,8 bn in 2025.
Not an individual investment recommendation.