
Investment Idea of the Day from Freedom Broker Analysts: CNX Resources
Stock Market News
9 қазан 2026, 12:23
Freedom Broker analysts recommend “Buy” shares of the U.S. gas producer CNX Resources (CNX) with a target price of $37 through November 30, 2026. At the current price of $33.89, the upside potential is about 9.2%. Experts are counting on a seasonal increase in gas demand, while additional arguments include a relatively low business valuation and share buybacks.
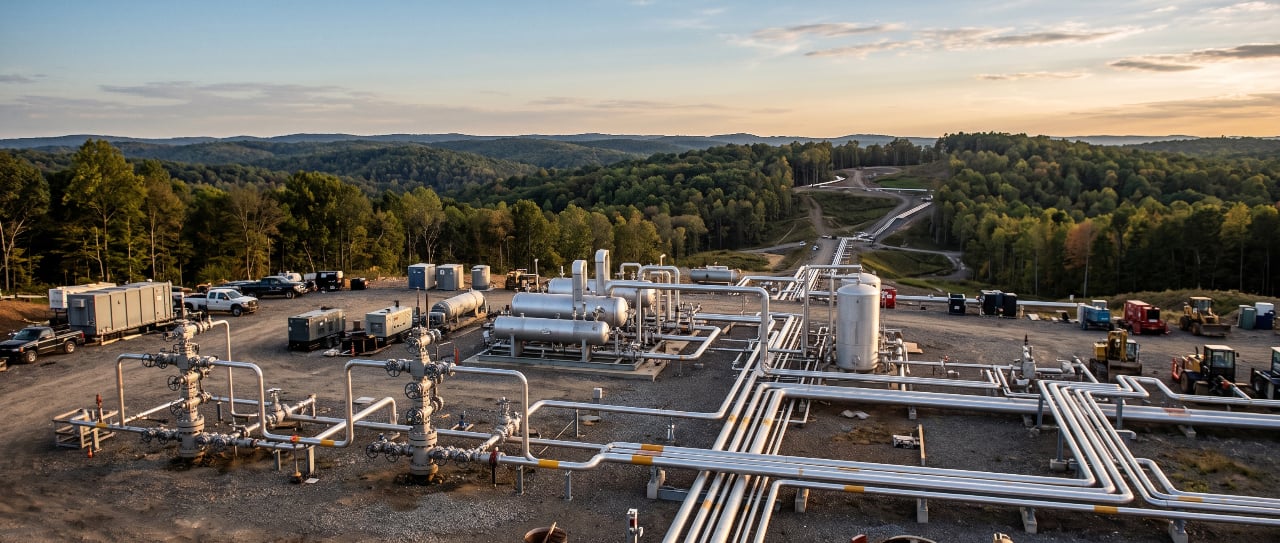
What CNX Resources is
CNX Resources is an independent gas-producing company operating in the Marcellus and Utica shale plays in the Appalachian Basin of the U.S. Its headquarters are in Canonsburg, Pennsylvania.
Based on 2025 results, natural gas accounted for about 91% of revenue from hydrocarbon sales, and natural gas liquids for about 9%. Therefore, gas demand and its price remain key factors for the business.
Heating season could support the share price
Freedom Broker expects that in the second half of autumn, U.S. gas prices may rise to $3.75 per million British thermal units, a standard unit of measurement in the U.S. gas market. This is 24.5% above the closing price of the NYMEX November futures on September 29 used in the report.
According to the U.S. Department of Energy forecast cited by the analysts, gas demand will increase by 10.6% quarter over quarter in Q4 2026 and by another 14% in Q1 2027. Additional support should come from liquefied natural gas exports: growth is expected at 7.8% and 4.5%, respectively. In experts’ view, the seasonal recovery of the gas market could improve investor sentiment toward CNX shares.
Hedging reduces dependence on price fluctuations
The company has locked in prices in advance for about 81% of expected gas production in 2026 using financial contracts. This approach protects cash flow when market prices decline, but at the same time limits the direct benefit from their growth.
At the same time, as Freedom Broker analysts note, prices locked in for 2027, taking regional basis adjustments into account, are 21% higher than 2026 levels. This creates prerequisites for improved financial results next year.
Business valuation and share buybacks are additional arguments
At the time of preparing the report, CNX’s forward price-to-earnings ratio, or P/E, was 10x for 2026 and 7.6x for 2027. The EV/EBITDA multiple, comparing enterprise value to earnings before interest, taxes, depreciation, and amortization, was at 5.5x and 4.9x, respectively. Freedom Broker considers these valuations relatively low.
The company projected about $525 mln in free cash flow for 2026. In the report, this amount corresponded to 11.4% of CNX’s market capitalization — a figure calculated using the share price as of the date the material was prepared.
Another supporting factor is share buybacks. According to the report, since the beginning of 2025 CNX has repurchased about 24 mln shares for $781 mln, offsetting the issuance of roughly 22 mln shares to redeem convertible notes. After the redemption is completed, further buybacks should directly reduce the number of shares outstanding.
As of the end of June, the unused amount of the buyback program was $2.17 bln. This is the authorized limit the company can use to repurchase its own shares. CNX_Invest Idea
CNX’s latest results
In Q2 2026, CNX generated $138 mln in free cash flow. The metric remained positive for the 26th consecutive quarter, and its cumulative amount since the start of the seven-year plan in 2020 reached about $3.1 bln.
During the quarter, the company repurchased about 5.6 mln shares for $199 mln. After it ended and before the July materials were released, it bought another 1.2 mln shares for $40 mln.
Management maintained its full-year free cash flow guidance of about $525 mln, based on market gas prices in mid-July. Thanks to share buybacks, the forecast for this metric per share increased from $3.41 to $3.55. The company also expected quarterly production volume to reach a peak in Q4.
Not an individual investment recommendation.