
Freedom reiterates Hold rating on General Motors with $76 price target
Stock Market News
22 October 2026, 22:26
Model range updates and persistent cost pressure could limit General Motors’ (GM) fourth-quarter results, according to Freedom Broker senior analyst Dmitry Pozdnyakov. Despite beating quarterly expectations, he lowered his forecast for the company’s financial metrics, while maintaining a Hold rating and a $76 per-share target price.
General Motors is a U.S. automaker producing vehicles under the Chevrolet, GMC, Cadillac, and Buick brands. The company’s main market is North America. The GM Financial unit provides financing to buyers and dealers.
Revenue increased, profit slightly exceeded expectations
According to the report published on October 20, GM’s third-quarter revenue totaled about $50 bn, while net income was $3.3 bn. Adjusted earnings before interest and taxes reached $4.1 bn.
Freedom’s report notes that revenue rose 2.9% year over year and topped the FactSet consensus forecast of $48.78 bn. Adjusted earnings per share came in at $3.70 versus the expected $3.69.
Adjusted EBIT margin improved from 6.9% to 8.2%. Results were supported by higher deliveries, lower warranty expenses, and reduced costs related to electric-vehicle production. At the same time, pressure from raw materials, logistics, and shifting production to the U.S. persisted.
Delivery growth supported the core business
GM wholesale deliveries increased 5.2% year over year to 1.028 million vehicles. In North America, growth was 3.5%, while outside the region it was 16.1%.
Revenue at the North American division rose 2.1% to $41.42 bn. GM’s average selling price in the U.S. remained around $52k, roughly in line with the previous quarter.
The international automotive division increased revenue by 12% to $4.09 bn, driven by a higher number of vehicles sold.
Pickup refresh may limit fourth-quarter results
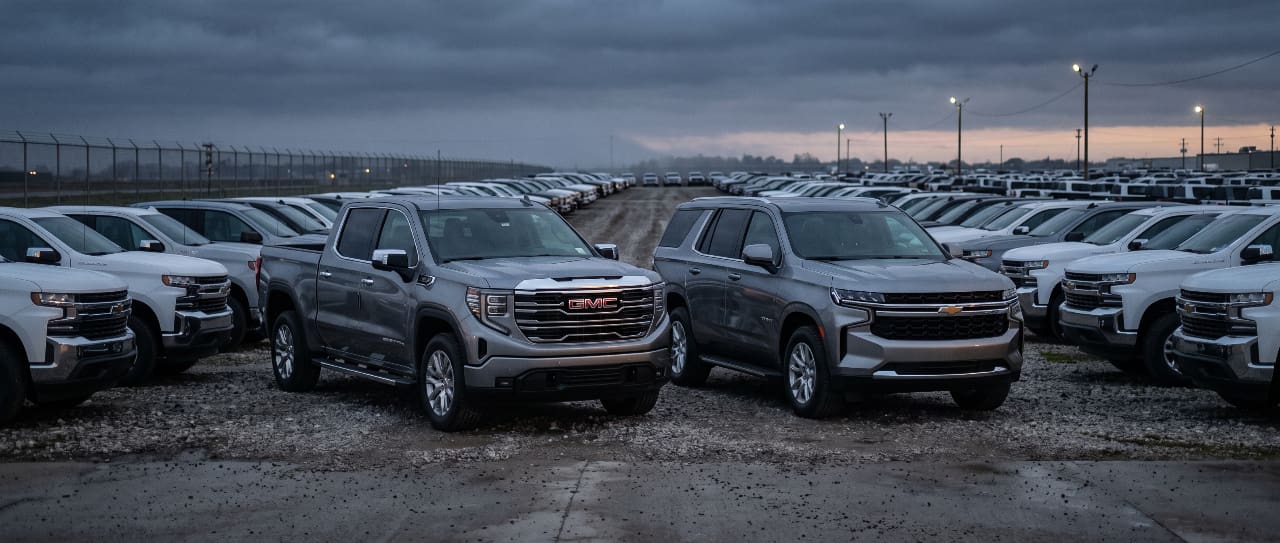
Management warned that North American deliveries in the current quarter could come in below normal due to preparations for a full-size pickup refresh.
Freedom now expects deliveries in the region to decline 0.5% year over year in the fourth quarter. The forecast for total quarterly revenue is $44.4 bn, 2% lower than a year earlier.
Pozdnyakov notes that earlier estimates had implied stronger delivery growth in the coming quarters. After the revision, the analyst forecasts GM revenue at $186.07 bn in 2026 and $191.14 bn in 2027.
GM refined full-year guidance and announced a share buyback
The company narrowed its 2026 adjusted EPS guidance to $12.75–13.75 from $12–14. Adjusted EBIT is guided at $14.5–15.5 bn.
The board also approved a new multi-year $20 bn share repurchase program and a quarterly dividend of $0.18 per share. Buybacks reduce the number of shares outstanding and can support earnings per share.
At the same time, Freedom maintains a neutral view on the stock: the $76 target price reflects more subdued expectations for deliveries during the model range refresh period.
Strong pickup demand preceded the forecast revisions
Previously, Freedom Broker reported an increase in GM’s U.S. sales driven by demand for pickups and SUVs. At the time, the company also said that next-generation full-size pickups should arrive at dealerships by year-end.
Updating these models creates prerequisites for further sales, but the transition period may temporarily constrain deliveries. This factor, along with costs, is limiting Freedom’s optimism regarding GM’s near-term results.
This is not an individual investment recommendation.