
Investment idea of the day: Freedom analysts see 31% upside for DNOW
Stock Market News
12 қараша 2026, 12:10
Freedom analysts upgraded shares of industrial equipment supplier DNOW (DNOW) to “Buy” and maintained a $18 price target. From the $13.72 quote used in the November 9 report, the upside potential is about 31.2%. Experts link the company’s prospects to the integration of MRC Global, improving profitability, and demand for equipment for gas and energy infrastructure.
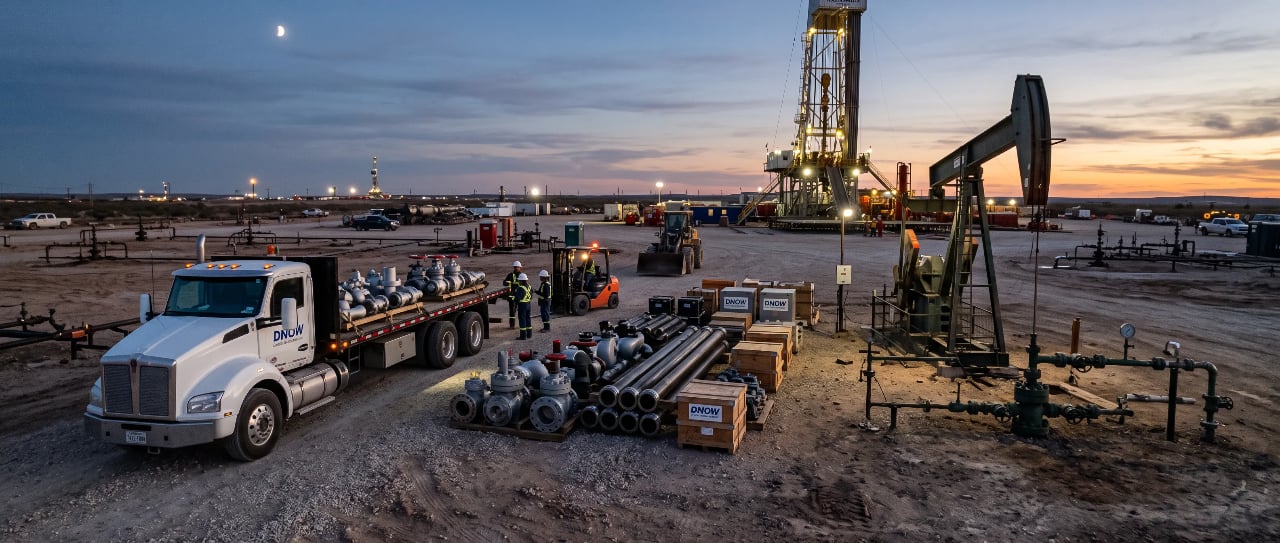
DNOW supplies pipes, valves, pumps, compressors and other solutions for oil and gas and industrial companies. The company also helps customers organize procurement and manage supply chains. After acquiring MRC Global in November 2025, it expanded its business and reduced its dependence on upstream producers.
Profitability is growing faster than sales
In the third quarter of 2026, DNOW increased revenue to $1.34 billion — up 2.3% versus the previous quarter and up 110.9% year over year. The more than twofold annual growth is largely explained by the inclusion of MRC Global in the group’s financials. Adjusted EBITDA reached $76 million.
For Freedom analysts, more important is that the company is consistently improving profitability. Adjusted EBITDA rose 26.7% quarter over quarter, and its margin increased from 4.6% to 5.7%. Adjusted EPS reached $0.18 versus $0.12 in the prior quarter.
The company sold more higher-margin products, improved efficiency, and cut costs. Selling, general and administrative expenses decreased by $6 million versus the second quarter. In Freedom’s view, the results show that the integration of MRC Global is beginning to deliver a more tangible financial effect.
Gas infrastructure supports demand
One of the most resilient areas was supplies to gas utilities. Revenue from these customers increased 4% quarter over quarter and reached a three-year high. Customers are modernizing infrastructure, and DNOW is expanding cooperation with them.
Sales to downstream and industrial customers rose 10% over the quarter. Revenue from customers engaged in gathering, processing and transporting hydrocarbons increased by about $20 million. Analysts believe this mix makes the business more balanced. The company earns income not only from drilling and production, but also from servicing infrastructure. Management also sees additional opportunities in LNG projects and in powering data centers.
Key bet: profit recovery in 2027
Freedom expects DNOW’s revenue to increase by 6.7% in 2027, to $5.39 billion. At the same time, adjusted EBITDA, according to analysts’ forecast, will rise by 42.9% to $328.5 million, and its margin will reach 6.1%.
Growth should be driven by customer investment in gas infrastructure, a rebound in upstream and industrial activity, and further cost reductions after the combination with MRC Global. Adjusted EPS, in Freedom’s estimate, could increase from $0.40 in 2026 to $0.79 in 2027.
Management’s preliminary scenarios assume EBITDA next year at $300–350 million. This range broadly matches Freedom’s calculations and supports the analysts’ expectations.
What could prevent the thesis from playing out
The next quarter may be weaker than the third due to a seasonal reduction in customer spending. Freedom forecasts revenue declining to about $1.22 billion and adjusted EBITDA to $54.8 million. Some of the pressure could be eased by deliveries under previously deferred international projects.
Risks also remain in the integration of MRC Global. The company continues migrating business units to a unified enterprise management system. Delays could complicate customer service, inventory management, and cost cutting.
Other risk factors include rising transportation costs, lower investment by oil and gas companies, and commodity price volatility. Therefore, improvements in DNOW’s results depend both on the company’s own actions and on customers’ willingness to finance new projects.
How Freedom’s view has changed
In June, Freedom Broker initiated coverage of DNOW with a “Buy” rating and a $16 price target. Even then, analysts highlighted the combination with MRC Global and the expansion of its presence in gas infrastructure as the main growth drivers.
In the November note, experts maintained the current $18 target and upgraded the recommendation to “Buy.” The new analysis is based on improved quarterly margins and further progress in integration.
Not an individual investment recommendation.