Двухнедельный обзор фондовых рынков №317. «Медвежий» капкан Трампа
Company News in Focus for Our Analysts
Nike
Nike (NKE) shares fell another ~8% after management signaled that the revenue decline will persist into FY27, with further pressure on earnings. The market reaction was decisively negative, pushing the stock to its lowest level since 2013. Q1 revenue declined 4.3% YoY to $11.21bn, missing consensus. China remained a major drag, with sales down 22% YoY in USD terms, pushing the region to the bottom of Nike’s geographic segments by revenue. Direct sales also declined materially across regions. However, the key issue was the outlook. Management sees no quick stabilization, guiding to ~4% YoY revenue contraction in Q2 and a high-single-digit revenue decline for FY27.
Carnival
On September 29, Carnival Corp. (CCL) reported Q3 FY26 results for the quarter ended August 31, with adjusted EPS and revenue beating consensus. Adjusted EPS came in at $1.43 vs. $1.35 expected, while adjusted EBITDA reached $2.993bn and revenue hit a record $8.435bn. Adjusted EBITDA and EPS were broadly flat YoY despite a 36% increase in fuel cost per ton. Unlike in Q2, the beat was more balanced, with both net yields and costs outperforming expectations. Constant-currency net yields rose 2.4%, well ahead of the ~1.2% June guidance, while ex-fuel unit costs increased just 1.8% vs. 2.8% expected. Customer deposits reached a Q3 record of $7.6bn. CCL shares jumped 13% on the results.
IDT Corporation
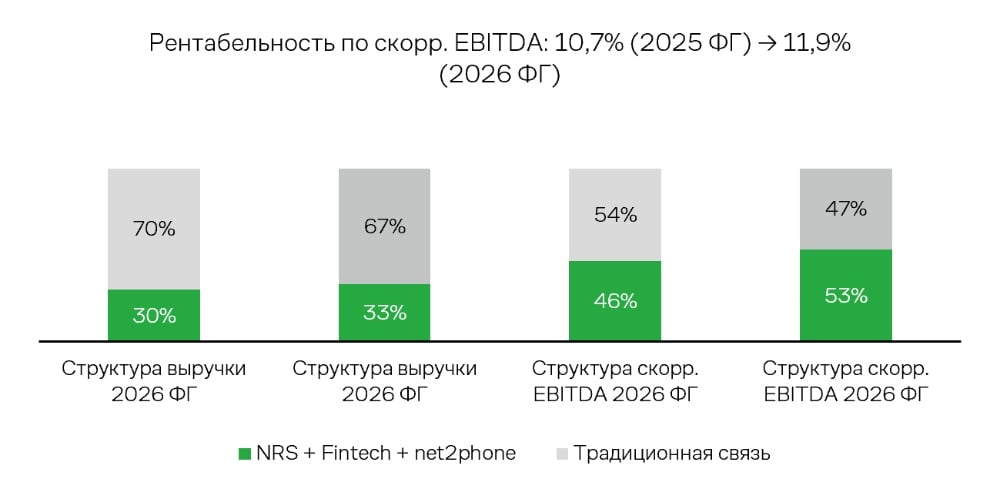
IDT exited FY26 on a strong note, with growth increasingly driven by higher-margin businesses. Q4 revenue rose 7% YoY to $339m, while adjusted EBITDA increased 22% to $41.2m. For FY26, adjusted EBITDA grew 17% to $154.6m, beating the company’s revised guidance. The key takeaway is the improving earnings mix. NRS, Fintech and net2phone accounted for 53% of consolidated segment EBITDA in FY26 vs. 46% in FY25, despite contributing only ~one-third of revenue, which points to an improving business mix. For FY27, management expects adjusted EBITDA to grow ~15% at the midpoint. NRS is expected to sustain its strong growth trajectory, Fintech should benefit from further operating leverage, while net2phone plans to reinvest part of its EBITDA growth into the development of AI solutions.
NVIDIA
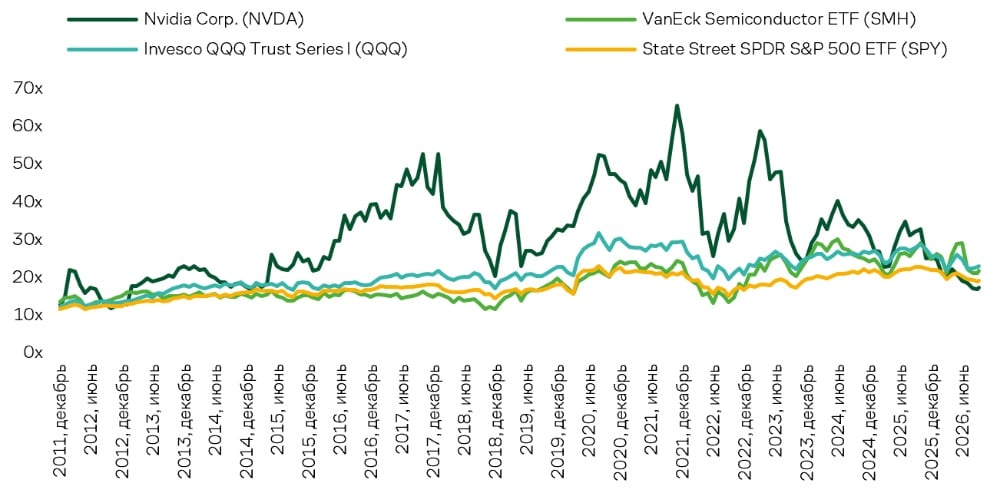
On September 28, Nvidia Corp. (NVDA) expanded its share repurchase authorization by $150bn, taking total remaining buyback capacity to $235bn through FY28. The increase marks the largest buyback expansion in corporate history, surpassing Apple’s previous $110bn record set in 2024. While the headline figure is substantial, the combined authorization amounts to only ~4.2% of Nvidia’s current market cap. The move signals management’s conviction in the durability of AI demand, while the shares look undervalued: despite a run of strong reports and regular guidance raises, the stock continues to trade at ever-lower multiples. On NTM P/E, NVDA is now trading at levels broadly comparable with early 2015, when AI was barely part of the investment narrative and Nvidia’s core business was still PC GPUs. Shares currently trade at >50% discounts to their 10-year historical average multiples and at a substantial discount to key equity indices and sector ETFs.
Micron Technology
On September 30, Micron Technology (MU) reported strong Q4 FY26 results and issued above-consensus guidance for Q1 FY27. The bigger takeaway, however, is the potential length and intensity of the cycle: management now expects the supply deficit to be more pronounced in 2027 and 2028 than in 2026, supported by a materially expanded long-term contract book. Q4 revenue, gross margin and EPS all exceeded consensus, our estimates and the high end of company guidance, with pricing again the key driver. Q1 FY27 guidance also came in above consensus on both revenue and EPS. Industry bit shipments remain supply-constrained, with cleanroom capacity, rather than demand, emerging as the key bottleneck. Micron’s Strategic Customer Agreements (SCA) portfolio expanded to 26 contracts, representing ~$150bn of remaining performance obligations (RPO) and $32bn of customer financial commitments. Importantly, new agreements are being signed at current, more supply-constrained market pricing.