Investment Review №354. AI lends a hand to the bulls
Vadim Merkulov
Head of Analytics department
Intuitive Surgical. A Successful Business
ISRG shares are a good buy with a target price of $540
About company
Intuitive Surgical (ISRG) is the global leader in robotic-assisted surgery. The company develops the da Vinci platform for minimally invasive procedures and the Ion platform for robotic lung diagnostics. Its model combines system sales and leases with high-margin recurring revenue from instruments and services. In Q2 2026, recurring revenue accounted for 85% of total revenue.
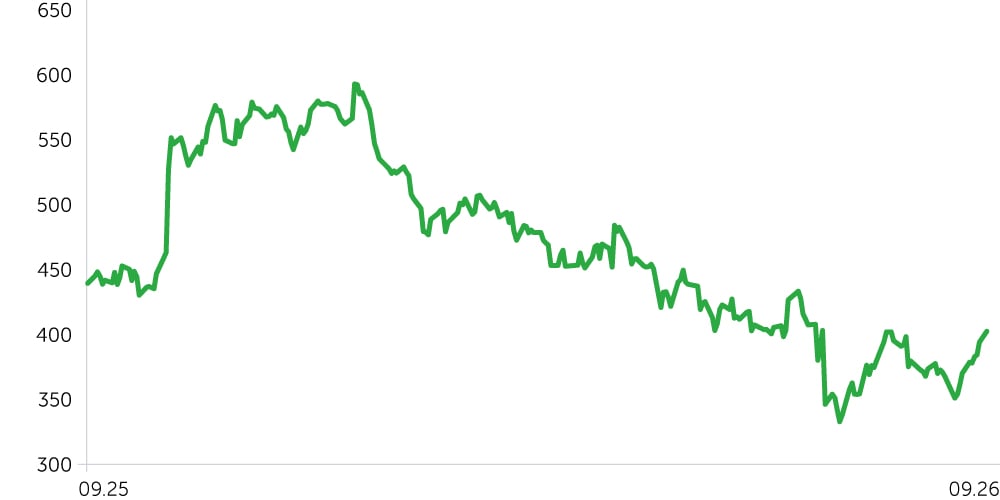
Price dynamics ISRG, $
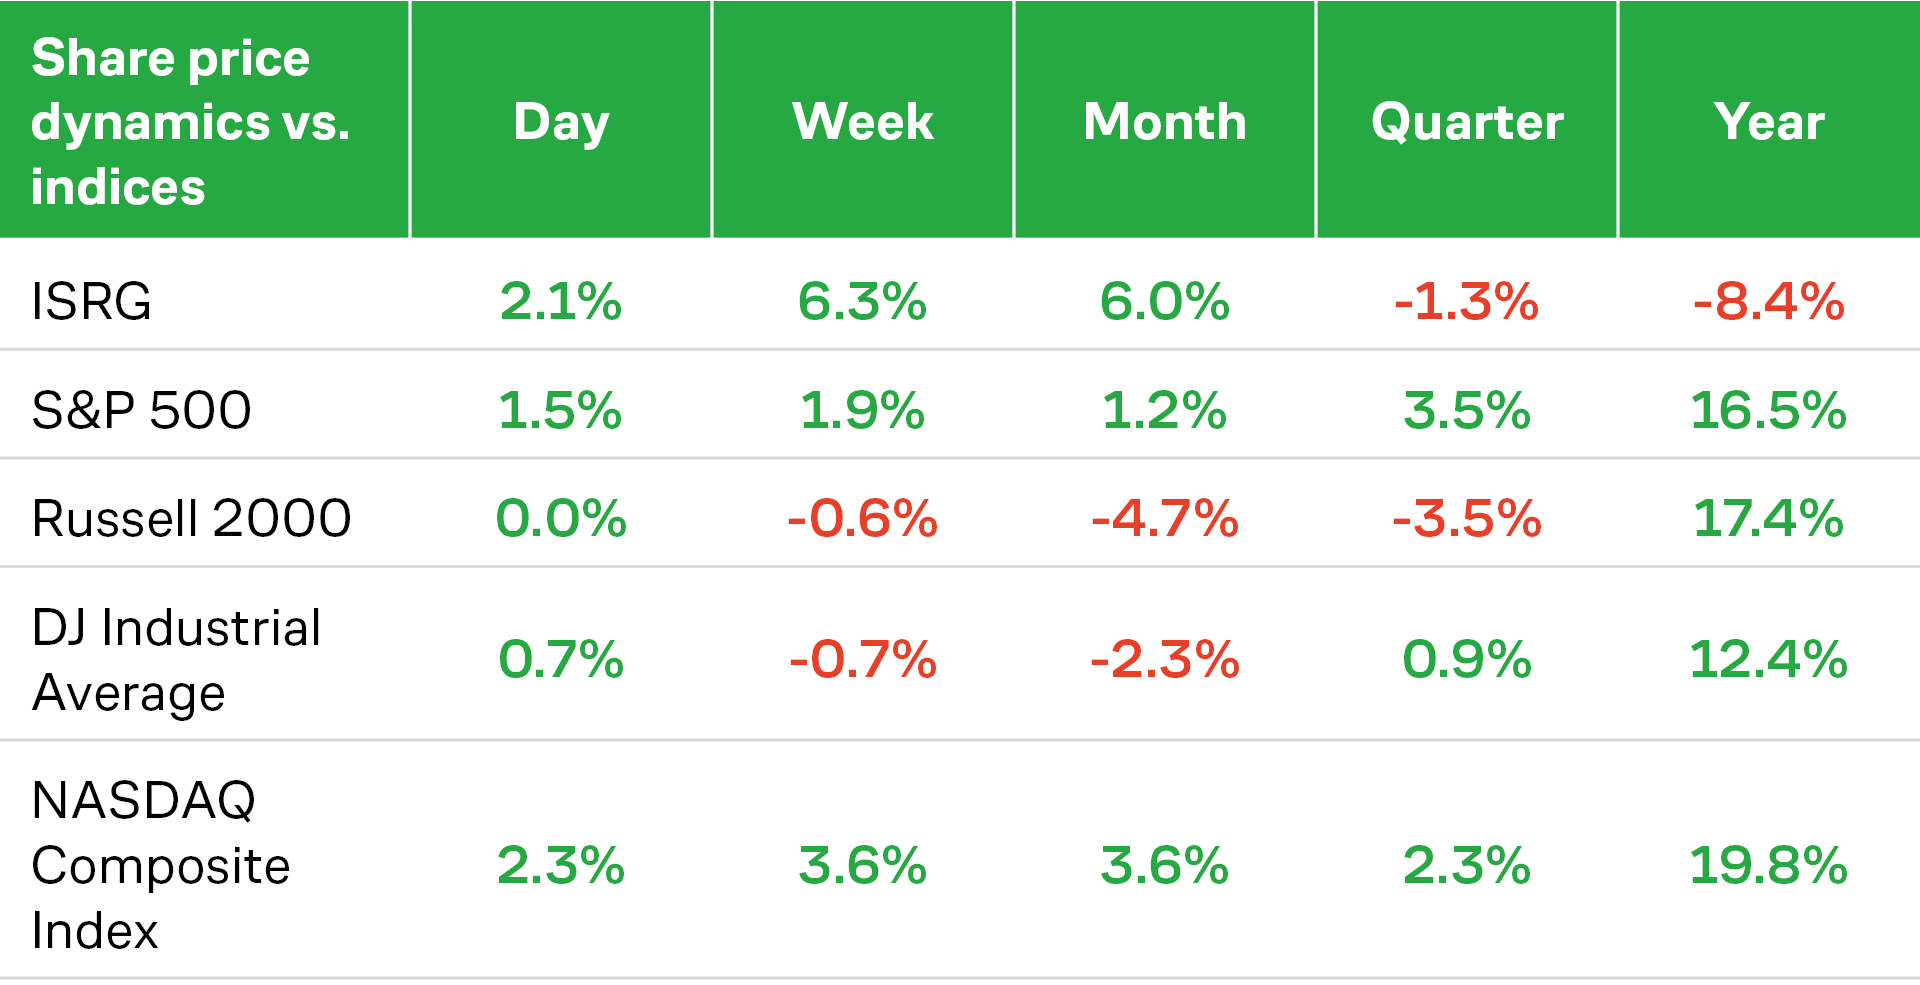
Key Investment Theses
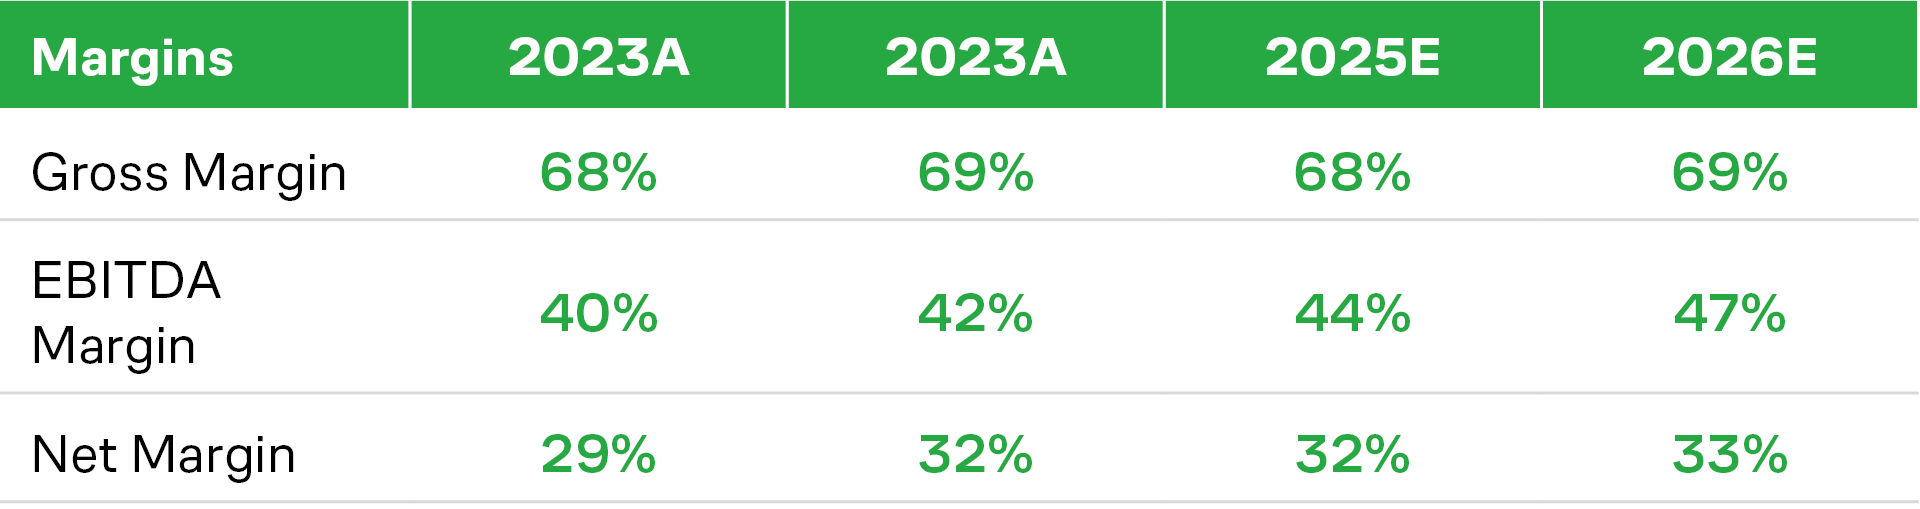
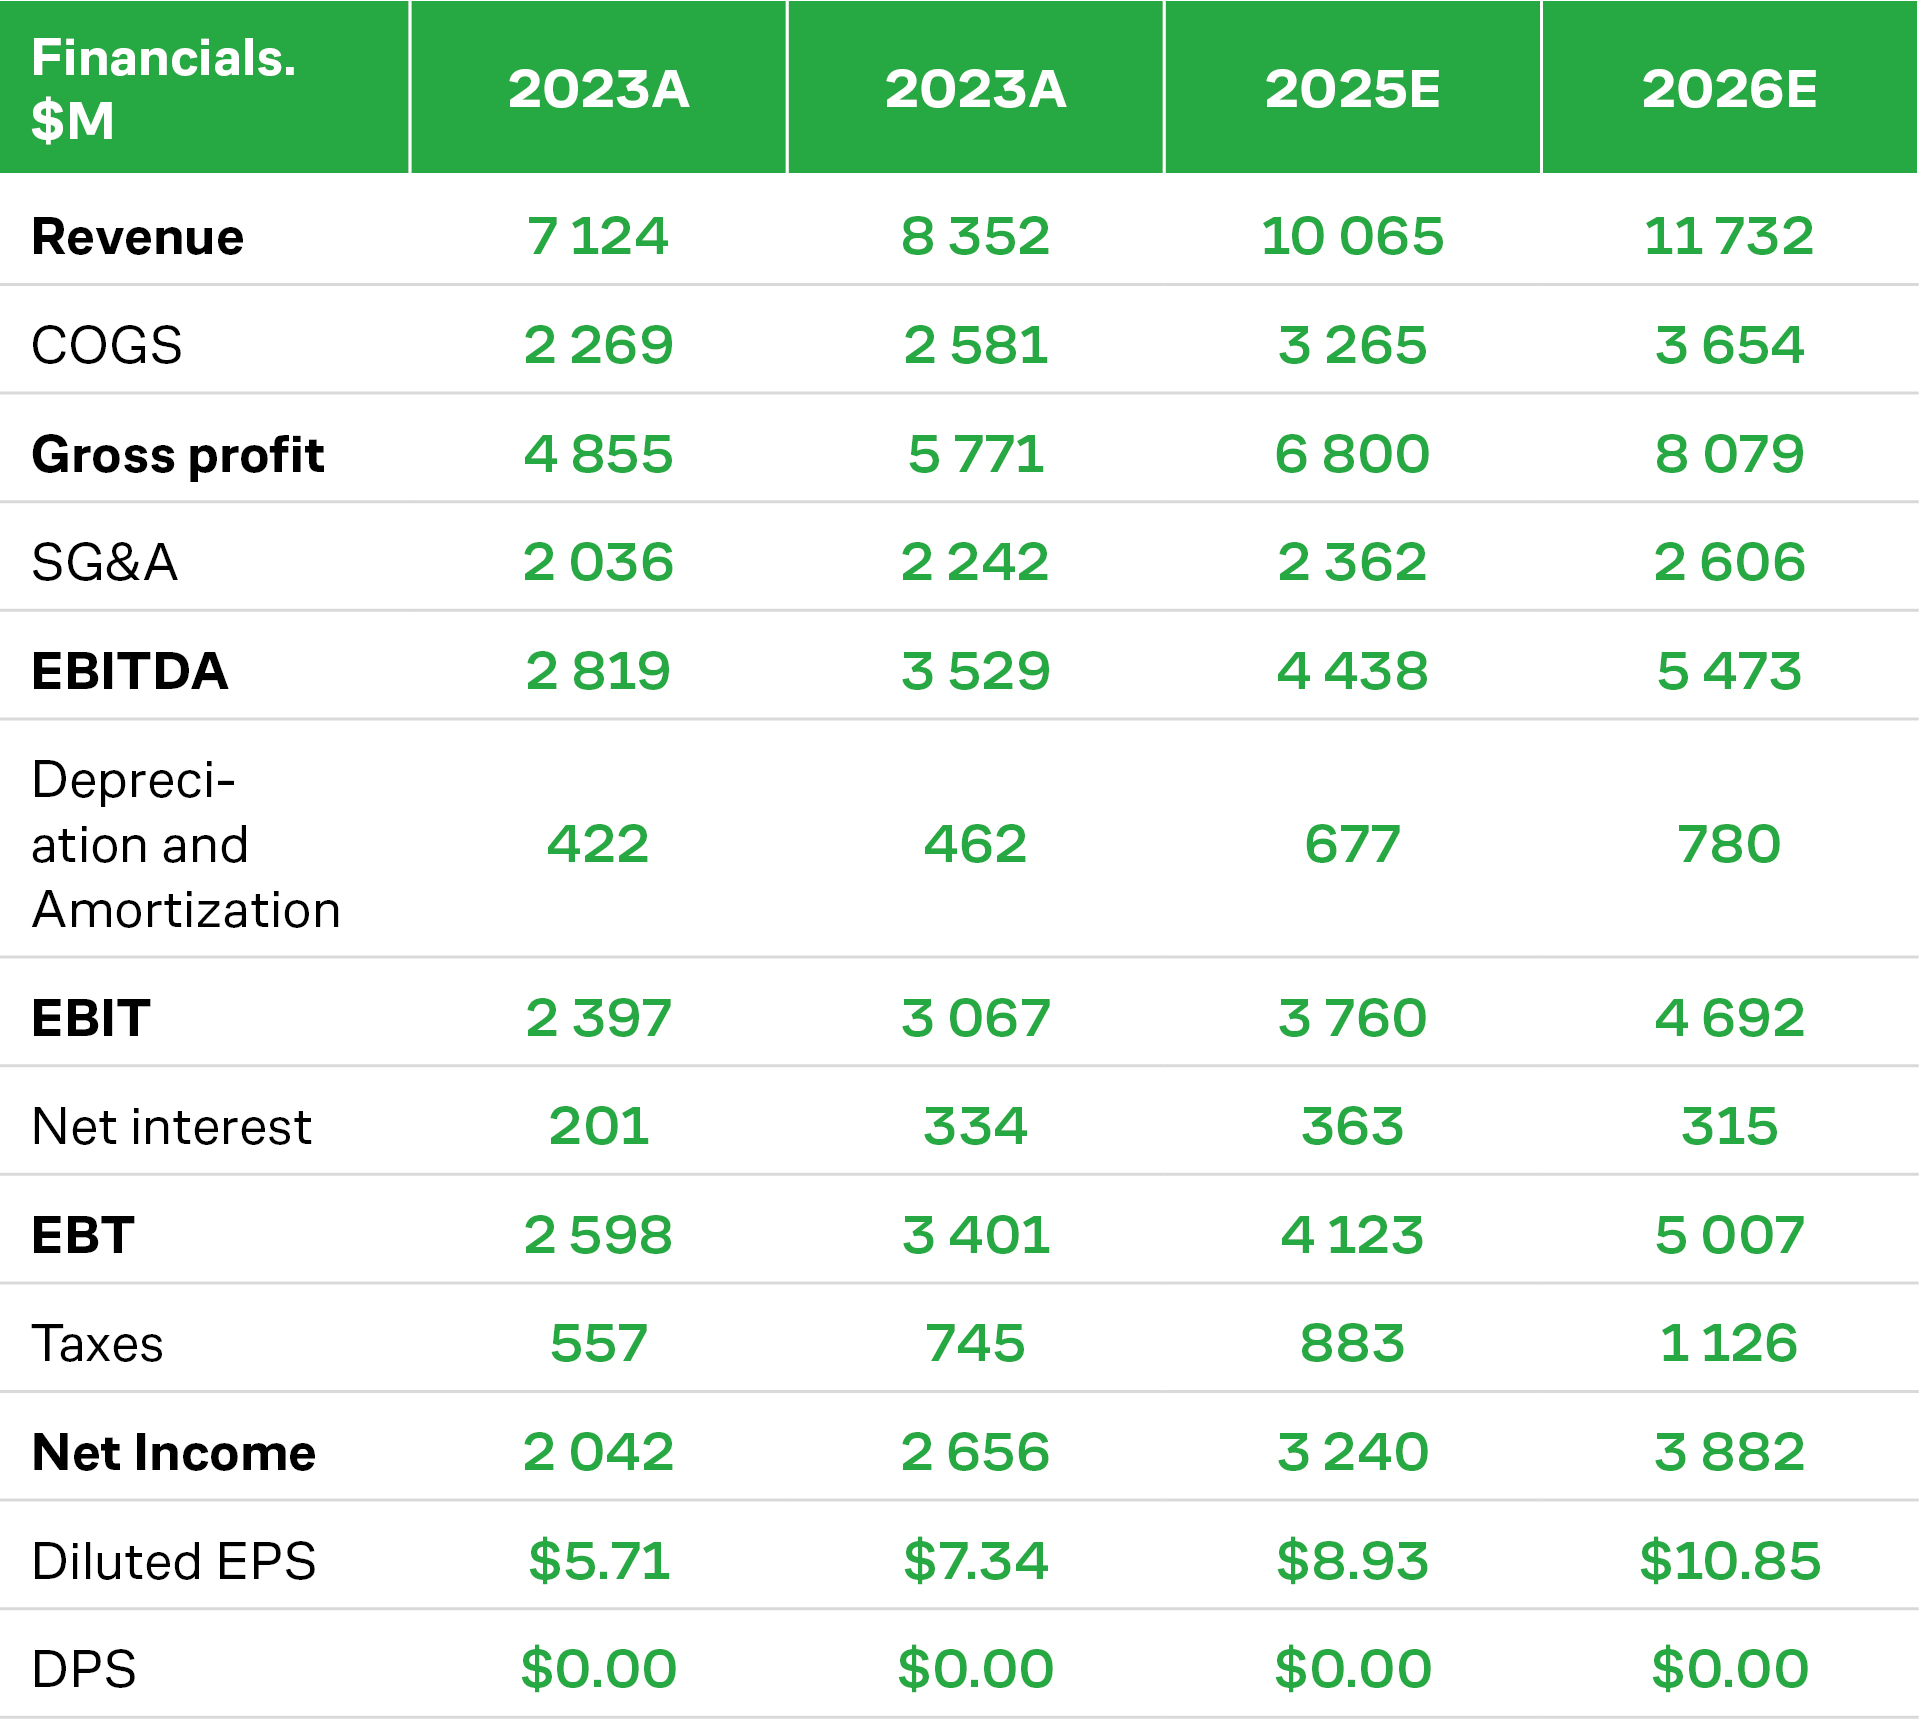
In Q2 2026, revenue grew 19% YoY to $2.89bn, while procedures increased 16% (+15% for da Vinci and +36% for Ion). ISRG installed 468 da Vinci systems (+18% YoY), including 246 da Vinci 5 units. The main weak point was U.S. da Vinci procedure growth, which slowed to 12% YoY from 14% in Q1, reflecting sluggish planned surgery volumes, GLP-1 headwinds in bariatrics, and deteriorating access to care. International da Vinci procedures rose 20%. Non-GAAP EBIT margin reached 42.1%, materially ahead of expectations on stronger gross margin and operating leverage.
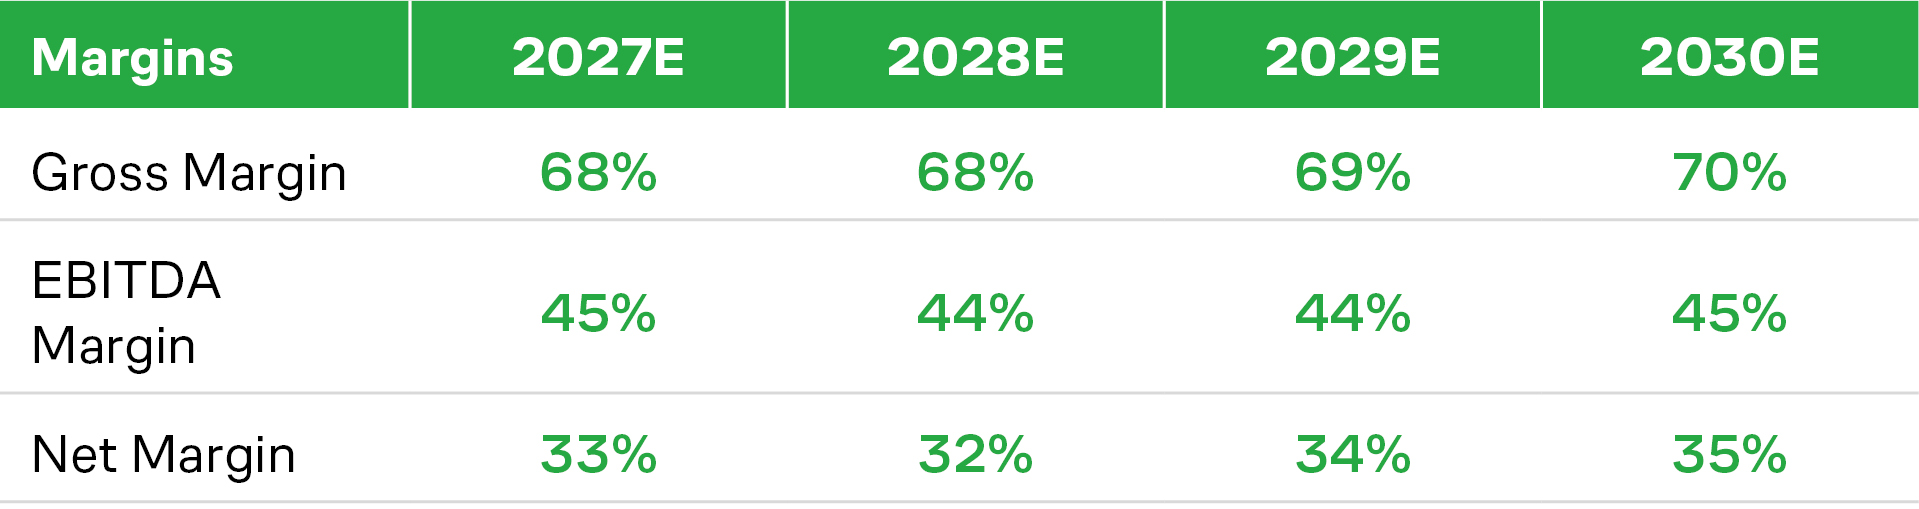
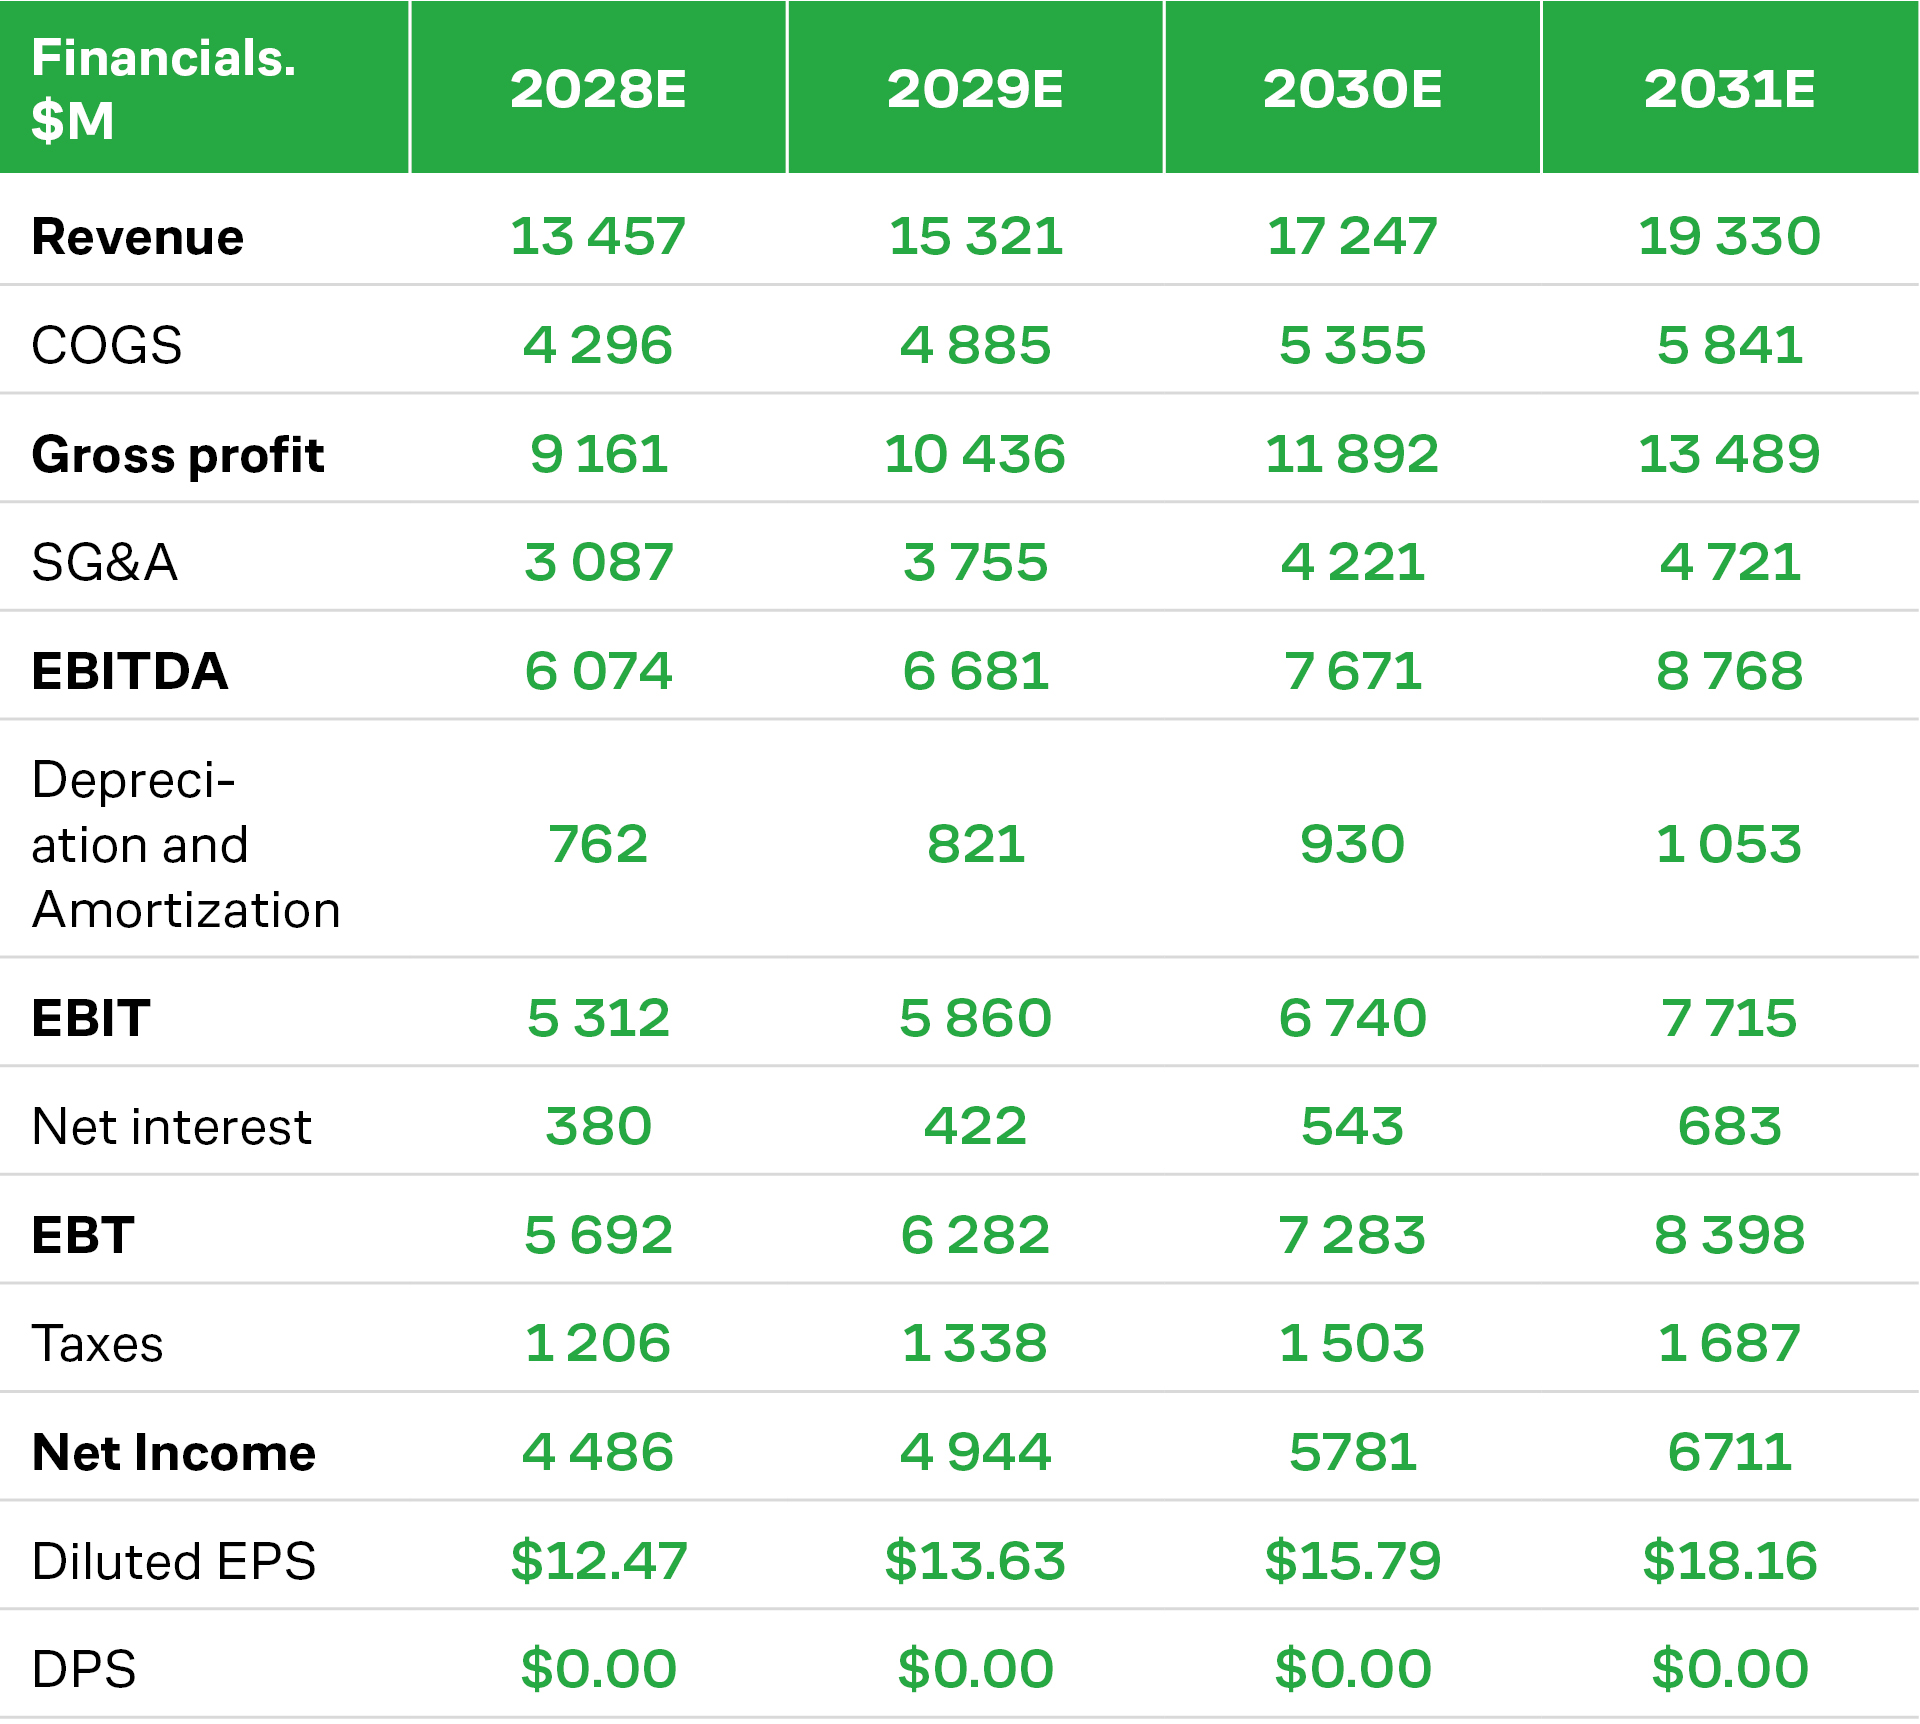
The primary long-term growth driver remains the multi-year upgrade cycle to da Vinci 5, which supports system sales, service revenue, and platform utilization. Additional upside comes from rapid growth in SP and Ion, international expansion, improved insurance reimbursement in Japan, and the rollout of da Vinci 5 in new markets. Refurbished XiR systems and the Extended Use program should lower per-procedure costs and expand penetration in price-sensitive segments. Expense growth remains below revenue growth, supporting margins and EPS.
Key risks include a sharper U.S. procedure slowdown, further GLP-1 pressure on bariatrics, weakness in China from local competition and regulatory constraints, and multiple compression as ISRG transitions to a more mature growth profile. The Extended Use program may also exert near-term pressure on Instruments revenue per procedure.
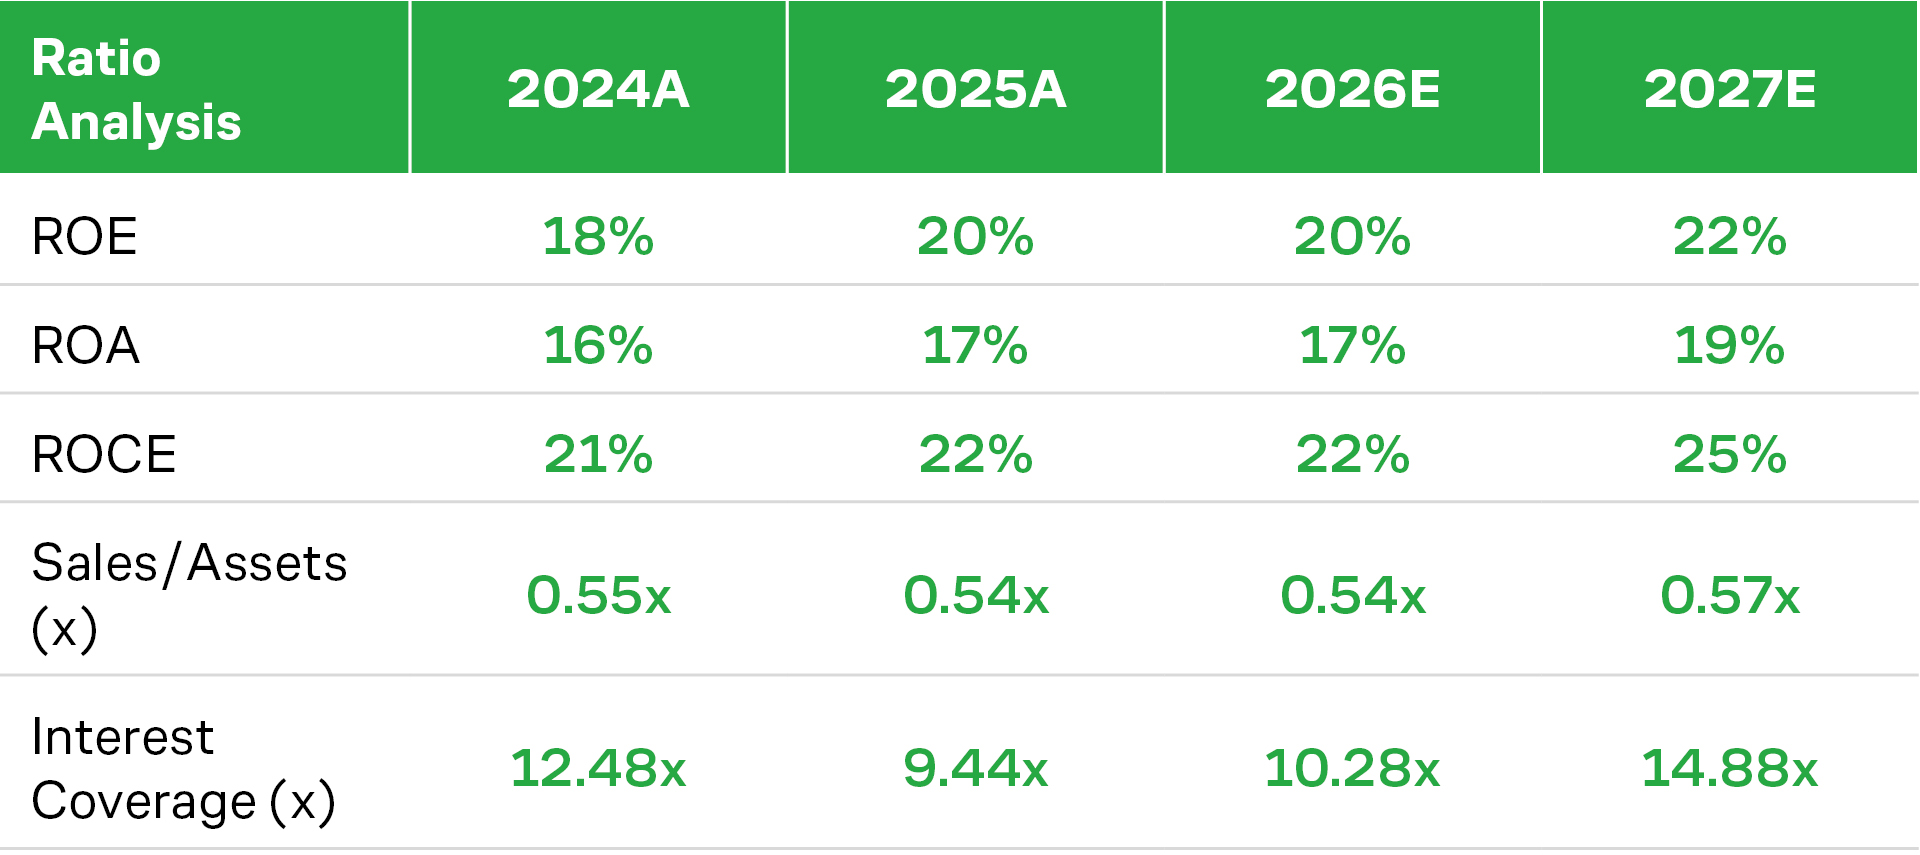
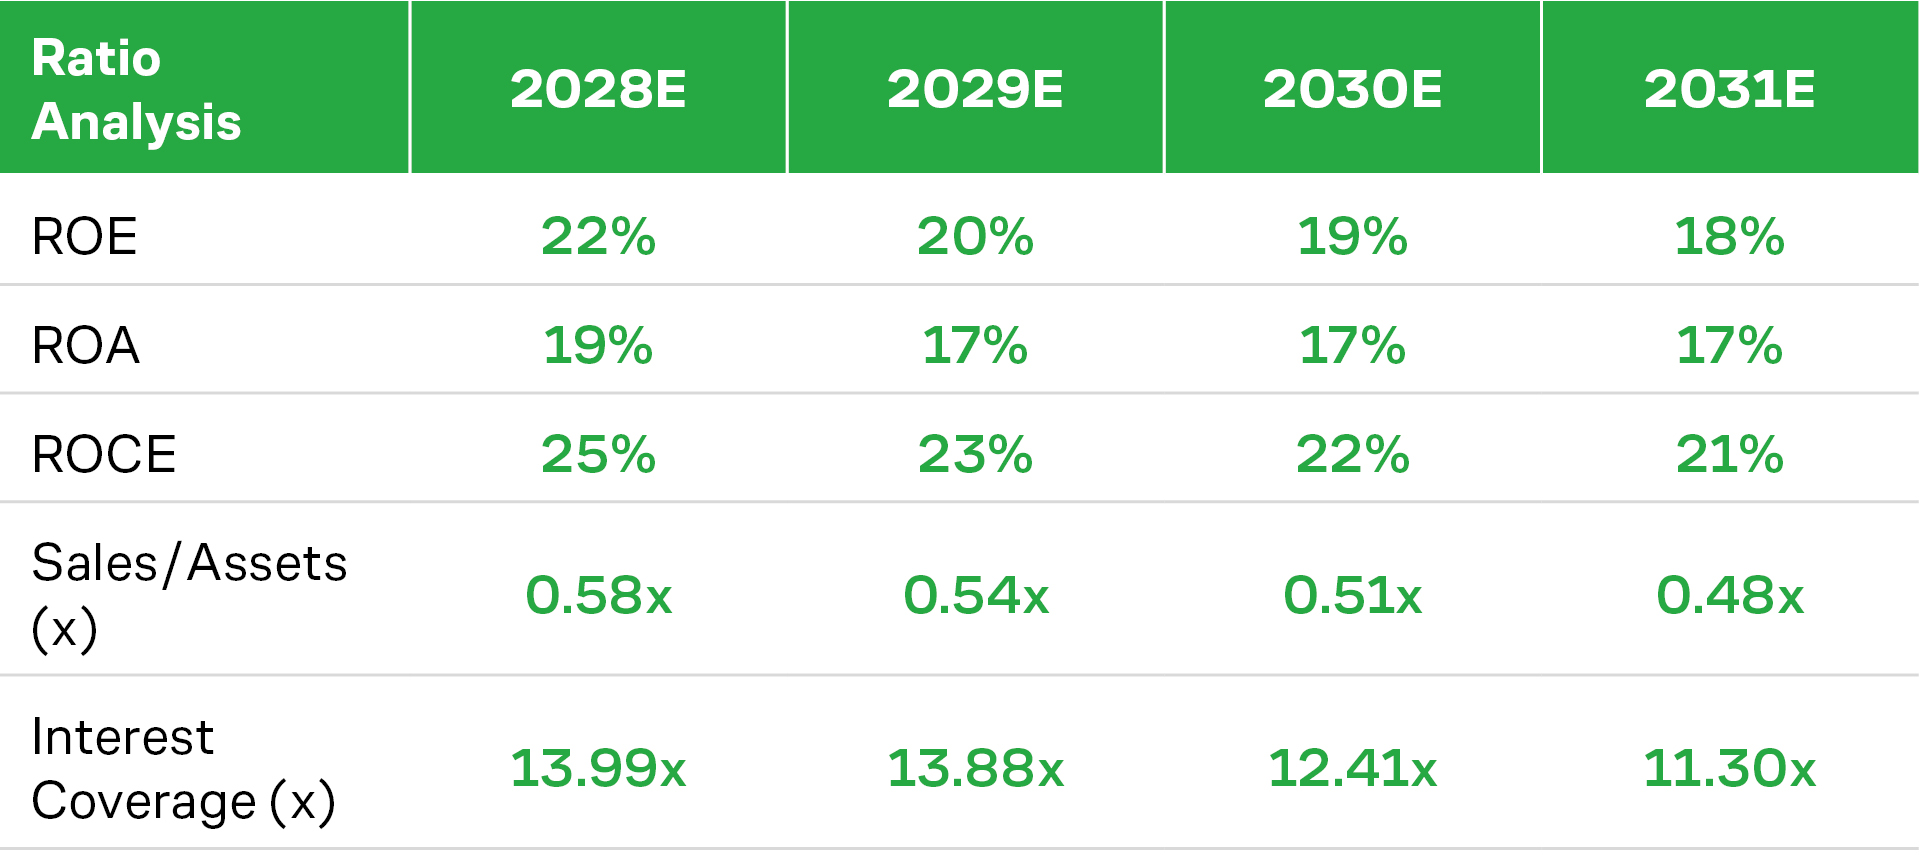
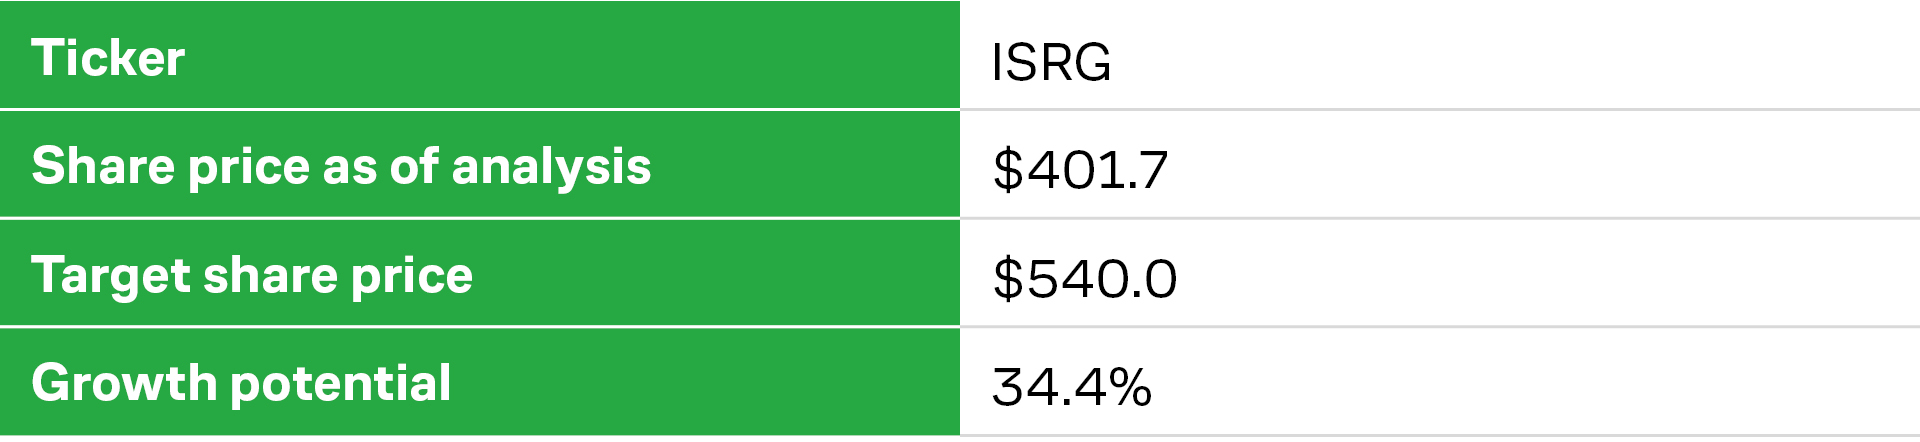
Our rating is Buy, with a $540 price target. We recommend setting a stop-loss at $320. We believe the current valuation already discounts normalized procedure growth but underestimates the durability of earnings. We forecast revenue CAGR of roughly 15% in 2026–2028, with faster EBIT growth on operating leverage. Our price target is based on a 5-year DCF, 50x NTM P/E, and 15x EV/Sales. Our positive view is supported by ISRG’s market leadership, high recurring revenue mix, and the growth potential of da Vinci 5, SP, and Ion.