Investment Review №356. A Reassessment of Values
LONG CALL ON DIS
Trade Thesis
Buy the DIS 115 Call as a bet on further share-price recovery and a potential re-rating ahead of Disney’s November 17 earnings. Improving streaming profitability and strong Experiences results could support the FY2027 EPS outlook.
Key Arguments
- Disney+ and Hulu are improving profitability; subscription price increases could lift ARPU if churn remains contained.
- Experiences continues to grow revenue and operating income, supported by theme parks and cruise expansion.
- A moderate forward P/E (~14–15x) and November 17 earnings offer room for a re-rating if guidance is strong.
Risk Management
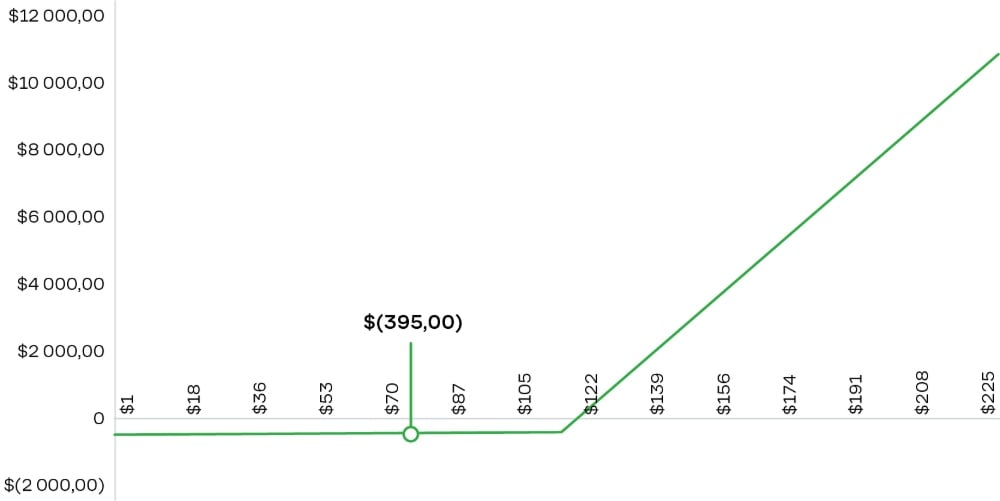
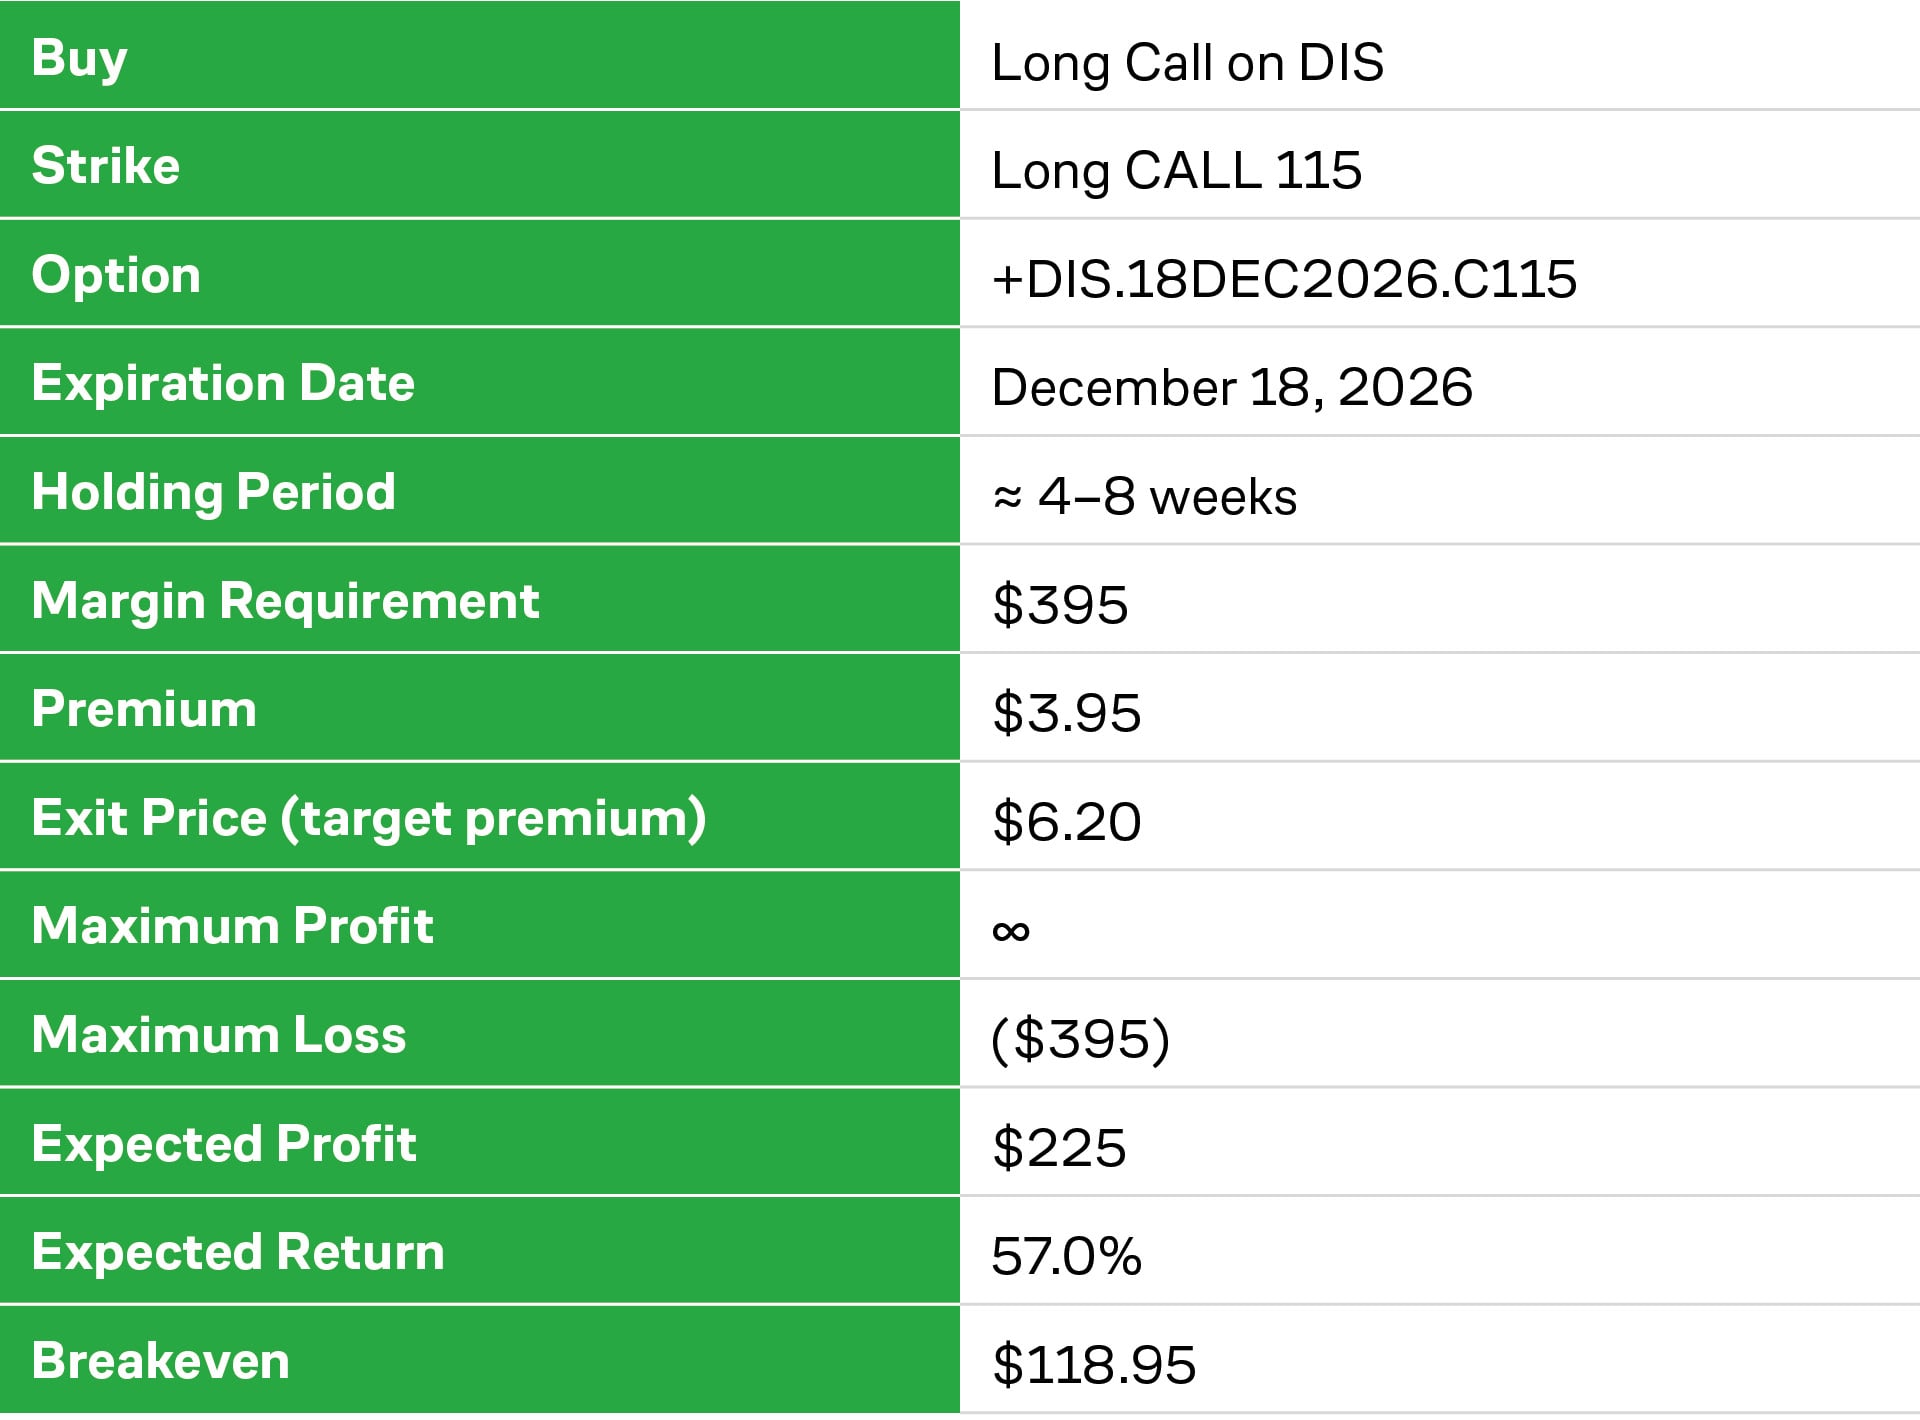
- DIS < $115 at expiration: maximum loss of $395.
- $115–118.95: partial loss.
- DIS > $118.95: profit at expiration.
- Target premium: $6.20 (+57.0%).
Risks: weak advertising demand, higher ESPN rights costs and subscriber churn after price increases. Disappointing November 17 earnings or a post-earnings IV decline could sharply reduce the option’s value.
Trade Parameters
Strategy Profit and Loss