
Investment Review №354. AI lends a hand to the bulls
Corporate News in Focus of Our Analysts
Adobe
Adobe (ADBE) posted a headline-strong Q3 FY26: revenue and EPS beat guidance and consensus, and management again raised the full-year outlook. However, growth quality continues to erode. The freemium bet is working at the funnel level, with MAUs topping 1bn and AI-related ARR growing at an exponential pace. Monetization, however, is lagging: net-new ARR slowed sharply, RPO declined sequentially, and organic ARR growth is now in single digits. Margins are compressing under higher AI compute costs, and a meaningful share of EPS growth reflects buybacks. Management reaffirmed its ARR growth target but gave no timeline for reinstating deferred price increases. The appointment of Anil Chakravarthy as CEO reduces leadership uncertainty, though the CFO role remains vacant. The burden of proof has shifted from funnel growth to monetization, which is advancing slowly across the software sector.
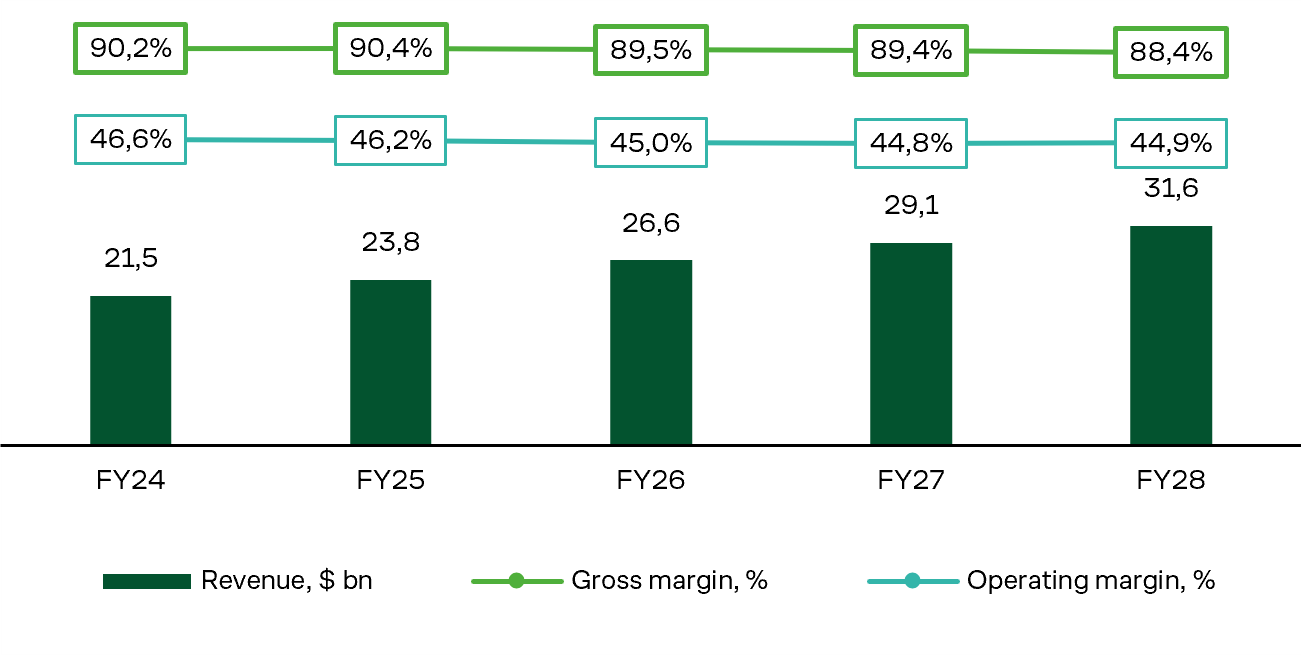
Key Financial Metrics for Adobe, Inc. (ADBE).
Sources: FactSet, Adobe, Freedom Broker
Oracle
Q1 FY27 was the quarter Oracle's (ORCL) AI build-out moved beyond a leap of faith, though reported results were slightly softer than expected. Order backlog beat expectations, and infrastructure revenue more than doubled. For the first time since the project’s launch, the financing position improved, giving investors some relief. However, new contract volume declined, and the guidance raise was far smaller than last quarter’s beat. Gross margin compressed more than anticipated, but operating margin held roughly flat on lower OpEx. EPS growth was aided by a lower tax rate and higher other income, including contributions from the Anthropic investment. Oracle is steadily converting new data-center capacity into revenue while renewing long-term leases on older GPUs at premium pricing. Management plans to address remaining investor questions at October’s Investor Day.
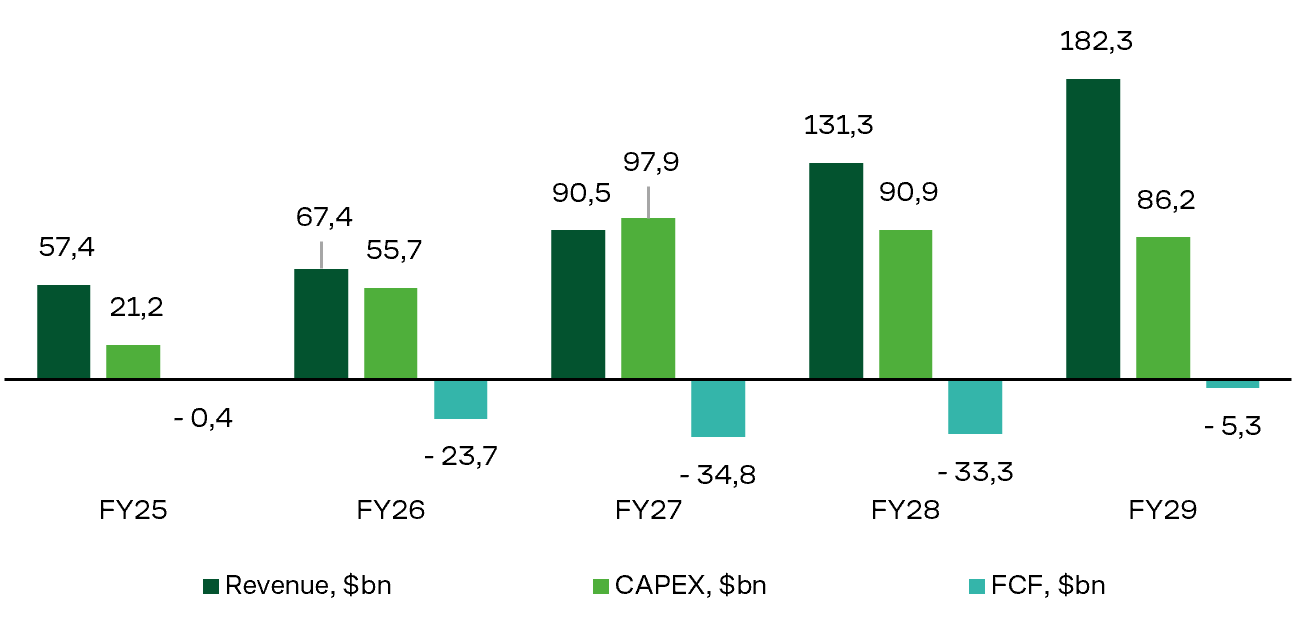
Key Financial Metrics for Oracle Corp. (ORCL).
Sources: FactSet, Oracle, Freedom Broker
Duke Energy, Southern Company, American Electric Power
On September 14, the U.S. Environmental Protection Agency finalized the repeal of most 2024 CO2 emissions standards for power plants and opened the remaining provisions for public comment. The action relaxes requirements premised on carbon capture and storage, expanding the runway for continued coal operations and new natural-gas generation. We view this as potentially positive for Duke Energy (DUK), Southern Company (SO), and American Electric Power (AEP): lower need for expensive retrofits lowers the risk of premature plant retirements and increases flexibility in capital planning. With data-center-driven load growth, preserving existing capacity should also help serve incremental demand. That said, the earnings impact is limited by the regulated business model: cost savings are reflected in rates, and reduced capex could temper rate-base growth.
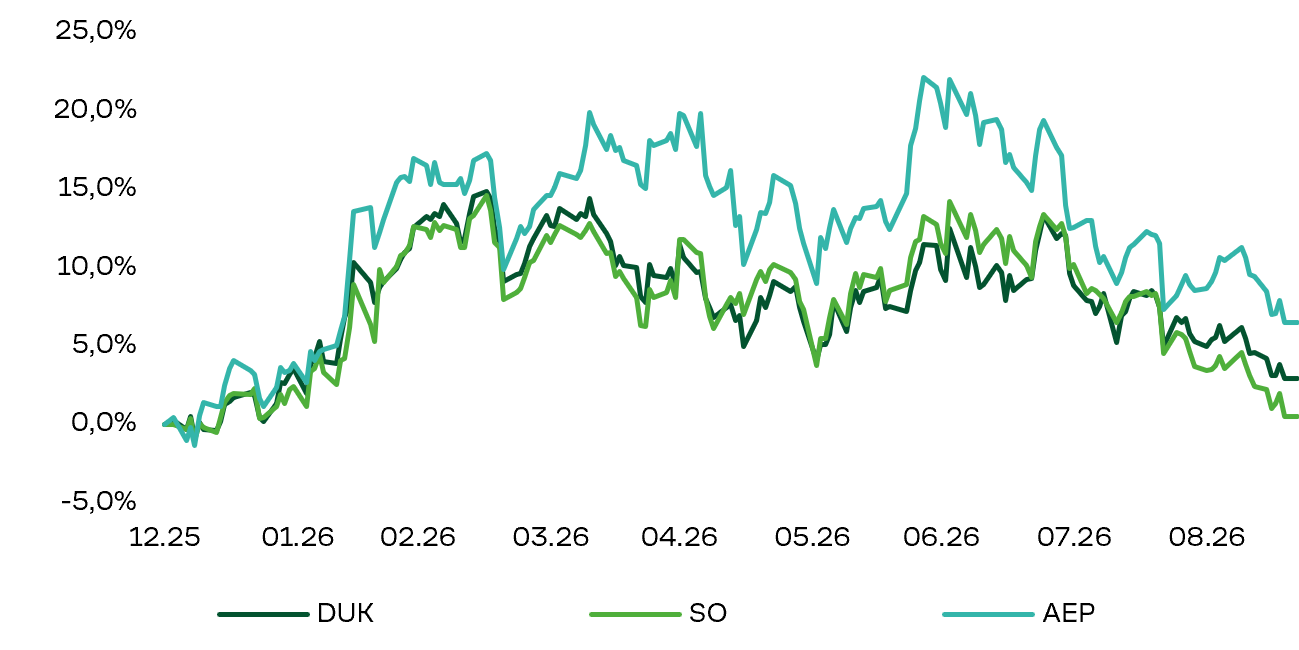
Total return on DUK, SO, and AEP.
Sources: FactSet, Анализ Freedom Broker
Coinbase
On September 15, the U.S. Senate failed to advance the CLARITY Act. In a procedural vote, the bill drew only 49 votes in favor, short of the 60 needed to proceed, pushing out prospects for a comprehensive statutory framework for crypto. No Democrats supported the measure; a key sticking point was language on ethics rules governing public officials’ crypto holdings. The bill remains technically alive, but with November midterm elections approaching, the odds of passage in 2026 appear remote. The market reaction was sharp but brief. On the day of the vote, Bitcoin fell nearly 4% to $75,500, and spot BTC ETFs saw roughly $450m of net outflows, with crypto-exposed equities among the main laggards. By September 18, Bitcoin had already reclaimed $80,000 and ETF inflows had resumed. Investors are betting the SEC and CFTC will keep advancing oversight under existing authorities even without new legislation, though such actions are more vulnerable to reversal if there is a change in administration.
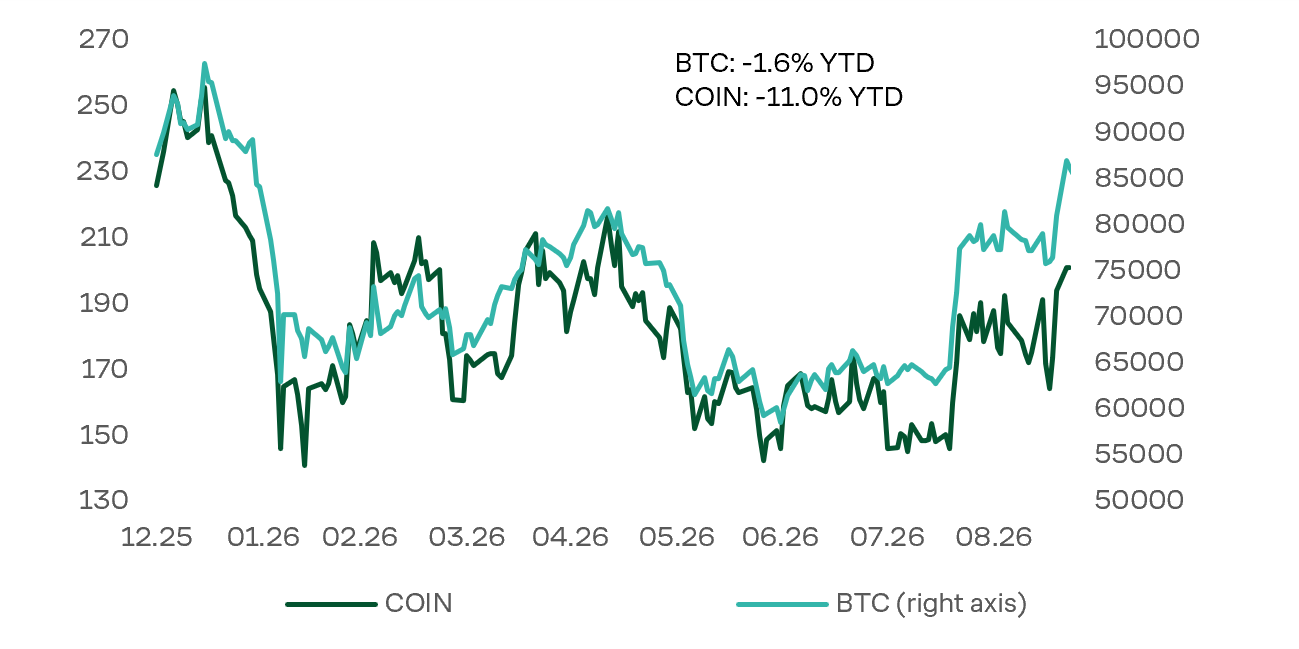
Year-to-date performance of Coinbase (COIN) and Bitcoin (BTC) shares, $.
Source: Bloomberg
Nucor, Steel Dynamics
Nucor (NUE) guided Q3 2026 EPS to $5.55–$5.65, with a midpoint of $5.60, up 113% YoY, below our prior $7.54 estimate and the $5.99–$6.20 consensus. Steel Dynamics (STLD) projects EPS of $5.34–$5.38, up 96% YoY, a smaller miss versus consensus. Steel and aluminum are driving growth, while scrap processing remains a headwind. STLD reports results on October 19, before Nucor on October 26. NUE shares fell 7% over two days, which appears excessive; STLD lost less than 2%. Nucor repurchased ~2.03m shares at $247.04, roughly twice its 2024–2025 buyback pace, bringing YTD shareholder returns to ~$1.36bn, or a ~2.2% yield. The stock trades below the average repurchase price, suggesting buyback support. Nucor has historically outperformed its EPS guidance, beating by an average of 13% since 2016. We lower our EPS estimates to $6.45 for Q3 and $20.55 for the year, still above the company’s guidance, supported by steel prices near $1,300/t, the highest since 2022.
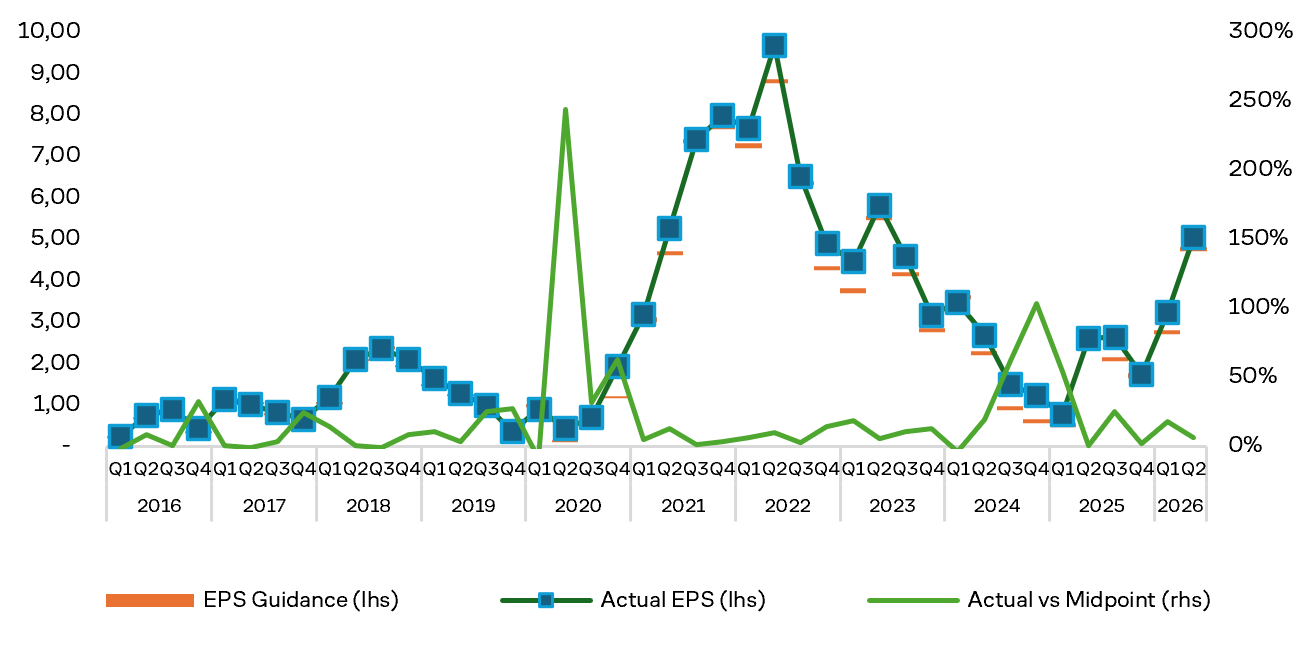
A comparison of actual EPS with Nucor's own guidance since 2016.
Source: FactSet