Investment Review №356. A Reassessment of Values
Vadim Merkulov
Director of the Analytical Department, Freedom Finance Global
Block. Comfortable Finance
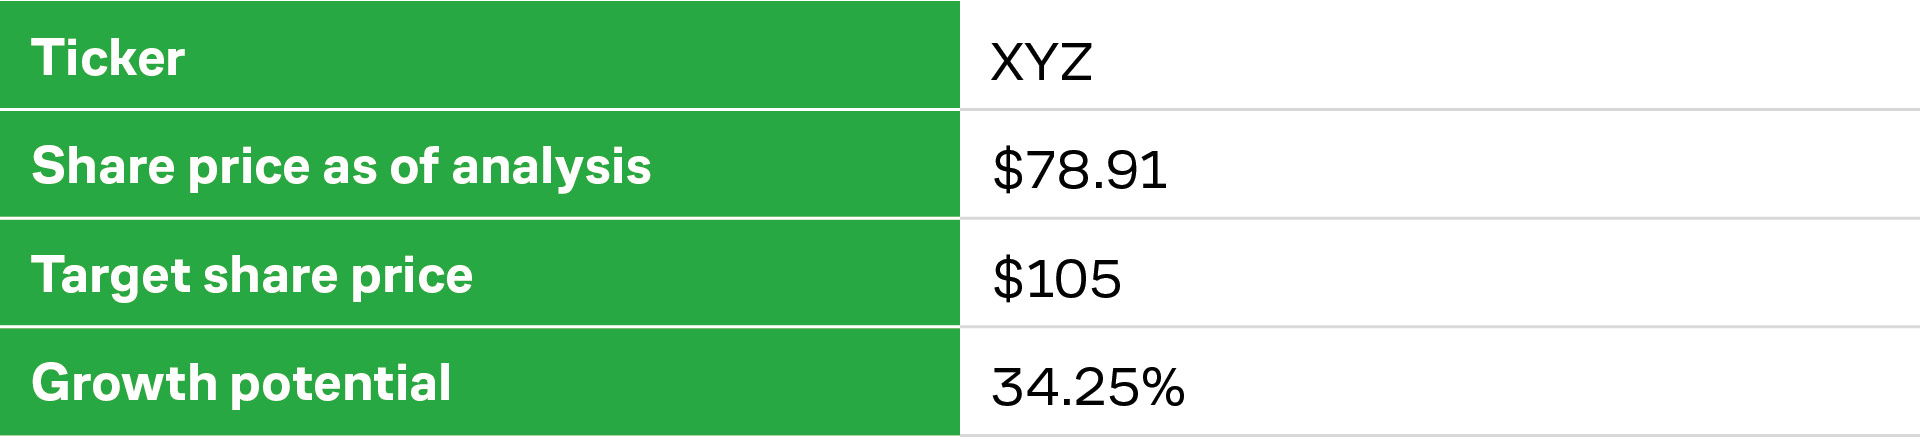
XYZ shares are attractive for investment with a $105 price target
About the Company
Block is a U.S.-based fintech company founded in 2009 that operates an ecosystem of financial and commerce services for businesses and consumers. Its two core segments are Square (payment, software, and financial solutions for merchants) and Cash App (a consumer financial platform). Square serves approximately 4 million merchants, while Cash App offers P2P transfers, debit cards, investing, lending, and BNPL services. As of the end of 2Q26, Cash App had 59 million monthly transacting active users.
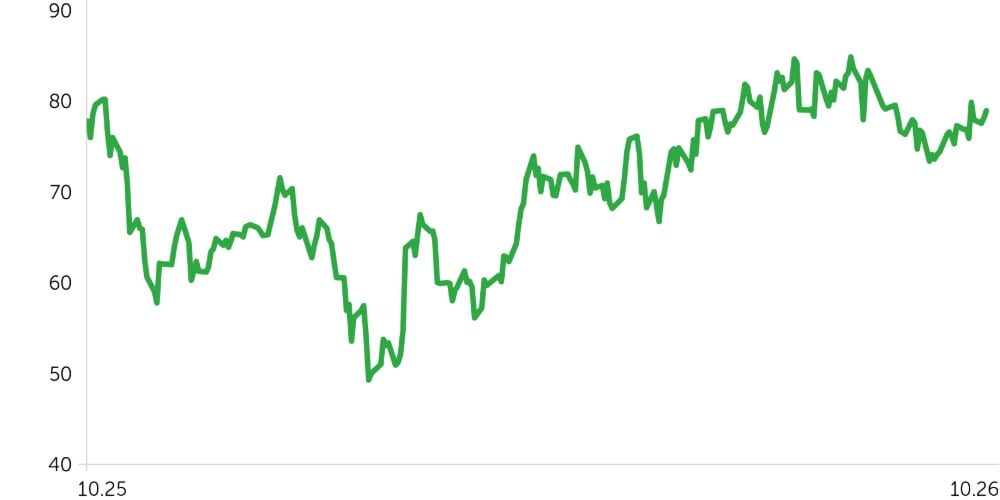
XYZ Share Price, $
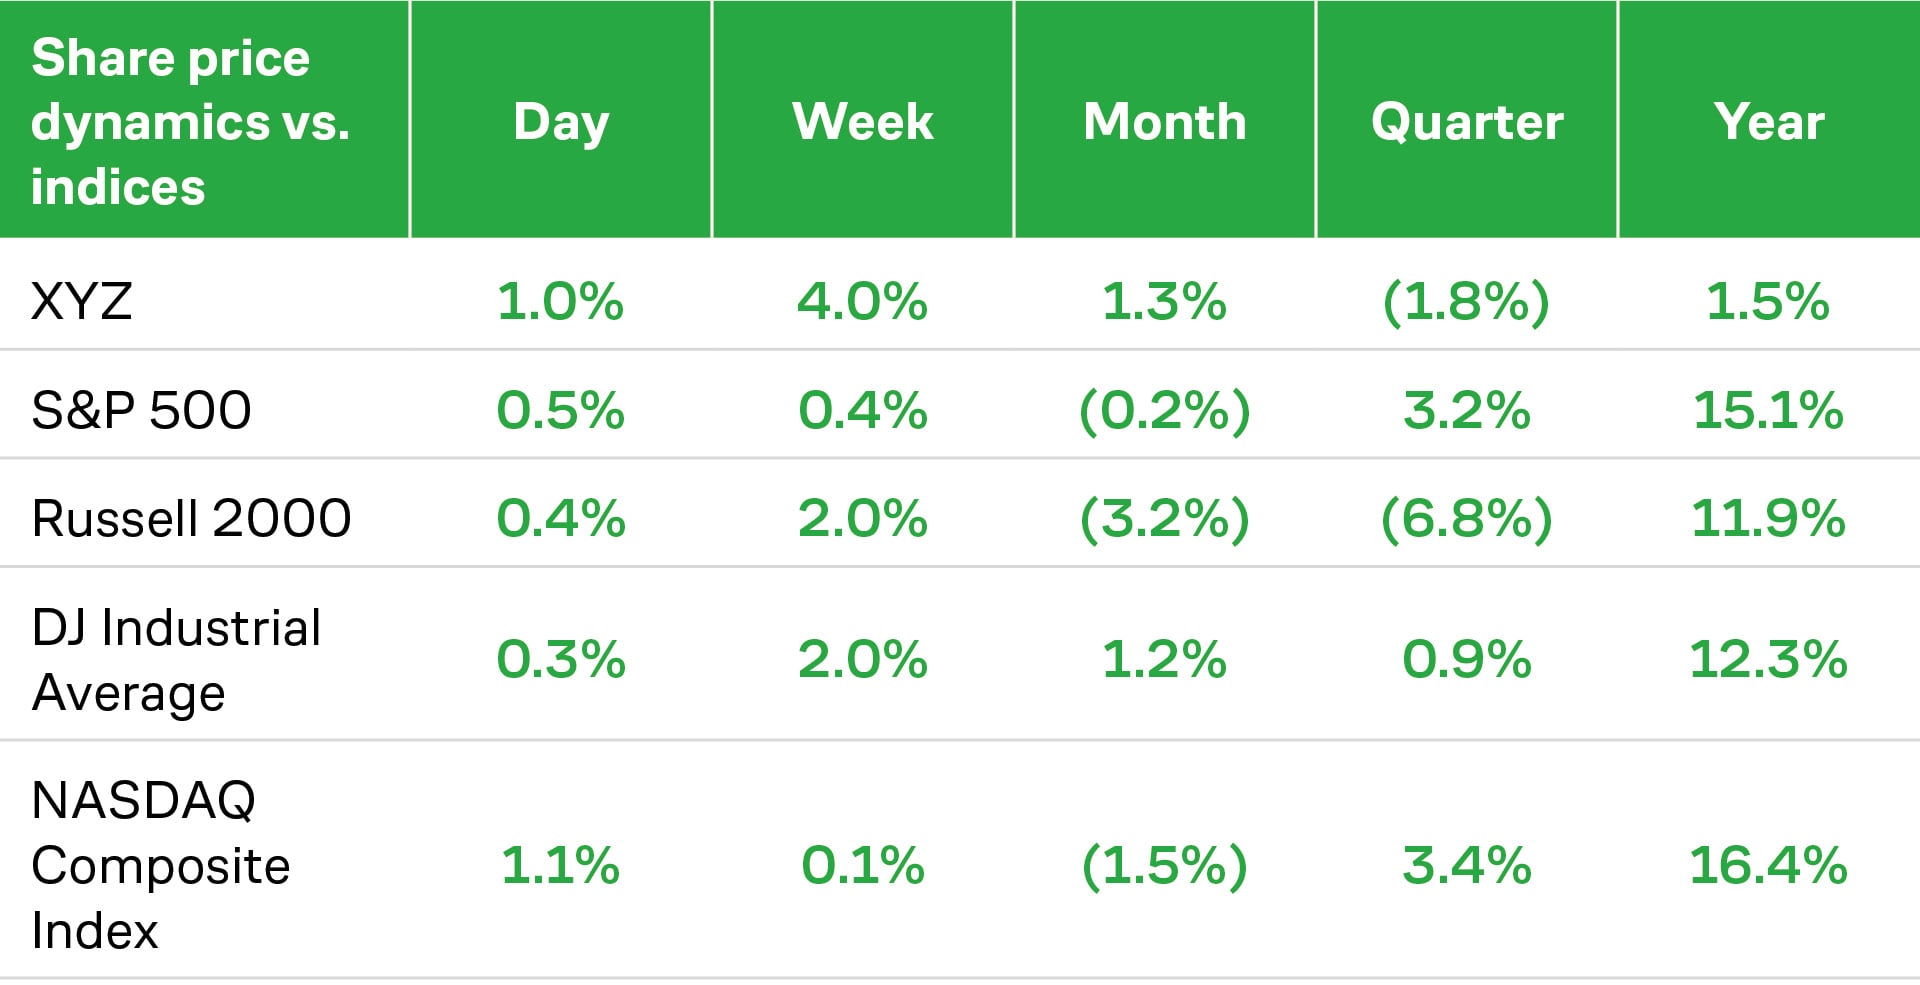
Key Investment Theses
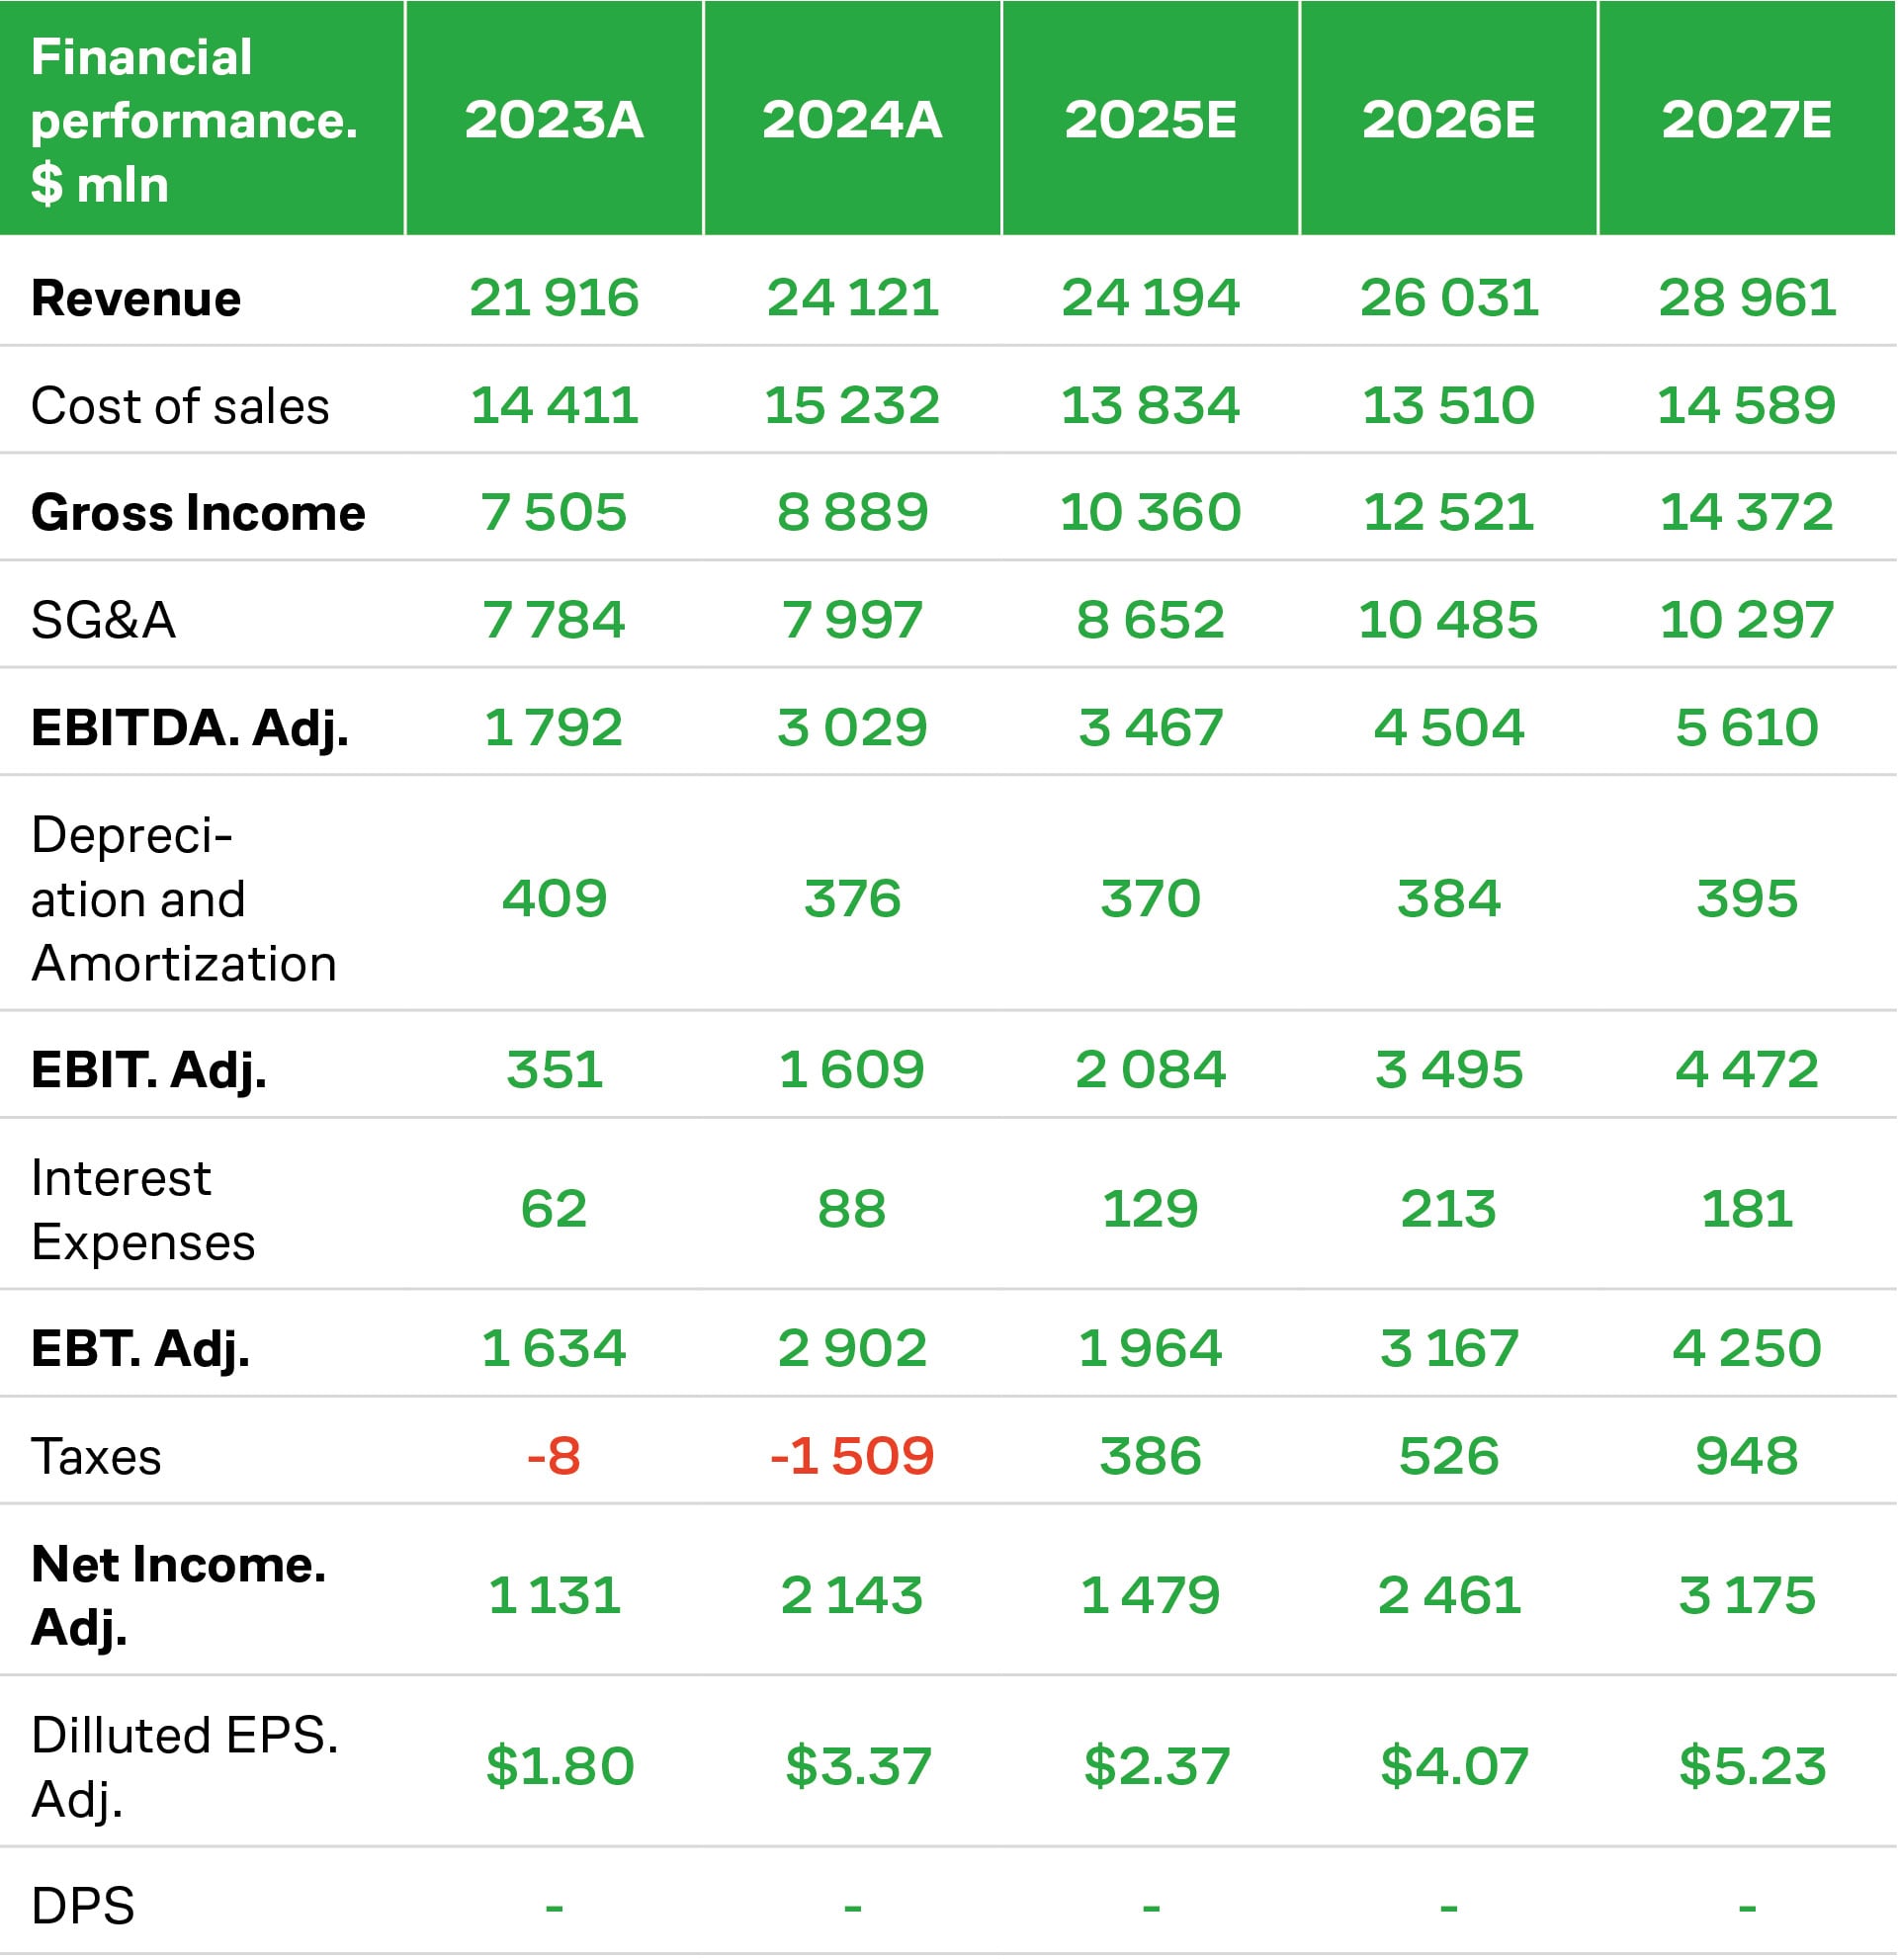
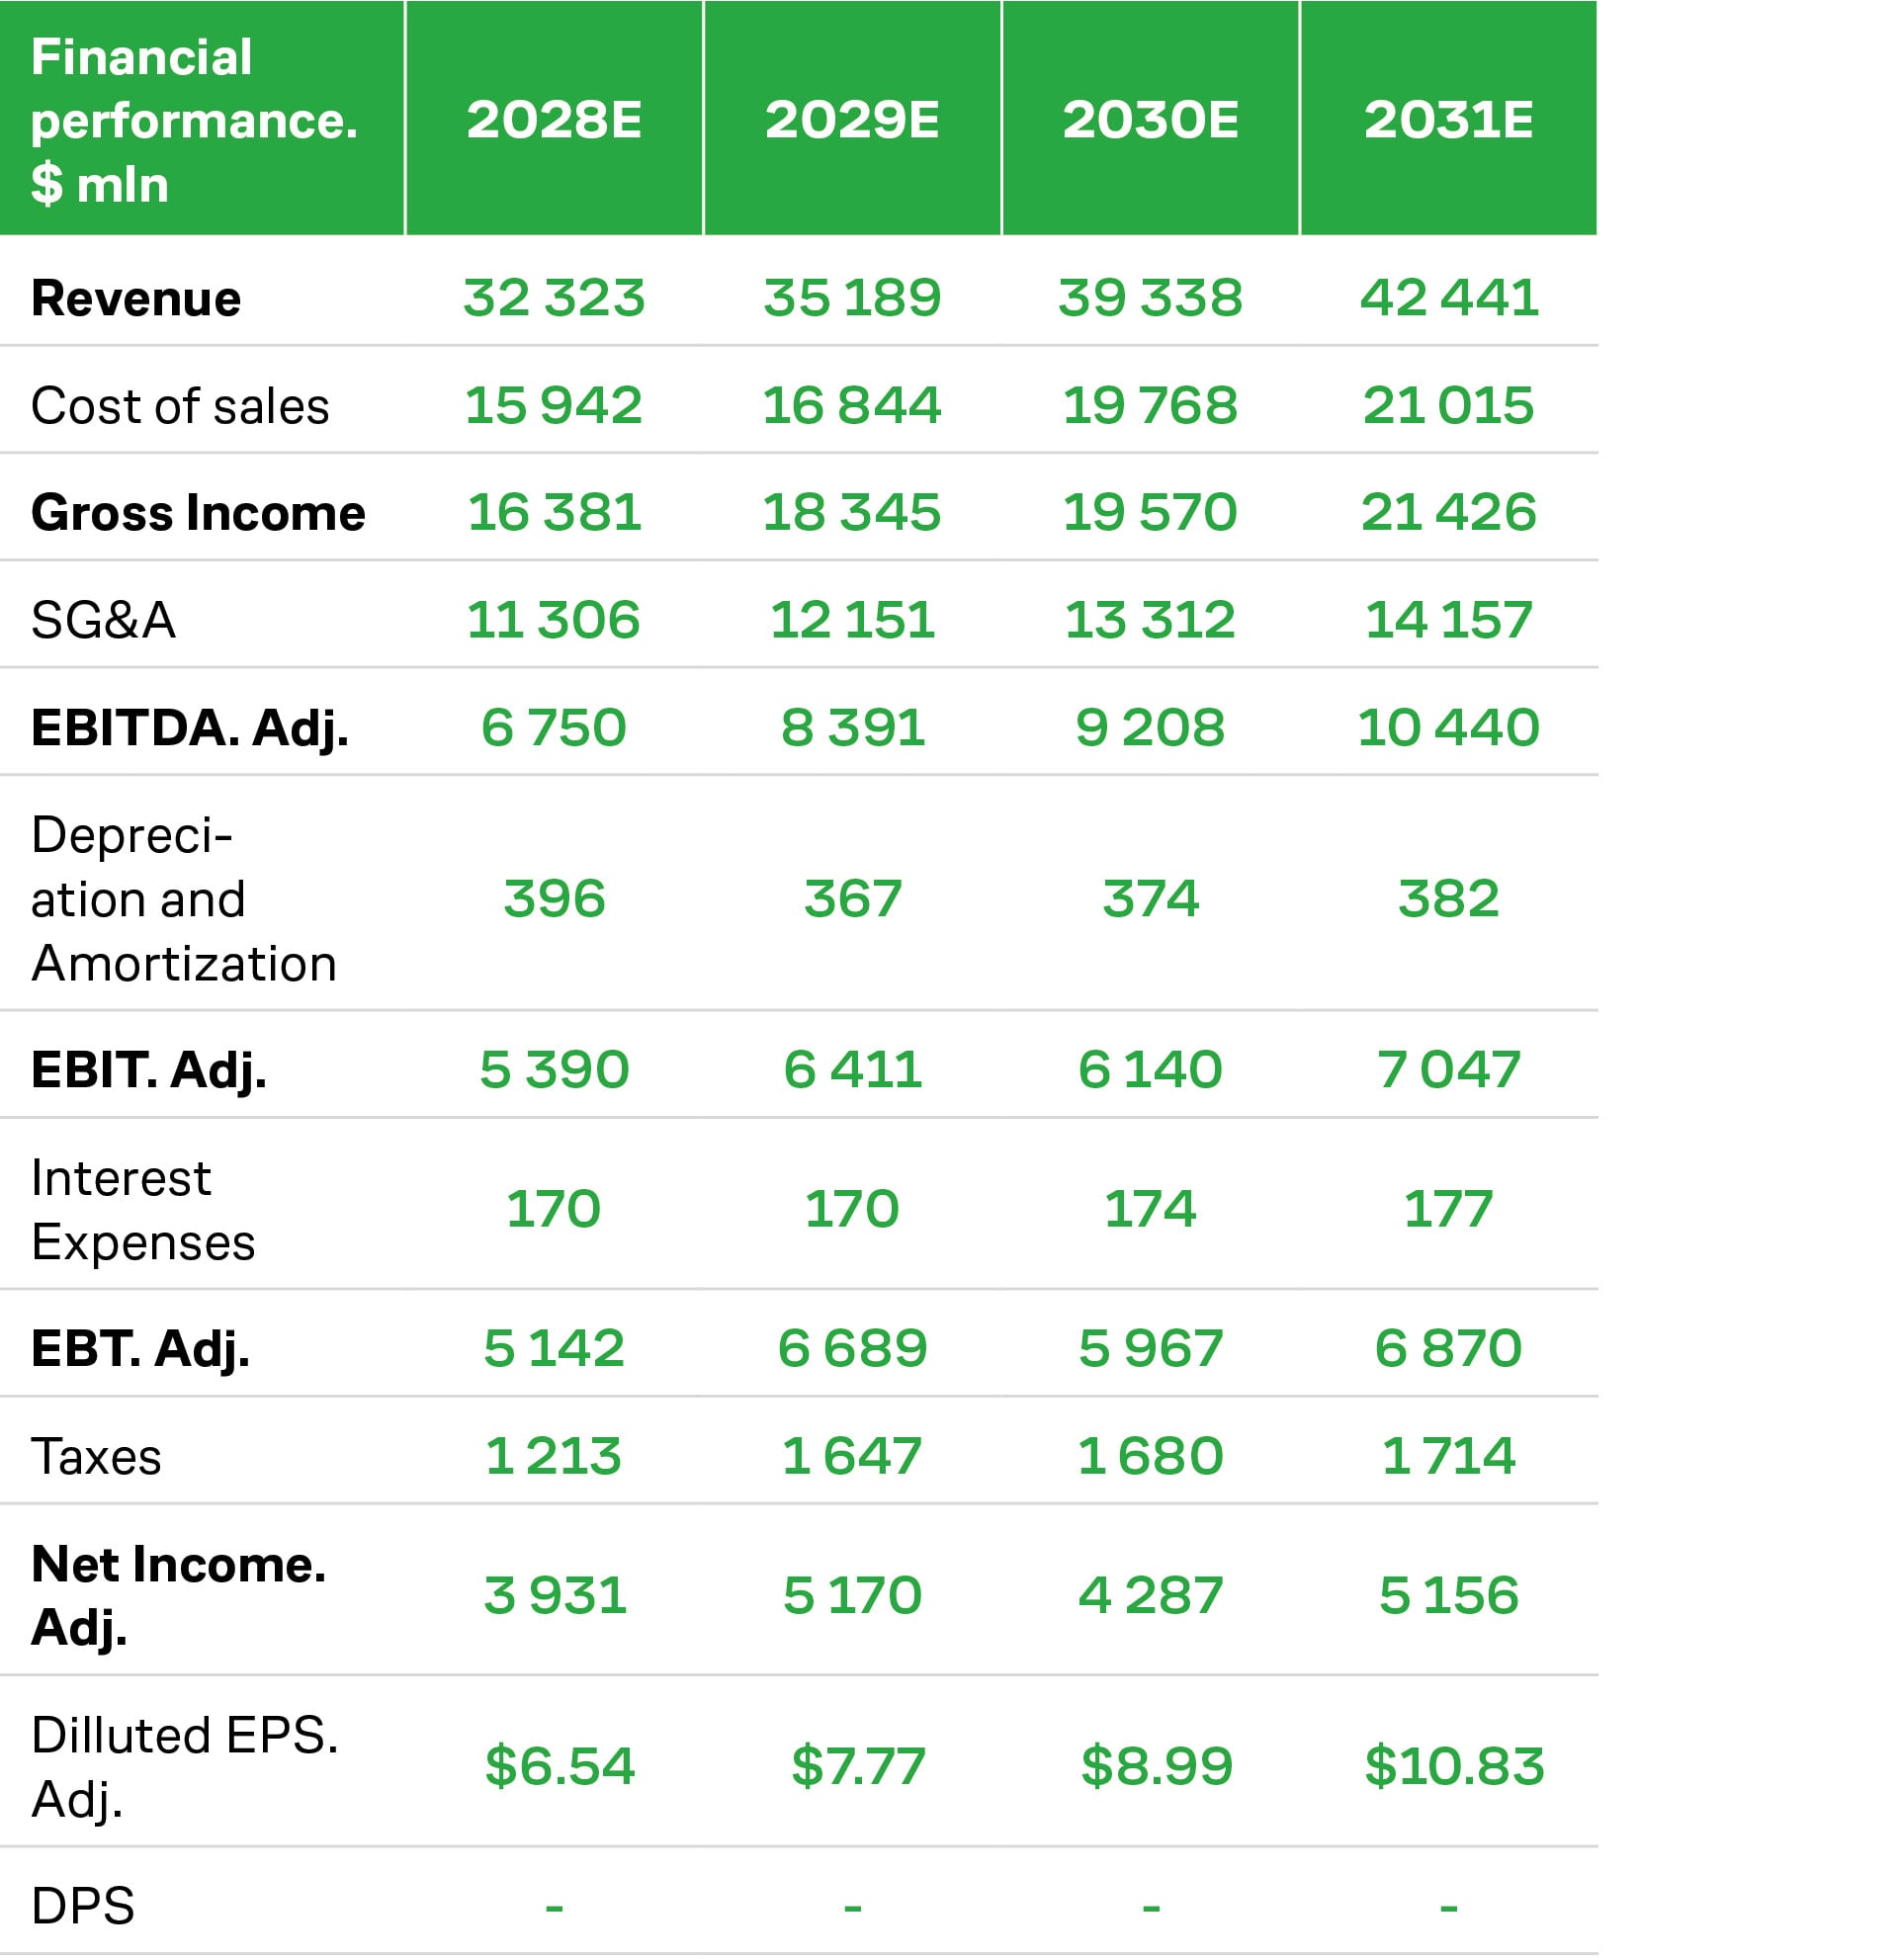
Square: Expanding distribution channels and enhanced restaurant solutions accelerate merchant acquisition. In 2Q26, Square's total gross payment volume (GPV) grew 13% YoY, with U.S. GPV growth accelerating to 10% (the fastest pace since 2Q23). Payment volumes increased 20% in the restaurant segment and more than 20% among mid-market merchants. The expansion of direct sales teams and independent sales organization (ISO) partnerships, alongside improvements in restaurant-specific software and hardware, is supporting merchant acquisition and strengthening Square's competitive position. Accelerating New Volume Added (NVA), a leading indicator of future GPV growth, suggests further upside to payment volumes. We expect sustained double-digit Square gross profit growth in 2027, driven by merchant acquisition and increased adoption of the platform's financial services.
Cash App: Lending growth normalizes as transaction-based monetization expands. In 2Q26, Cash App gross profit increased 31% YoY, while Cash App Card spending volumes grew more than 20%, significantly outpacing the broader U.S. debit card market. Additional monetization opportunities stem from expanding the Primary Banking Active (PBA) user base, which generates approximately $300 in annual revenue per user, compared with $20 for P2P-only users. The expansion of Cash App Green, integration of Afterpay with Cash App Card, and launch of Managed Accounts for children aged 6–12 should support user engagement and transaction-based revenue growth. Meanwhile, increasing Cash App Borrow fees from 5% to 7.5%, alongside extending loan terms from four to six weeks, could improve lending profitability. We expect lending growth to moderate and gross profit drivers to become more diversified, helping alleviate investor concerns over credit risk.
12-Month Price Target: $105
Stop-Loss: $45
Current Share Price: $77.50