
Freedom experts forecast LATAM Airlines bond yields of up to 8.5%
Stock Market News
30 September 2026, 19:59
Freedom Broker analysts maintained a “Hold for up to two years” recommendation on two LATAM Airlines Group (LTM) bond issues. The expected return over the holding period is 7.9% for the notes maturing in 2030 and 8.5% for the 2031 issue. The airline’s credit rating upgrade was a positive development; however, a significant portion of the improvement in its financial position is already reflected in bond prices.
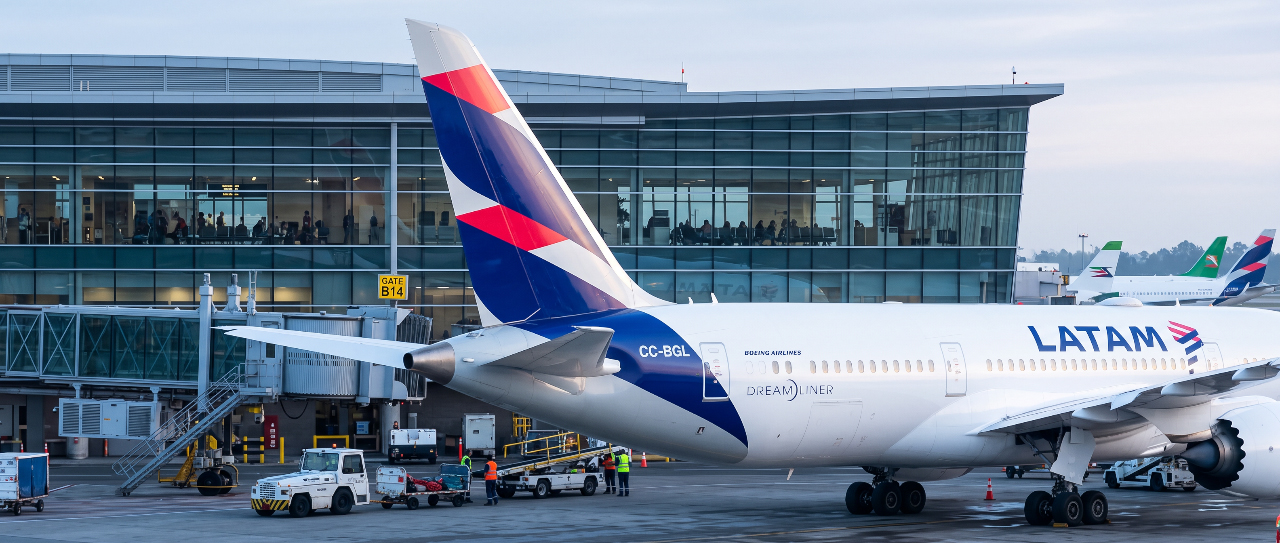
LATAM Airlines is a Latin American carrier
LATAM Airlines is Latin America’s largest aviation group, providing passenger and cargo transportation. The company operates in the region’s domestic markets and serves international routes.
The rating upgrade was a positive signal
On September 21, S&P Global Ratings (SPGI) upgraded LATAM Airlines’ long-term credit rating to BB+ from BB and revised the outlook to “Stable” from “Positive.” At the same time, the agency affirmed the BBB− ratings on the senior secured LTMCI 7.875’30 and LTMCI 7.625’31 issues.
S&P’s updated base-case scenario S&P assumes LATAM’s EBITDA will total about $4.3 bln in 2026. Positive free operating cash flow is expected at about $1.3 bln in 2026 and $1.9 bln in 2027.
The agency forecasts the adjusted debt-to-EBITDA ratio to remain in the 1.5–1.6x range in 2026–2028. Funds from operations before changes in working capital to gross debt should be around 50% and not fall below 45%.
S&P’s upgrade to BB+ is a positive credit event. However, current valuations of the issues already reflect a substantial portion of the improvement in the company’s fundamentals, Freedom Broker analysts note.
Analysts expect the further performance of the bonds to depend on the company’s ability to maintain profitability and positive cash flow amid fleet expansion and rising debt. Against this backdrop, analysts maintain a “Hold for up to two years” recommendation and estimate the issues’ return over the holding period at 7.9% and 8.5%.
The LTMCI 7.875’30 bonds, with a 7.875% coupon and maturity on April 15, 2030, are trading at an indicative price of 100.5% of par. Their yield to maturity and expected return over a two-year holding period are 7.9%.
The LTMCI 7.625’31 issue, with a 7.625% coupon and maturity on January 7, 2031, was priced at 99.8% of par. Its yield to maturity is 7.8%, while the expected return over the holding period is 8.5%. The minimum lot for both issues is $2k.
The BBB− rating corresponds to the lower boundary of investment grade on S&P’s scale. It indicates a lower credit risk for the bonds compared with the issuer’s own rating. This is explained by the secured status of the issues, which provides their holders with additional protection in an adverse scenario.
Fitch maintains LATAM’s rating at BB with a “Positive” outlook. According to Freedom Broker, a potential Fitch upgrade of LATAM to BB+ and the secured issues to BBB− would allow the notes to receive two investment-grade assessments. This could broaden the buyer base via funds and indices focused on investment-grade bonds, experts emphasize.
Revenue rose by nearly 30%
In the second quarter, LATAM’s revenue increased 28% year over year to $4.2 bln. Net income totaled $125 mln, and the operating margin was 5.4%. Passenger revenue rose 27.9% year over year. LATAM carried 21.1 mln passengers and increased total capacity by 8.9%. International capacity rose 11.8%, LATAM Airlines Brazil domestic capacity increased 5.7%, and operations of subsidiaries in Chile, Colombia, Ecuador, and Peru grew 5.3%. The load factor was 81.8%.
Fuel expenses rose by 93.1%
The main factor weighing on results was a near-doubling of jet fuel costs. In the second quarter, they reached $1.7 bln, up 93.1% year over year. The fuel price, including hedging, rose 81.3%.
Despite this surge, the company’s adjusted EBITDA amounted to $713 mln. In S&P’s calculations, EBITDA was $792 mln, down only 4.4% year over year. The difference is due to the specifics of how the metric is calculated by the company and the rating agency.
Analysts note that LATAM was able to pass a significant portion of the increase in fuel costs on through fares. A diversified model that includes the premium segment, cargo transportation, and a loyalty program helped the company maintain profitability amid a sharp rise in fuel prices.
Liquidity reached $4.2 bln
LATAM’s adjusted operating cash flow in the second quarter amounted to $473 mln. As of end-June, the company had $2.7 bln in cash, and total liquidity including available credit lines reached $4.2 bln, or 26.2% of revenue over the last 12 months.
Fleet expansion will increase financing needs
The company expects to increase capacity by 9–10% year over year and to deliver adjusted EBITDA in the range of $4.1–4.4 bln. Year-end liquidity should be at least $4.7 bln, and the adjusted net debt-to-EBITDA ratio should be no more than 1.6x.
At the same time, the airline is implementing a major investment program. S&P expects a net fleet increase of 69 aircraft by 2028 and gross debt including leases to rise by $3.5–4.0 bln in 2025–2028. Capital expenditures are projected at about $2.3 bln in 2026, $2.0 bln in 2027, and $2.6 bln in 2028.
In the second quarter, LATAM received nine aircraft, including two wide-body jets, bringing its fleet to 383 units. From November 2026 through March 2027, the company plans to introduce up to 14 Embraer E195-E2 aircraft. They will serve 42 routes, including four new destinations.
This is not an individual investment recommendation.