
Freedom Broker Initiates Coverage of IAMGOLD With a $23 Price Target
Stock Market News
9 October 2026, 12:21
Freedom Broker analysts have initiated coverage of Canadian gold miner IAMGOLD (IAG) with a “Buy” rating and a $23 price target. At the current price of $18.03, the upside potential is about 27.6%. The investment thesis is based on rising production and lower costs at the Côté Gold mine, reduced leverage, and the development of Canadian deposits. According to experts, the company is moving from costly construction to sustainable cash-flow generation.
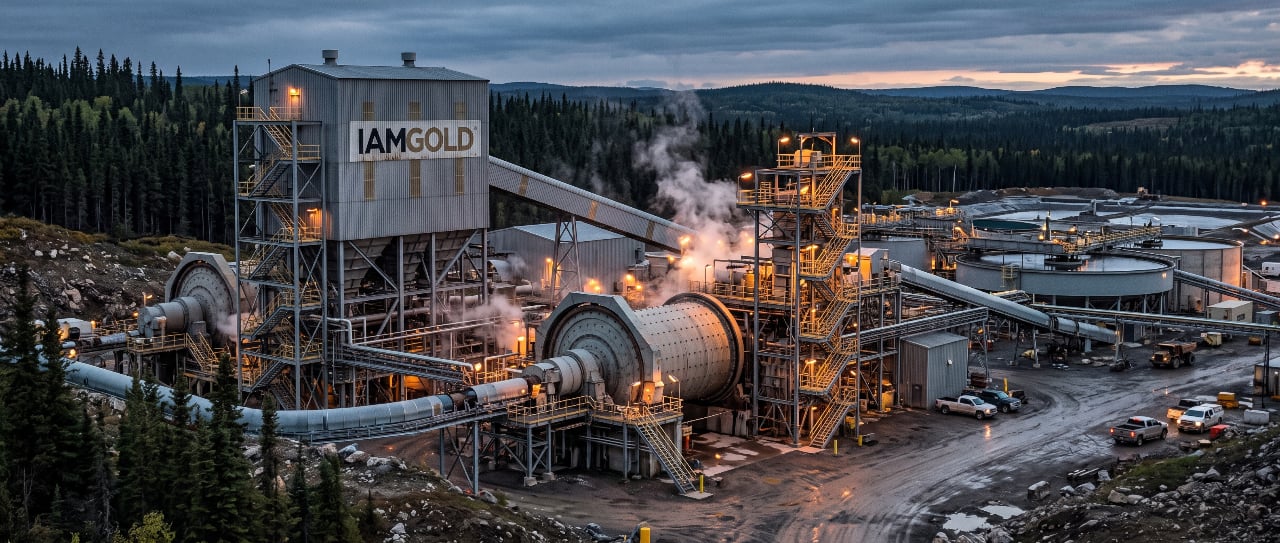
What IAMGOLD is
IAMGOLD operates three producing gold-mining assets: Côté Gold in Ontario, Canada; Westwood in Quebec; and Essakane in Burkina Faso. The company owns 70% of Côté, 100% of Westwood, and 85% of Essakane. In addition, it is developing the Nelligan project complex in Quebec.
Freedom Broker analysts believe the Canadian assets will play an increasingly significant role in the business. At the same time, Essakane remains an important source of funds for investments and share buybacks.
Côté should increase production and reduce costs
Experts cite Côté Gold as the key growth driver. In their forecast, the mine’s share of IAMGOLD’s attributable production, based on its ownership interests in the assets, will rise from about one-third in 2026 to more than 40% in 2027.
Bringing the operation to stable performance should allow costs to be spread over higher production volumes. Freedom Broker expects all-in sustaining costs (AISC) to fall by about 19%, from $2,041 per ounce in 2026 to $1,645 in 2027.
Côté’s free cash flow, according to analysts, could increase from $430 million in 2026 to more than $800 million annually in 2027–2028. These are funds remaining after operating expenses and capital expenditures that can be directed to business development or returned to shareholders.
Debt reduction expands financial flexibility
Another argument in favor of IAMGOLD, analysts say, is a stronger balance sheet. The company’s long-term debt fell from $1.1 billion in Q2 2025 to $449 million a year later. The company also fully repaid its revolving credit facility borrowings.
As of the end of June, cash totaled about $501 million, and available liquidity including the credit facility was roughly $1.35 billion. In Freedom Broker’s view, lower leverage reduces financial risks and allows a larger share of future cash flow to be allocated to investments and share buybacks. IAMGOLD does not pay regular dividends: buybacks remain the primary method of returning capital to shareholders.
Nelligan is the next stage of growth
Analysts link the long-term potential to the Nelligan complex. It combines several closely located deposits that could, over time, share common ore-processing infrastructure.
Freedom Broker values Nelligan at about $1.6 billion and includes this amount in its price-target calculation. However, the complex is not yet producing: additional studies, permits, and capital expenditures are required to advance it.
A separate opportunity is tied to the Gosselin deposit near Côté. Analysts are not yet including additional production and cash flow from it in their forecasts. More information is expected from an updated Côté mine plan, which is anticipated in Q4 2026.
What the price target is based on
Freedom Broker forecasts IAMGOLD’s revenue to increase from about $3.76 billion in 2026 to $4.26 billion in 2027. GAAP EPS, according to experts, is expected to rise from $2.24 to $2.97. To derive the $23 target, analysts valued the operating mines and Nelligan separately, then incorporated cash, debt, and lease liabilities. The valuation of operating assets is based on forecast 2027 adjusted EBITDA of around $2.6 billion and an EV/EBITDA multiple of about 4.6x—the ratio of enterprise value to this earnings metric.
In experts’ view, the upside potential is primarily tied to achieving the projected financial results and recognition of the value of Nelligan’s resources.
What risks could derail the forecast
The investment thesis depends on gold prices and mine performance. Freedom Broker’s assumptions include a gold price of $4,900 per ounce in 2027 and $5,000 in the long term. A sustained decline could materially reduce the company’s profit and cash flow. Other risks include delays in bringing Côté to stable throughput, rising fuel and materials costs, and changes in operating conditions in Burkina Faso. For Nelligan, uncertainty remains regarding timelines, development costs, and permitting.
Analysts emphasize that IAMGOLD shares provide exposure to the gold-mining business, but performance depends not only on the metal price, but also on production costs and execution of the company’s plans.
Company’s latest results
In Q2 2026 IAMGOLD increased revenue to $856.9 million versus $580.9 million a year earlier. Net earnings attributable to shareholders rose from $78.7 million to $230.5 million, and adjusted EBITDA increased from $276.4 million to $507.3 million.
Attributable production totaled 188.1 thousand ounces. The company maintained its annual guidance of 720–820 thousand ounces and expects higher Côté output in the second half of the year.
Not an individual investment recommendation.