
Freedom: the risk of an aluminum shortage could support Alcoa shares with a $60 target
Stock Market News
13 октября 2026, 09:54
Freedom analysts recommend opening long positions in Alcoa Corporation (AA) shares with a target price of $60. Relative to the price of $42.37 at the time of analysis, the upside potential is 41.6%. Experts link the investment idea to risks of a reduction in global aluminum supply and the possibility of a short-term re-rating of the shares.
Details — in the biweekly review of the U.S. market from Freedom analysts.
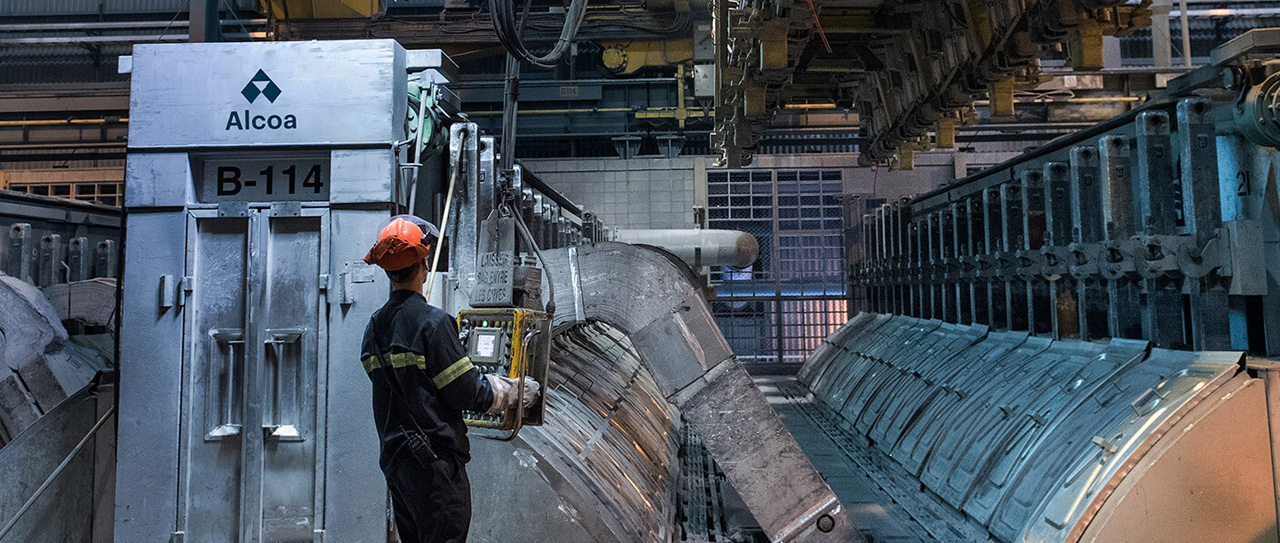
Alcoa is one of the world’s largest aluminum producers. The company operates at key stages of the production chain: from bauxite mining and alumina production to primary aluminum output.
A supply reduction could lead to higher prices
The main thesis of Freedom analysts is that a deterioration in the global aluminum balance could raise the metal’s price and regional premiums. According to experts, due to the conflict in the Middle East, annual aluminum production capacity cuts of more than 2.5 million tons were announced. Lost processing volumes were estimated at 2 million tons. A blockade of the Strait of Hormuz also complicates supplies of the raw materials needed for production.
For Alcoa, analysts view the transportation constraints primarily as a factor supporting aluminum prices rather than as a material operational risk. This underpins expectations of a possible short-term rise in the company’s shares.
Bauxite exports remain a source of uncertainty
An additional factor is a possible revision of Guinea’s export policy, as it is one of the world’s largest bauxite suppliers. Alcoa representatives previously noted that changes could affect the cost of raw materials and aluminum itself. According to Freedom’s estimate, rising transportation costs are already putting pressure on metal prices.
Another source of uncertainty for global supply is restrictions on Russian exports. At the same time, analysts believe the impact of these risks on Alcoa itself is limited.
The acquisition of South32 assets could improve unit costs
Experts also highlight the announced acquisition of South32’s aluminum assets for $4.1 bn. The deal covers bauxite mining, alumina production, and aluminum operations in Australia, Brazil, and South Africa.
According to Freedom analysts’ estimate, the expected synergy could deliver about $900 mln in net present value — the estimated value of future benefits adjusted for the timing of their receipt. The acquisition should deepen Alcoa’s production integration, expand its geographic footprint, and improve the company’s cost position.
Freedom previously recommended buying Alcoa shares
In August, Freedom Broker analysts recommended opening a long position in Alcoa with a target price of $60 over a two-month horizon and a stop-loss of $43. At that time, at a price of $51.01, the upside potential was 17.62%. Experts also linked the idea to a possible rise in aluminum prices due to supply disruptions.
This assessment was preceded by strong reporting for Q2 2026: revenue increased from $3.018 bn to $3.966 bn year over year, net profit from $164 mln to $407 mln. Adjusted EBITDA rose 51% versus the previous quarter to $901 mln, driven by higher aluminum prices and increased shipments.
Not an individual investment recommendation.