
Freedom: improved profitability supports BioMarin valuation despite guidance cut
Stock Market News
5 November 2026, 19:43
Improving operating efficiency is becoming the key argument in favor of BioMarin Pharmaceutical (BMRN) shares, according to Freedom Broker analysts Ilya Zubkov and Boris Tolkachev. The company lowered its full-year guidance, and quarterly sales depended on the timing of large orders. At the same time, underlying profitability came in better than expected. The analysts maintained their “Buy” rating and a target price of $110 per share.
BioMarin develops and manufactures therapies for rare genetic diseases. Following the acquisition of Amicus Therapeutics, the company expanded its portfolio of drugs for inherited metabolic disorders. Another important focus area is therapy for diseases that affect bone growth in children.
Revenue rose, but delivery timing distorts the picture
According to the Q3 2026 results, BioMarin’s revenue increased 32% year over year to $1.025 billion. Growth was supported by products acquired with Amicus and higher sales from the existing portfolio.
Revenue from the metabolic disorders franchise reached $744 million, beating market consensus by about 1%. However, in Freedom’s view, the overall result masks uneven dynamics across individual products.
VIMIZIM sales benefited from the timing of international orders. PALYNZIQ and NAGLAZYME, by contrast, came in below expectations after a strong Q2. The analysts believe the shortfall in PALYNZIQ is largely related to shipment scheduling: the number of patients continued to grow.
VIMIZIM sales—the drug used to treat the rare inherited disease mucopolysaccharidosis type IVA—were supported by the timing of international orders. Sales of PALYNZIQ, intended to treat phenylketonuria, and NAGLAZYME, used for mucopolysaccharidosis type VI, by contrast, were below expectations after a strong Q2. The analysts believe the shortfall in PALYNZIQ is largely related to shipment scheduling: the number of patients continued to grow.
A delay in orders from one international customer and disruptions in the Middle East led to a cut in full-year revenue guidance for this segment to $2.675–2.750 billion from $2.725–2.775 billion.
Slowing VOXZOGO growth increases uncertainty
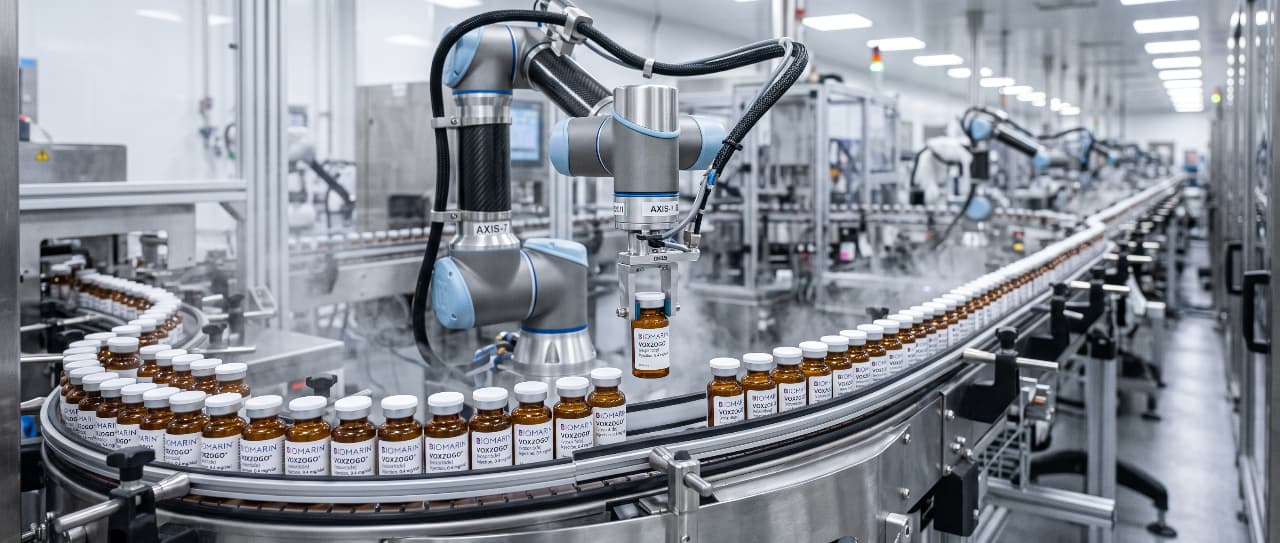
VOXZOGO revenue amounted to $245 million, up 12% year over year, but nearly 5% below consensus. The drug is used to increase growth in children with achondroplasia, a genetic bone development disorder.
Management explained the miss by the shift of a large international order into Q4. However, the number of patients increased 17% versus more than 20% in the previous quarter. Full-year VOXZOGO sales guidance was lowered to $975 million–1.025 billion, reversing the prior increase.
Freedom maintains a cautious view on the sustainability of the product’s growth. In addition to delivery timing, competition affects the outlook, and the company’s decision to stop disclosing metrics on patient switching to alternative therapy reduces transparency.
Opportunities to expand the market are linked to regulatory decisions in 2027. The FDA is reviewing an application for full approval of VOXZOGO for achondroplasia and an expansion into hypochondroplasia—another condition that impairs bone growth. Decisions are expected on February 28 and May 30, respectively.
Excluding acquired in-process spend, profitability is higher
BioMarin’s adjusted operating profit was $137 million, and operating margin was 13.4%. The figure exceeded consensus but came in below Freedom’s forecast.
The main reason for the divergence from the analysts’ estimate was about $288 million in expense for acquired in-process research and development, mainly related to the Alesta deal. These costs were not included in Freedom’s previous forecast.
Excluding them, operating margin, by the analysts’ calculations, would have been around 41.5%. This is an additional adjustment by Freedom, not a metric published by the company.
The business is benefiting from revenue growing faster than costs. Adjusted R&D expenses declined 4% year over year, while selling, general and administrative expenses increased 12% against revenue growth of 32%.
According to management, integration savings from Amicus are ahead of schedule. The company reaffirmed its target of about $220 million in annual benefits by 2028.
Why the recommendation remained unchanged
BioMarin lowered its 2026 adjusted earnings-per-share guidance to $2.80–3.10. It was impacted by acquired R&D expenses and revised revenue expectations.
Freedom also reduced its near-term financial estimates, but maintained a positive view of the company’s ability to improve profitability. The investment thesis now depends more on cost control and the integration of Amicus than on accelerating sales.
Previously, Freedom Broker had already noted BioMarin’s improving profitability after the Amicus acquisition. At that time, the analysts also warned that the upward revision to VOXZOGO guidance could reflect the schedule of international deliveries. The new results confirm the importance of both factors: operating efficiency is improving, while quarterly revenue remains volatile.
This is not an individual investment recommendation.