
Freedom experts: vVARDIS plans to raise $214 million in an IPO
Stock Market News
13 November 2026, 13:43
Swiss vVARDIS Holding AG, a developer of early-stage tooth decay treatments, is preparing to list on the New York Stock Exchange under the ticker VVVV. The company is offering about 9.52 million shares at $21–24. At the midpoint of the range, the IPO would raise $214.3 million and value the company at about $1.3 billion. Trading is expected to begin on November 13.
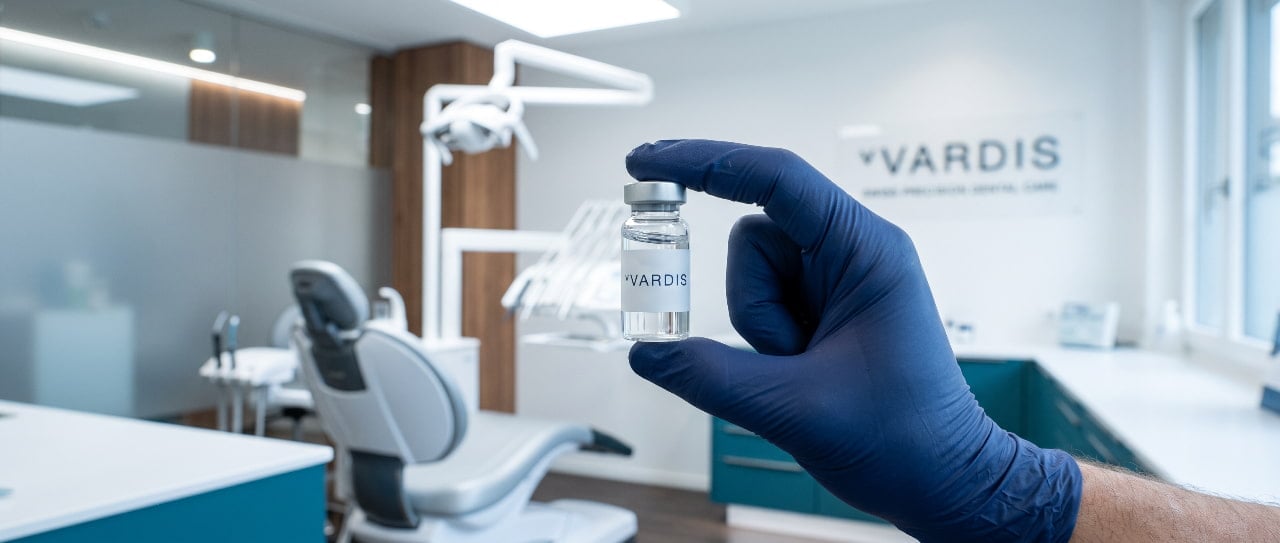
vVARDIS was founded in 2020 by dentist sisters Hailey and Goli Abivardi. The company is developing the Curodont line—peptide-based products that, according to its description, help halt the progression of early caries and restore damaged enamel. The product is used in the dental office: the procedure takes up to five minutes and requires no drilling or injections.
Offering terms
vVARDIS disclosed the parameters of the offering in an updated prospectus dated November 6. At $22.50 per share, the company expects to receive about $191.1 million after underwriter commissions and offering expenses. The proceeds are planned to be used for working capital, operating expenses, and capital expenditures.
Renaissance Capital puts the business valuation at roughly $1.3 billion at the midpoint of the price range. If the shares are priced at the top end of $24, the base offering size would reach about $228.6 million.
The IPO is being led by Goldman Sachs, J.P. Morgan, William Blair, UBS Investment Bank, and Deutsche Bank Securities. Trading on the NYSE is scheduled to begin on November 13.
Core market is U.S. dental clinics
The bulk of vVARDIS’s revenue comes from Curodont Repair Fluoride Plus, which is sold in the U.S. The company entered the U.S. market in January 2024. By the end of June 2026, more than 20,000 of the country’s roughly 110,000 general dental clinics had purchased its products.
By vVARDIS’s own estimate, by that time its products had been used to treat more than 3.5 million teeth. Shipments in the U.S. are made exclusively through distributor Henry Schein, while marketing is handled by the company’s in-house sales team.
The U.S. product is sold as an over-the-counter drug under an FDA monograph—a set of rules that allows compliant products to be brought to market without separate prior approval. This does not mean that the FDA has independently confirmed the safety and effectiveness of Curodont Repair Fluoride Plus itself.
The fluoride-free version, Curodont Repair, is sold as a medical device in the UK and some European countries. The products are intended for early stages of tooth decay; the company does not position them as a replacement for all types of traditional dental treatment.
Revenue is growing, the company remains unprofitable
In the first half of 2026, vVARDIS’s net revenue more than tripled—from $9.1 million to $28.6 million. Gross margin rose from 51.4% to 86.4%.
However, the company has not yet reached net profitability. The loss for the half-year totaled $27.8 million versus $32.1 million a year earlier. Rapid sales growth is accompanied by ongoing spending to develop the business.
For the 12 months through June 2026, revenue reached about $49.7 million, and net loss amounted to $52.2 million.
What matters for investors
vVARDIS’s outlook depends on further adoption of Curodont among dentists and repeat orders from clinics. At the same time, the business is largely concentrated in a single product and the U.S. market, where sales depend on a single distributor.
Another factor is the governance structure. According to the prospectus, after the IPO the founders will retain about 87% of voting power thanks to two classes of shares. This will allow them to determine key corporate decisions even after the company goes public.
Not an individual investment recommendation.