Investment Review №356. A Reassessment of Values

LONG CALL ON DIS

Options Idea

Trade Thesis

Buy the DIS 115 Call as a bet on further share-price recovery and a potential re-rating ahead of Disney’s November 17 earnings. Improving streaming profitability and strong Experiences results could support the FY2027 EPS outlook.

Key Arguments

  • Disney+ and Hulu are improving profitability; subscription price increases could lift ARPU if churn remains contained.
  • Experiences continues to grow revenue and operating income, supported by theme parks and cruise expansion.
  • A moderate forward P/E (~14–15x) and November 17 earnings offer room for a re-rating if guidance is strong.

Risk Management

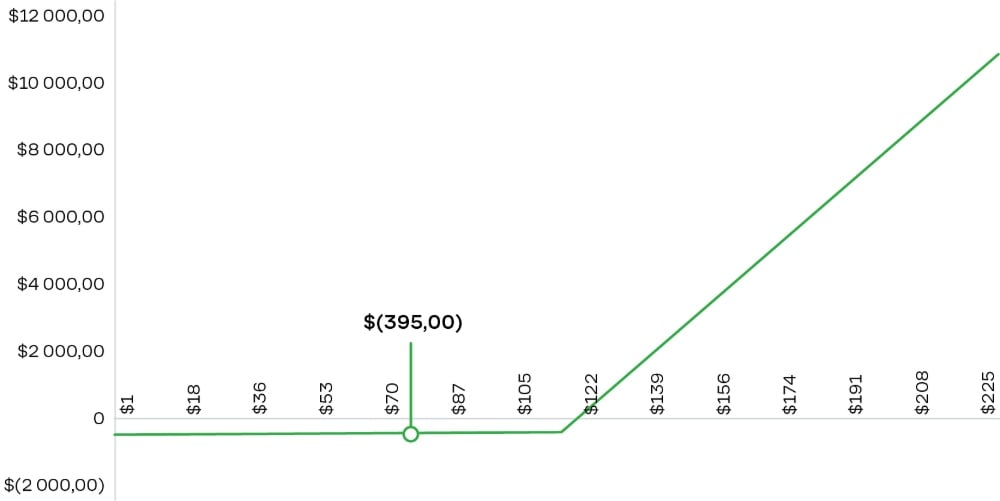
  • DIS < $115 at expiration: maximum loss of $395.
  • $115–118.95: partial loss.
  • DIS > $118.95: profit at expiration.
  • Target premium: $6.20 (+57.0%).

Risks: weak advertising demand, higher ESPN rights costs and subscriber churn after price increases. Disappointing November 17 earnings or a post-earnings IV decline could sharply reduce the option’s value.

Trade Parameters
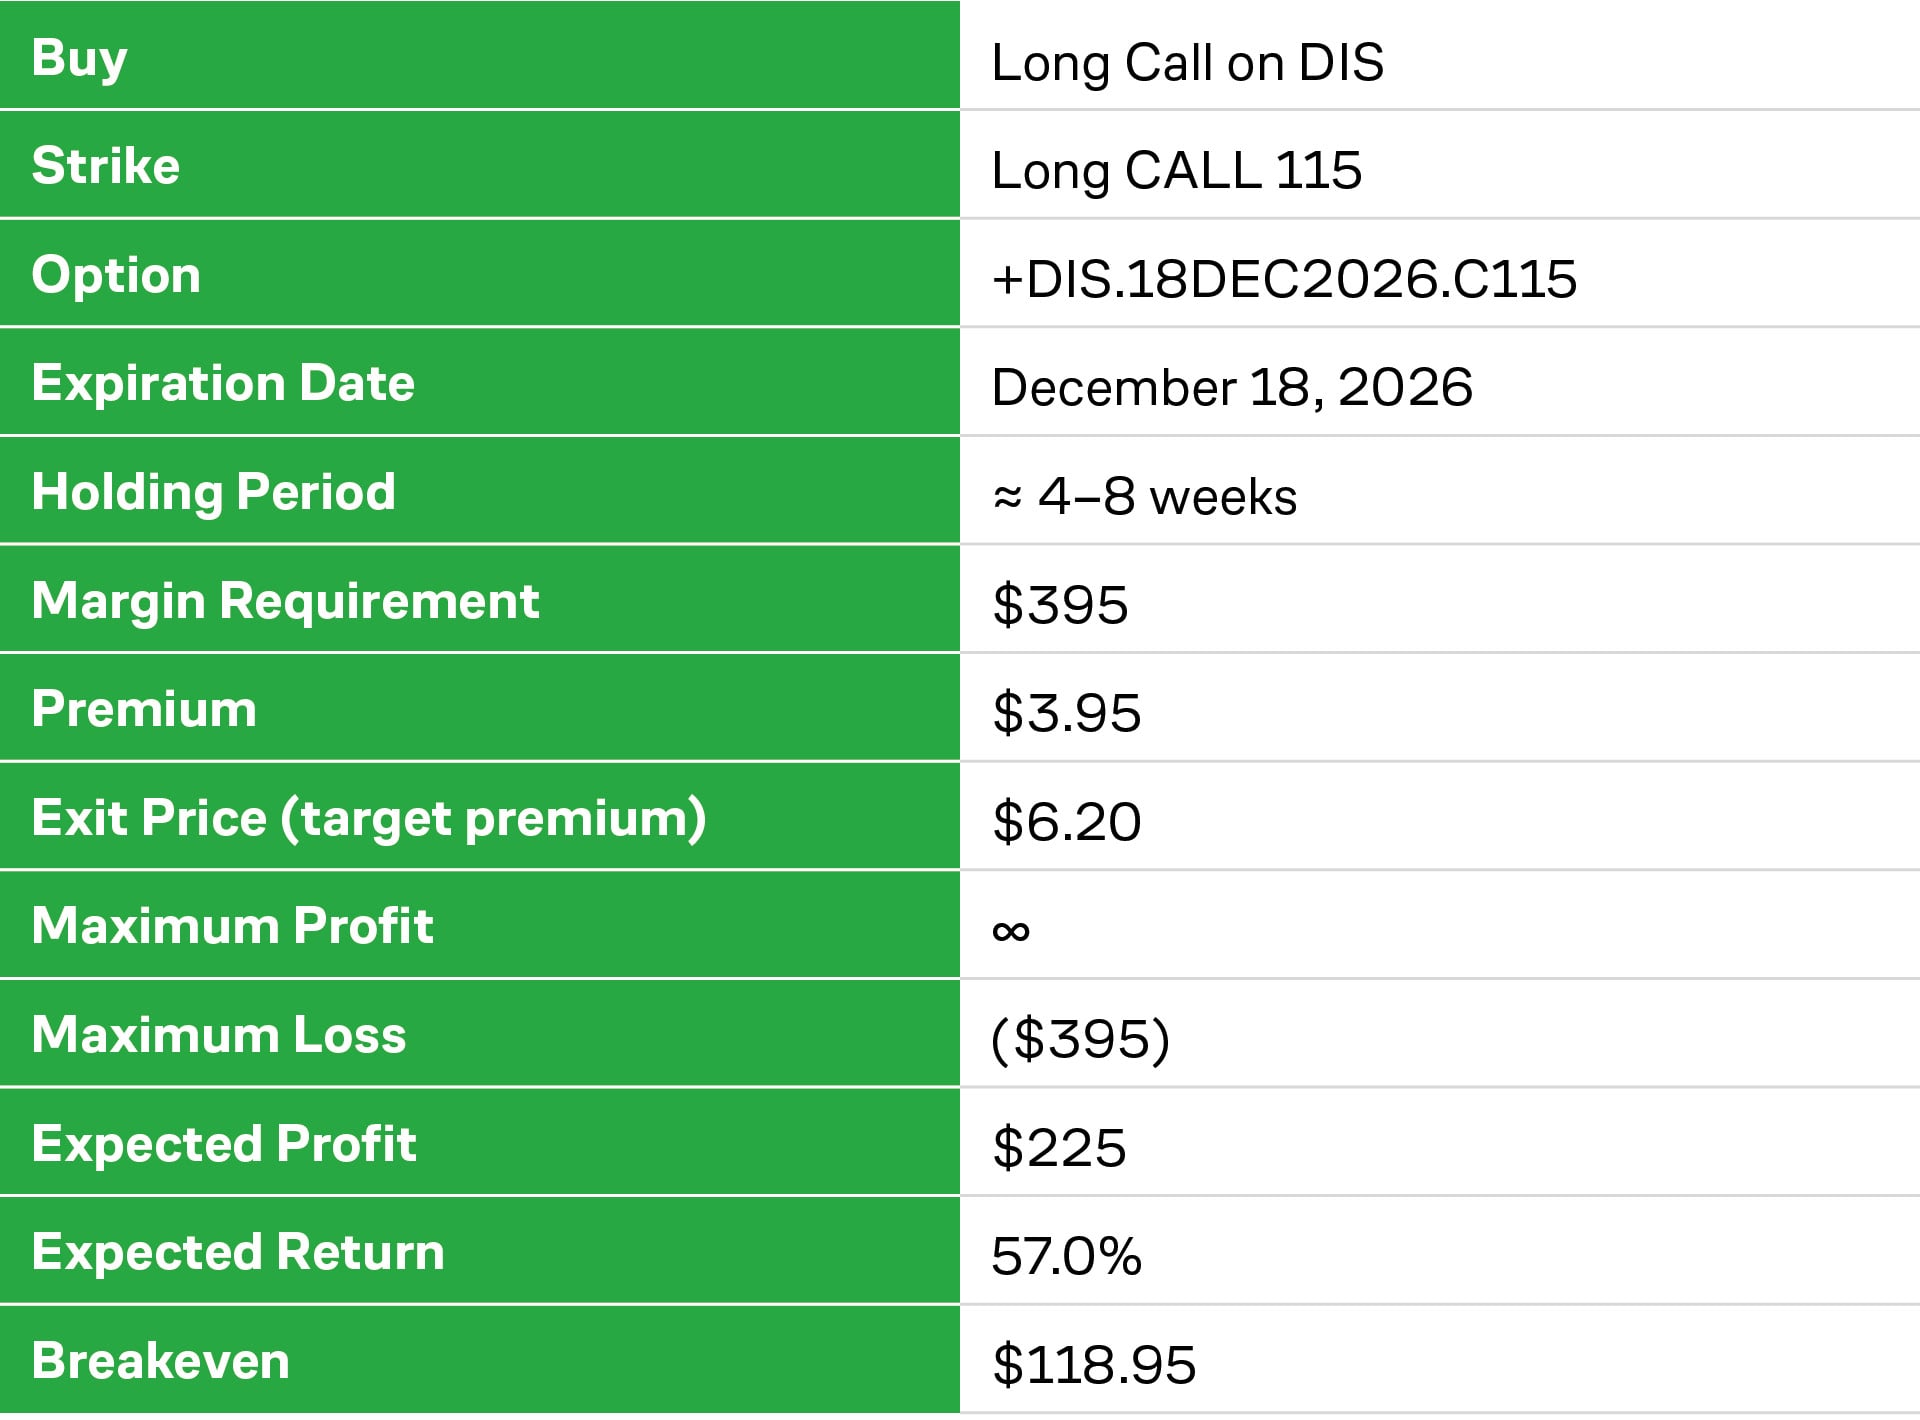
LONG CALL ON DIS. Trade parameters

Strategy Profit and Loss

LONG CALL ON DIS. Strategy profit and loss

16, Dostyk street, integral non-residential facility No.2, Yessil district Astana, Republic of Kazakhstan (Talan Towers Offices).

+7 7172 67 77 55 - Free from landline numbers in Kazakhstan; calls from international and mobile numbers are chargeable.

(+7 727 3557555 – additional)

7555 - free from mobile operators in Kazakhstan [email protected], [email protected]

Notify about fraudulent activities or security issues regarding this resource: fbroker.kz/trustcenter

Owning securities and other financial instruments is always associated with risks: the value of securities and other financial instruments can both rise and fall. Past investment results do not guarantee future income. In accordance with the law, the company does not guarantee or promise future returns on investments, nor does it provide guarantees regarding the reliability of potential investments or the stability of potential income.

Freedom Finance Global PLC provides brokerage (agency) services in the securities market on the territory of the Astana International Financial Center (hereinafter referred to as AFSA) in the Republic of Kazakhstan. Subject to compliance with requirements, conditions, restrictions and/or directions of the Acting Law of the AFSA, the Company is authorized to conduct the following Regulated Activities under License No. AFSA-A-LA-2020-0019: Dealing in Investments as Principal, Dealing in Investments as Agent, Managing Investments, Advising on Investments, Arranging Deals in Investments.

S&P Global ratings – “BB-”, outlook “Positive”.

Ownership of securities and other financial instruments always involves risks: the cost of securities and other financial instruments may rise or fall. Past investment results do not guarantee future returns. In accordance with the legislation, the company does not guarantee or promise the profitability of investments in the future, does not guarantee the reliability of possible investments and the stability of the amount of possible income.

The information on the website is updated as part of keeping the data up-to-date and meeting regulatory disclosure requirements. Please note that these updates are for informational purposes only and are not marketing materials!