
Freedom Broker analysts maintain a “Hold” recommendation on Tesla (TSLA) shares: a noticeable impact from robotaxis and robotics on the company’s financial results may emerge in the second half of 2027. The target price remains at $360, implying downside potential of 6.85% versus the $386.47 quote cited in the report. Adjusted profit for Q3 exceeded market expectations, but the timing for scaling new business lines remains uncertain.
What Tesla is
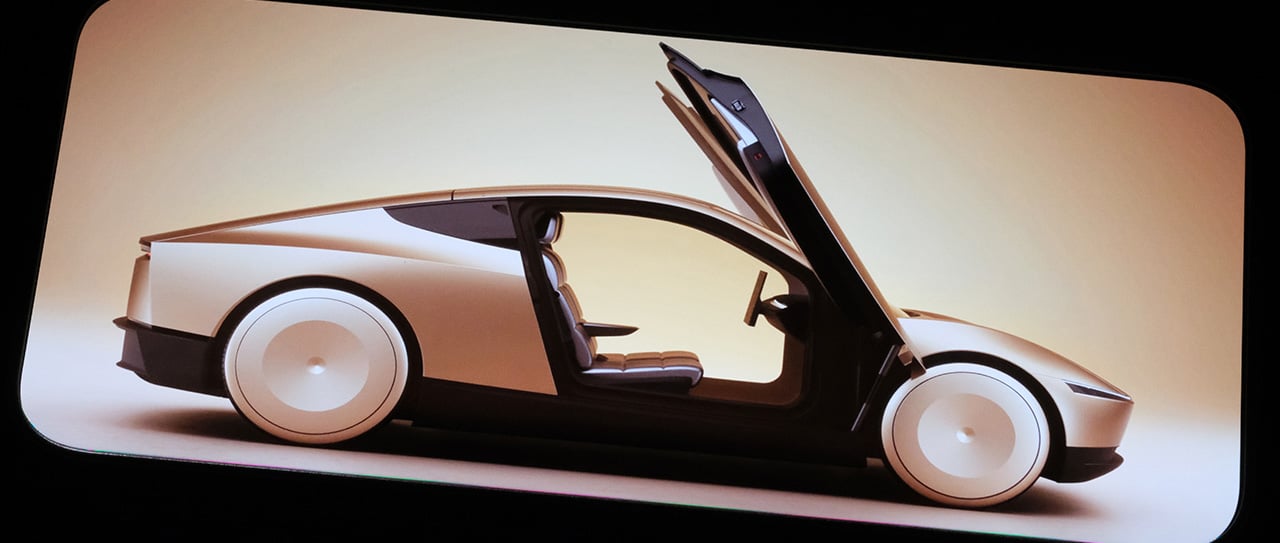
Tesla manufactures electric vehicles, solar equipment, and energy storage systems, and is also developing the FSD automated driving system, a robotaxi service, the autonomous Cybercab model, and humanoid Optimus robots.
For the company’s investment case, both the performance of the automotive business and the prospects for new products are important. In Freedom Broker’s view, management’s comments indicate that the transition from initial launches to large-scale commercial operations may require additional time.
New initiatives are not yet changing the financial picture
Analysts view Tesla’s Q3 report as neutral. The company kept revenue roughly at last year’s level, when EV buyer incentives were still in place in the U.S. and China. At the same time, the timelines for expanding new businesses may shift again.
At the end of the quarter, Tesla put Cybercab on the roads of Austin as part of its robotaxi service. Management expects to expand the geography of rides; however, in Freedom Broker’s assessment, the company still needs to address technological issues before more aggressive scaling. This could begin next year.
The number of active FSD subscribers reached 1.74 million, up 67% year over year. Tesla expects to obtain approval for the system across the entire European Union in the coming months. This is management’s expectation, not a regulatory decision that has already been made.
The company also reported the start of production of Tesla Semi trucks and the initial stage of Optimus output. According to Elon Musk, reaching production capacity of 1 million robots will require at least another year.
Revenue came in below Freedom Broker’s forecast
Tesla reported results on October 21 after the market close. Q3 revenue totaled $28.0 billion, down 0.2% from $28.1 billion a year earlier. The result was roughly in line with the FactSet consensus forecast of $28.1 billion, but below Freedom Broker’s expectation of $29.6 billion.
The core automotive segment reduced revenue by 3.0% year over year, to $20.6 billion. Analysts attribute the decline to lower deliveries and average selling prices.
Revenue in the solar equipment and energy storage segment fell 15.6%, to $2.9 billion. Services and other operations, by contrast, delivered growth of 32.5%, to $4.6 billion. In experts’ estimates, this line already significantly exceeds the energy segment in revenue and in the coming years may show the highest relative growth rates.
Profit beat expectations, but expenses weigh on margins
Tesla’s net profit amounted to $0.8 billion—42.7% less than a year earlier, but above Freedom Broker’s forecast of $0.6 billion. Adjusted net profit reached $1.70 billion versus the consensus forecast of $1.57 billion. Adjusted earnings per share were $0.48 compared with the FactSet expectation of $0.47.
Operating margin—the share of operating profit in revenue—increased to 2.6% from 1.4% in the prior quarter, but remained below last year’s 5.8%. Gross margin rose to 19.6% from 18.0% thanks to improved results in the services segment.
This was not enough to offset a 39% year-over-year increase in operating expenses. The main pressure came from research and development costs, which rose 69%. At the same time, management lowered its 2026 capital expenditure guidance from $25 billion to $20 billion.
Deliveries were supported by exports from China
In Q3, Tesla delivered 486.5 thousand EVs—2.1% less than a year earlier and 1.3% more than in the previous quarter. According to Kelley Blue Book estimates cited in the report, sales of new battery electric vehicles in the U.S. fell by about 39.5% year over year, while Tesla’s domestic deliveries may have declined by 19.7%. The more moderate drop allowed the company to increase its market share to 54.0% versus 50.5% in the prior quarter.
In China, Tesla’s wholesale deliveries fell 16.0% year over year, according to China Passenger Car Association data. At the same time, the Shanghai plant increased exports by 83.18%, to 132.9 thousand vehicles. The company also reported record deliveries in Canada, Australia, Japan, and Taiwan. Freedom Broker expects the high growth rates of deliveries of China-made vehicles to persist.
What results analysts expect
According to Freedom Broker’s forecast, Tesla’s revenue for full-year 2026 could total $106.0 billion, up 11.7% year over year. In 2027, analysts expect $115.1 billion. The Q4 revenue forecast is $27.3 billion, or 9.6% growth year over year. Experts slightly reduced this estimate due to a revision of expectations for the energy business.
The GAAP earnings-per-share forecast is $0.87 for 2026 and $0.92 for 2027. The $360 target price is calculated based on a five-year discounted cash flow model: it values the company’s future cash flows taking into account time and risk.
Previously, robotaxis were the main catalyst for the short-term idea
In September, Freedom Broker presented a separate “idea of the day” on Tesla with a “Buy” recommendation and a $425 target price on a two-month horizon. At the time, analysts highlighted the expansion of the robotaxi fleet and the possibility of exceeding market expectations for quarterly deliveries.
In the October post-earnings report, experts maintain the “Hold” recommendation and the $360 target price. The key question now is when the development of autonomous transport and robotics will begin to meaningfully show up in Tesla’s revenue and profit.
Not an individual investment recommendation.