Investment Review №357. A Change of Leadership
Vadim Merkulov
Director of the Analytical Department, Freedom Finance Global
CrowdStrike. A Multi-Layered Cybersecurity Service
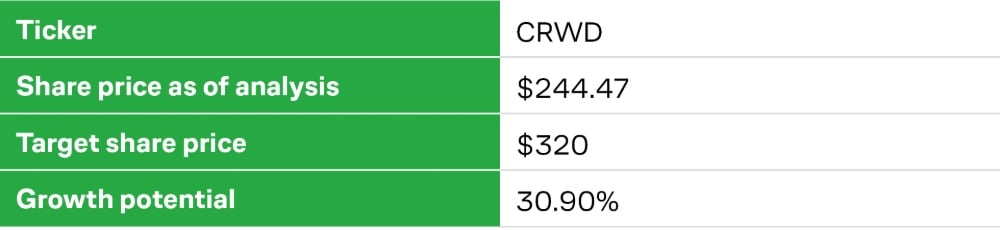
CRWD shares look attractive with a $320 price target
About the Company
CrowdStrike (CRWD) develops cybersecurity solutions. The company provides customers with Falcon, a cloud-based platform that protects servers, computers and mobile devices, and operates on a SaaS (software as a service) model.
The core investment thesis centers on an accelerated multiple re-rating driven by the company securing its status as the primary consolidator of enterprise cybersecurity budgets. Large-scale enterprise migrations toward a single platform and surging demand for AI infrastructure protection continue to fuel strong net new ARR additions and robust free cash flow expansion.
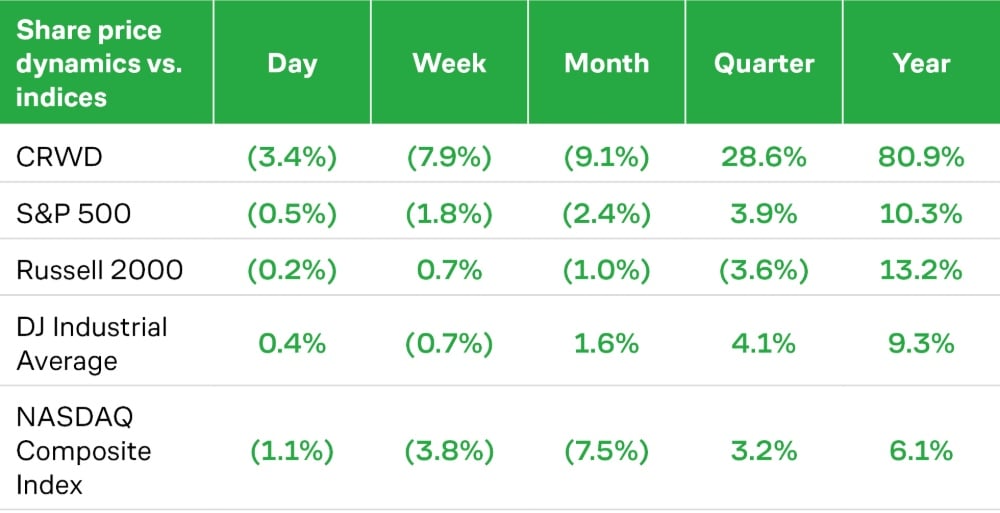
CRWD Share Price, $
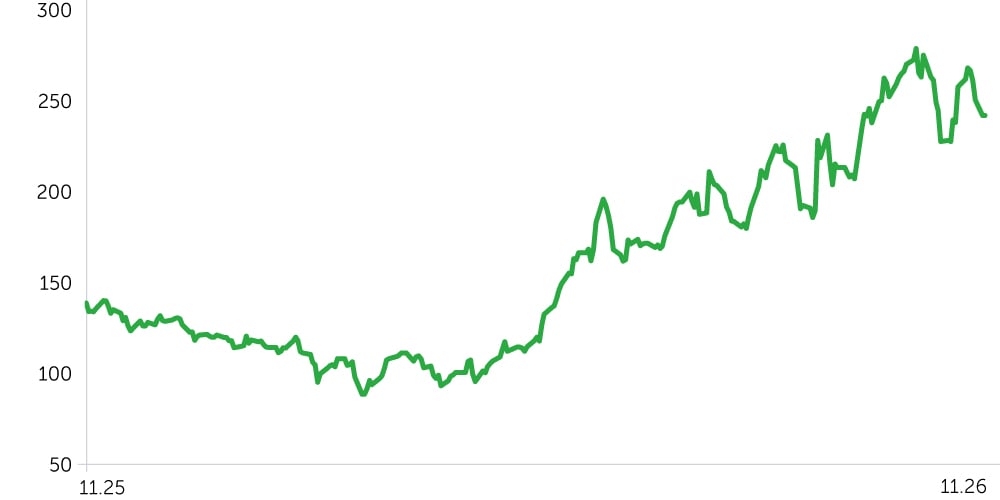
Key Investment Theses
Escalating threat sophistication drives enterprise migration to consolidated architectures. A surge in generative AI-enabled attacks alongside shrinking breakout times forces enterprise buyers away from fragmented point products in favor of unified ecosystems. CrowdStrike’s Falcon platform serves as the primary beneficiary of this platformization trend. The Falcon Flex licensing model has seen exponential adoption, allowing customers to deploy Cloud Security, Identity Protection, and Next-Gen SIEM modules seamlessly without procurement friction.
Securing enterprise AI workloads unlocks a massive incremental TAM. Deploying generative AI across corporate environments creates critical vulnerabilities across foundation models, training data pipelines, and orchestration layers. CrowdStrike’s specialized AI Detection & Response capabilities and Charlotte AI assistant transition the business from a traditional endpoint security player (EDR/XDR) into an essential control plane for enterprise LLMs and autonomous agent workflows. Monetization across these product lines outpaces initial consensus expectations and reinforces competitive moats against legacy IT vendors.
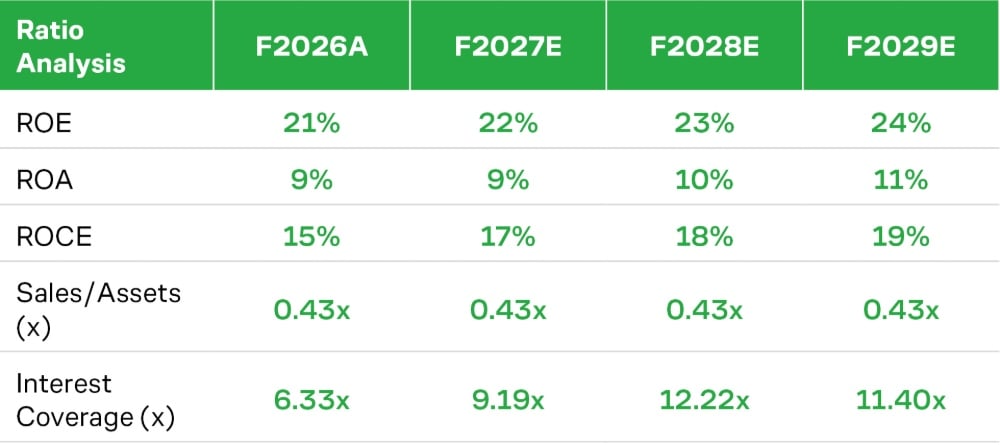
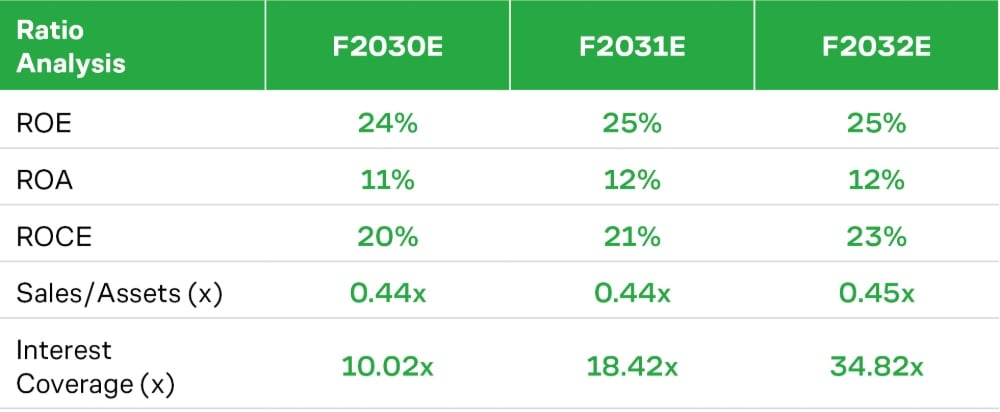
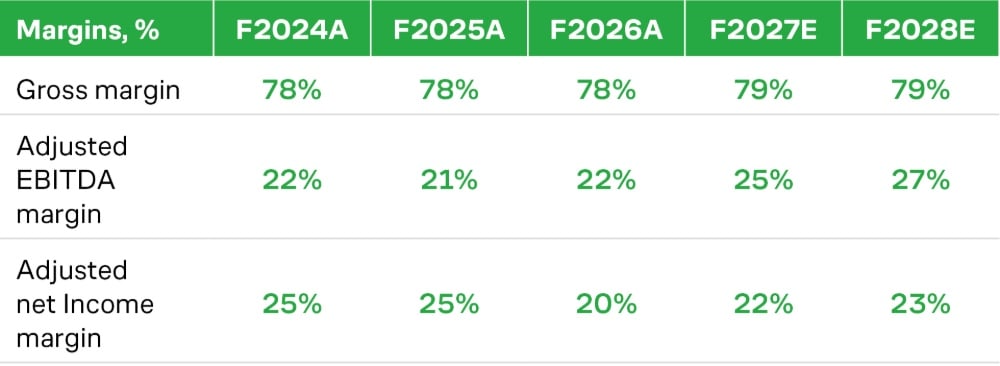
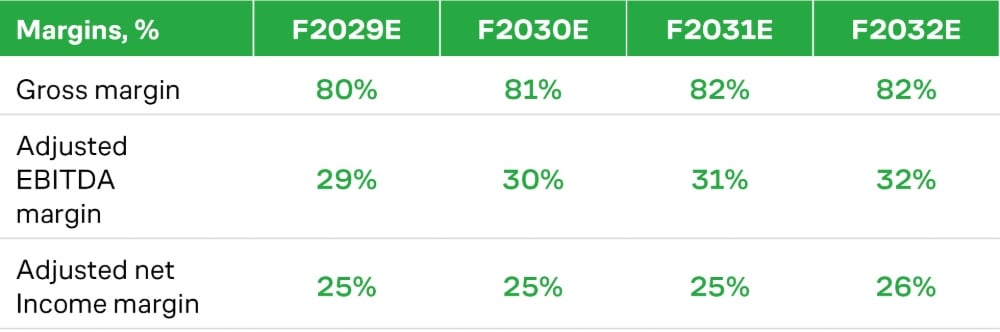
Operating model delivers superior operating leverage and ARR scale. CrowdStrike remains firmly on track toward its $10 billion ARR milestone, underpinned by net revenue retention (NRR) above 115% and increasing module adoption among customers with five or more modules. Subscription gross margins near 80% combined with 30–35% free cash flow margins place the company comfortably at the top tier of the "Rule of 40/50," providing strong valuation support even amid broader tech-sector volatility.
We recommend a long position in CrowdStrike (CRWD) with a price target of $320 and a stop-loss of $200.