
Financier №3 (43) 2026
Assem Agi
Chief Client Relationship Manager, Freedom Finance Global
Beyond Oil
Is There an Alternative to the World’s Main Energy Resource?
Contrary to a widespread myth, oil is not running out. As of the end of 2024, global proven oil reserves stood between 1.57 and 1.76 trillion barrels. This is almost double the amount recorded 40 years ago, even though tens of billions of tons of this raw material have been produced from the ground since then. Therefore, the problem is not the supply of energy resources - there are currently enough of them. The problem lies in demand, and it is here that the key battle for oil’s future is unfolding.
The Outlet vs The Barrel
Renewable energy is most often cited as the main alternative to “black gold”, but in reality, it does not compete with oil. Solar panels and wind farms are displacing coal and gas, not extracted barrels. This is because oil has a multi‑component composition. According to OPEC, the transportation sector remains its primary consumer, accounting for over 60 % of global demand. Land transport consumes about 46 % of total energy carriers, air transport approximately 8 %, and maritime transport roughly 7 %. Another approximately 15 % of hydrocarbon feedstock is used in the production of plastics, fertilizers, and synthetic materials. Therefore, each industry will have to find its own way to replace oil.
In 2025, the Chinese corporation Dongfang Electric installed the world’s largest offshore wind turbine, with a capacity of 26 MW, capable of supplying energy to up to 55,000 households
In the automotive sector, electric motors are indeed displacing fossil‑fuel engines. The International Energy Agency (IEA) forecasts that the share of electric vehicles will exceed 50 % in new car sales by 2035. Over the next decade, expansion of the electric transport segment across all vehicle types (passenger cars, motorcycles, buses, and trucks) will eliminate the need for approximately 10 million barrels of oil per day. Global investment priorities are also shifting. In 2025, worldwide energy investments reached a record $ 3.3 trillion (IEA data). Moreover, clean energy received twice as much funding as oil, gas, and coal combined - approximately $2.2 trillion versus $1.1 trillion. Investments in solar generation amounted to around $450 billion, making it the largest single item on the global energy capital expenditure map. IEA Executive Director Fatih Birol described the current trend as the dawn of the “electricity era”: just 10 years ago, investments in fossil fuels were one‑third higher than those in the electric power sector, but today this ratio has reversed.
While the land transport sector already has viable alternatives to oil, in many other industries it remains an irreplaceable resource. For example, in petrochemicals, it is nearly impossible to substitute this key feedstock. According to the IEA (Global Energy Review 2025), the entire increase in global demand for liquid hydrocarbons was provided by the petrochemical industry from 2019 to 2024.
Wind power generation depends on petrochemicals. The gearbox and hydraulic system of an industrial wind turbine use between 300 and 1,500 liters of industrial oil.
The aviation and maritime sectors also continue to rely on oil‑derived products. Electric batteries are still too heavy for long‑haul flights, while the production of sustainable aviation fuel, biofuels, and hydrogen remains expensive and poorly scalable. Oil and petroleum products will remain in demand in these sectors for a long time, and demand is likely to keep growing.
This Is Not the End Yet
Discussions about the energy transition often focus on when global oil demand will reach its peak and begin to decline. Until recently, it was believed that this would happen around 2030. However, forecasts have shifted over the past year: now, the peak in oil consumption is expected only between 2032 and 2035.
At the same time, OPEC sees no signs of weakening demand and predicts consumption will grow to nearly 123 million barrels per day by 2050. In November 2025, the US investment bank Goldman Sachs (GS) raised its target for this indicator to 113 million barrels by 2040. British Petroleum’s (BP) base case scenario assumes that oil demand will peak at around 103.5 million barrels in the mid‑2030s, followed by a decline to 83 million by 2050. According to IEA estimates, global oil demand will reach its maximum - around 102 million barrels per day - by the end of the decade, after which it will stop growing, a situation that finance professionals refer to as “plateauing”.
Thus, there is no single agreed‑upon scenario for the future of the oil market: estimates differ both in terms of when the demand peak will occur and the scale of its subsequent decline. At the same time, many experts agree that the industry needs massive investments just to maintain production at current levels, as existing fields are depleting at an average rate of 4–5 % per year. OPEC estimates that the required investments in upstream infrastructure development will amount to $18.2 trillion through 2050. Nevertheless, the global economy reaching peak oil demand does not automatically mean a subsequent collapse. However, due to talk of oil’s imminent “decline”, companies may reduce their investments in production. This would further constrain supply and create conditions for price growth.
Oil demand will certainly not collapse overnight; instead, it will be gradually replaced across different industries. The key change will be in what oil remains needed for. According to IEA estimates, by the end of this decade, more than one‑sixth of global consumption of this feedstock will be used for the production of polymers and synthetic fibers. Therefore, even if oil’s role as the primary motor fuel gradually declines, its era as an industrial feedstock is far from over.
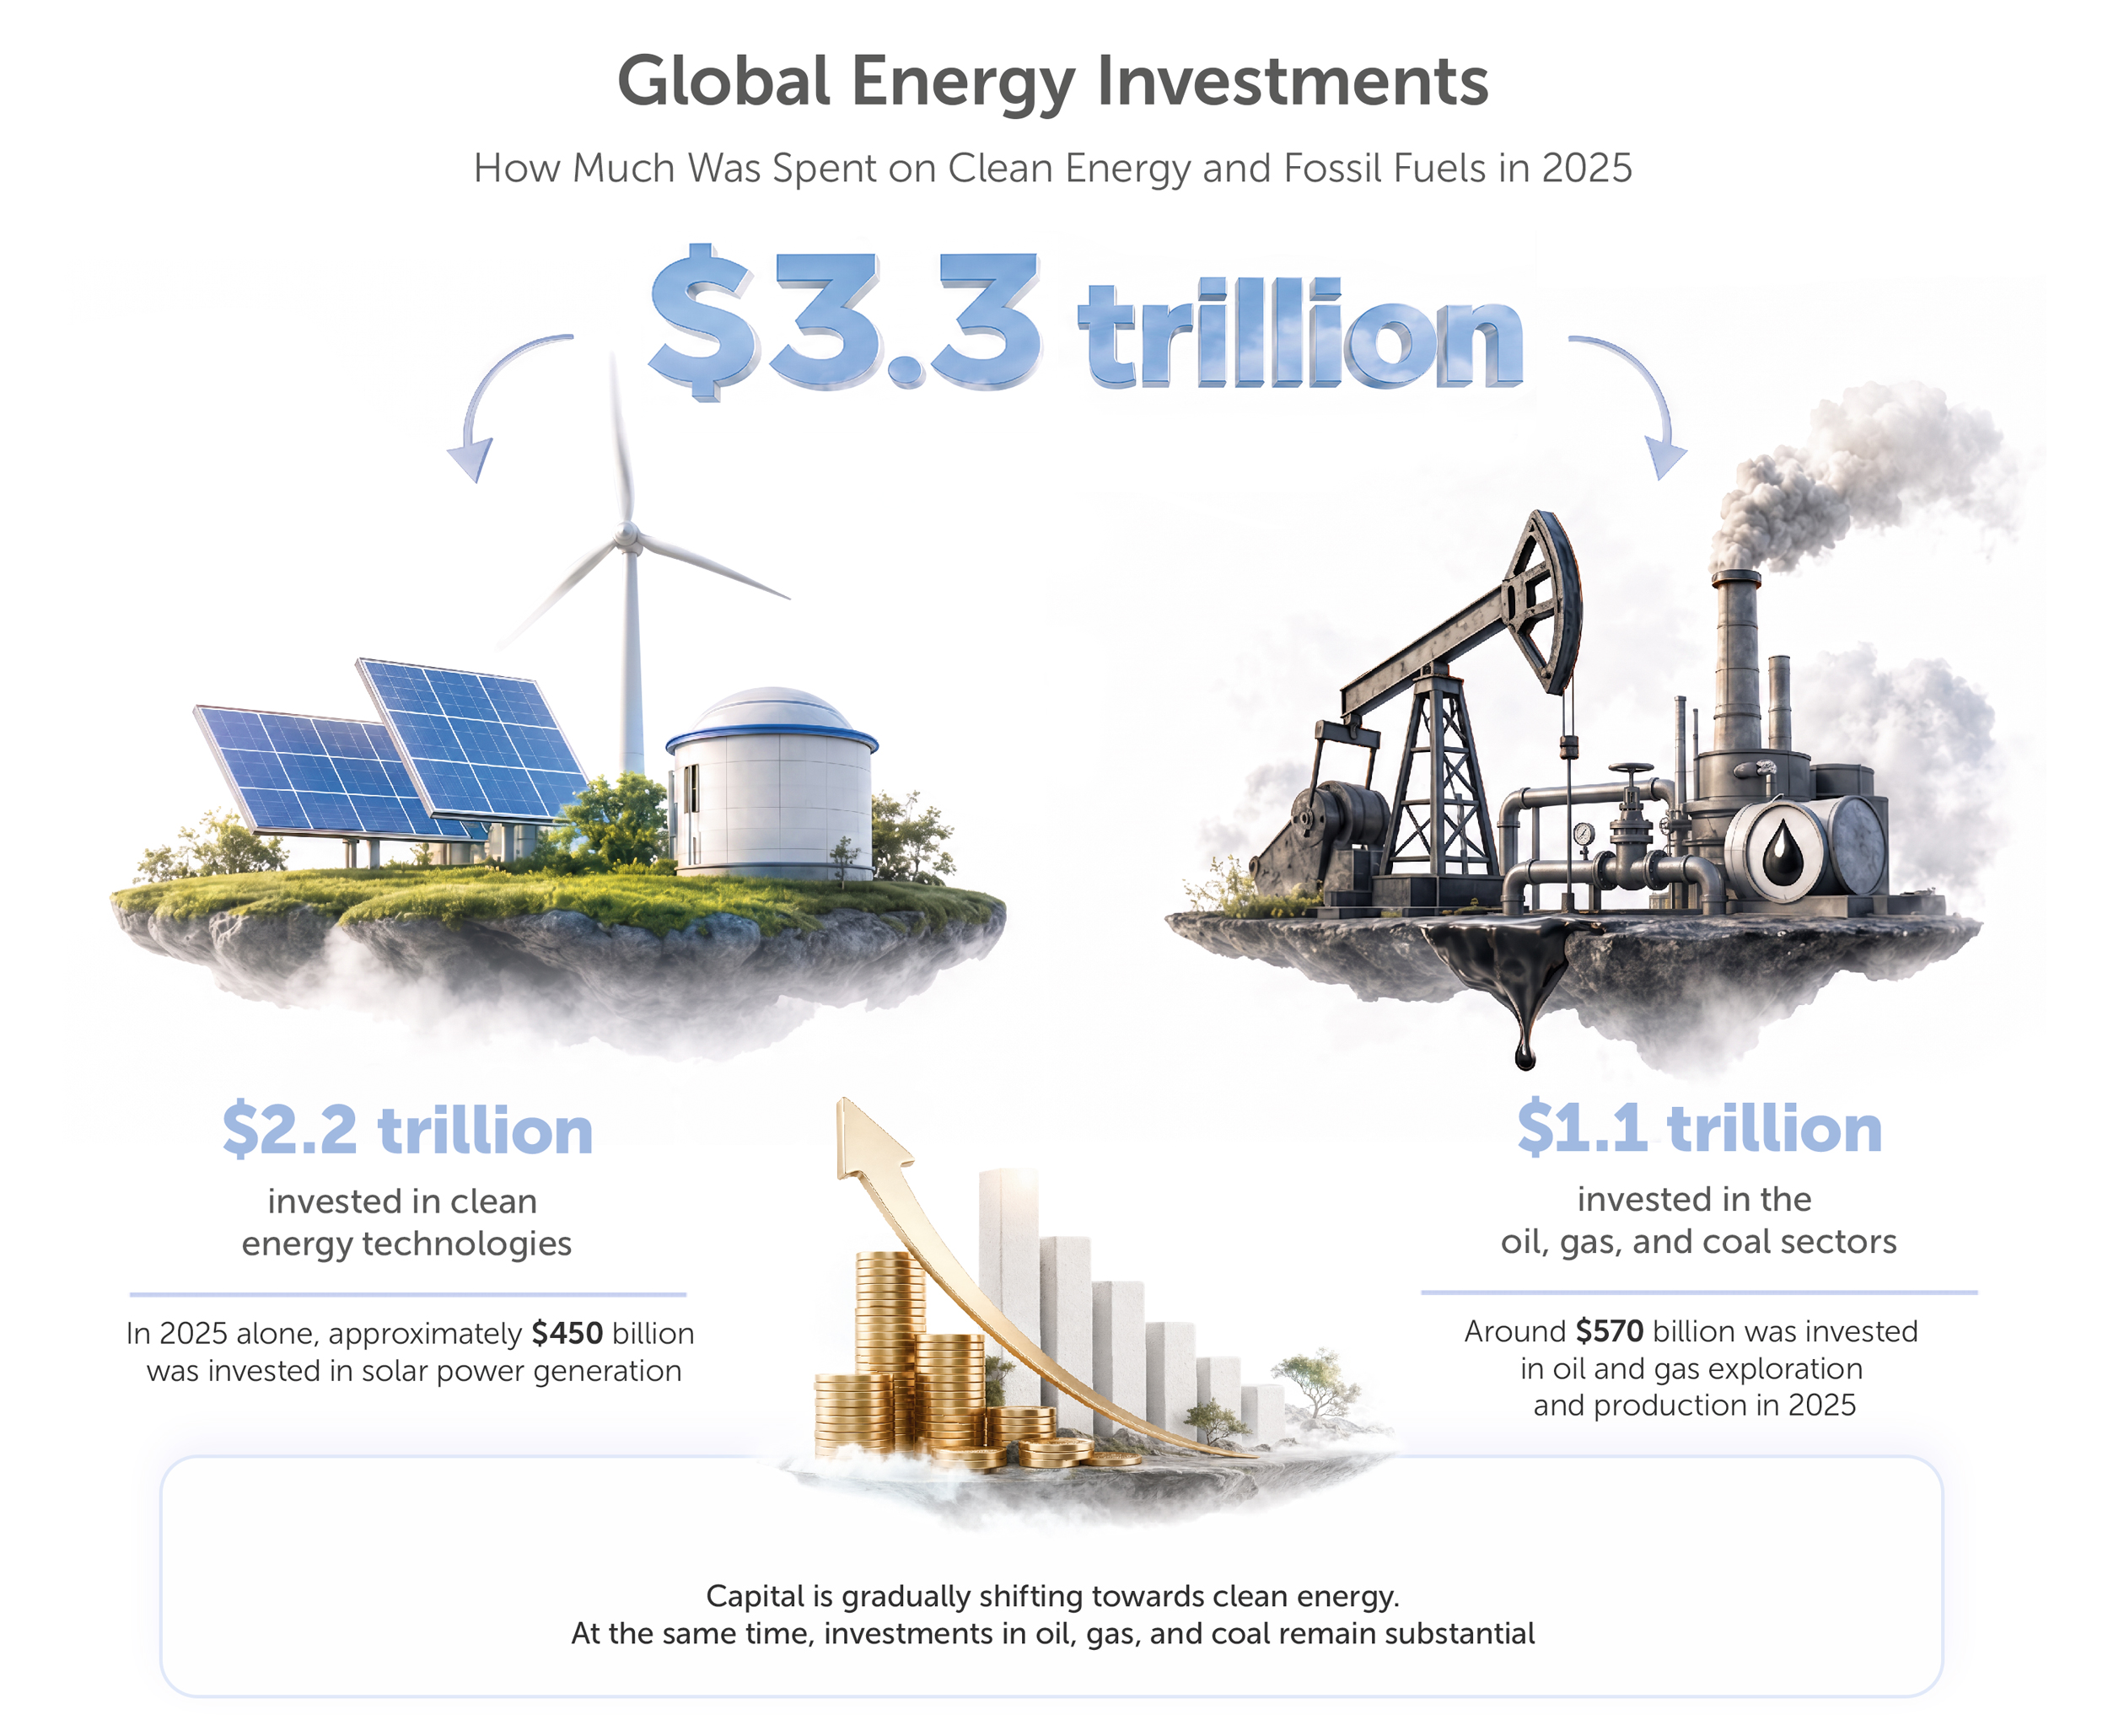
Source: IEA, World Energy Investment 2025